The Cheapest NVIDIA Has Looked All Month: What the Price Target Says
A brutal week of selling left NVIDIA at its cheapest valuation in months, but the fundamentals tell a completely different story than the price action suggests.

NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) closed at $216.47 on October 20, and our model says that price underestimates the business. The 24/7 Wall St. price target for NVIDIA is $258.42 over the next 12 months, implying 20.68% upside.
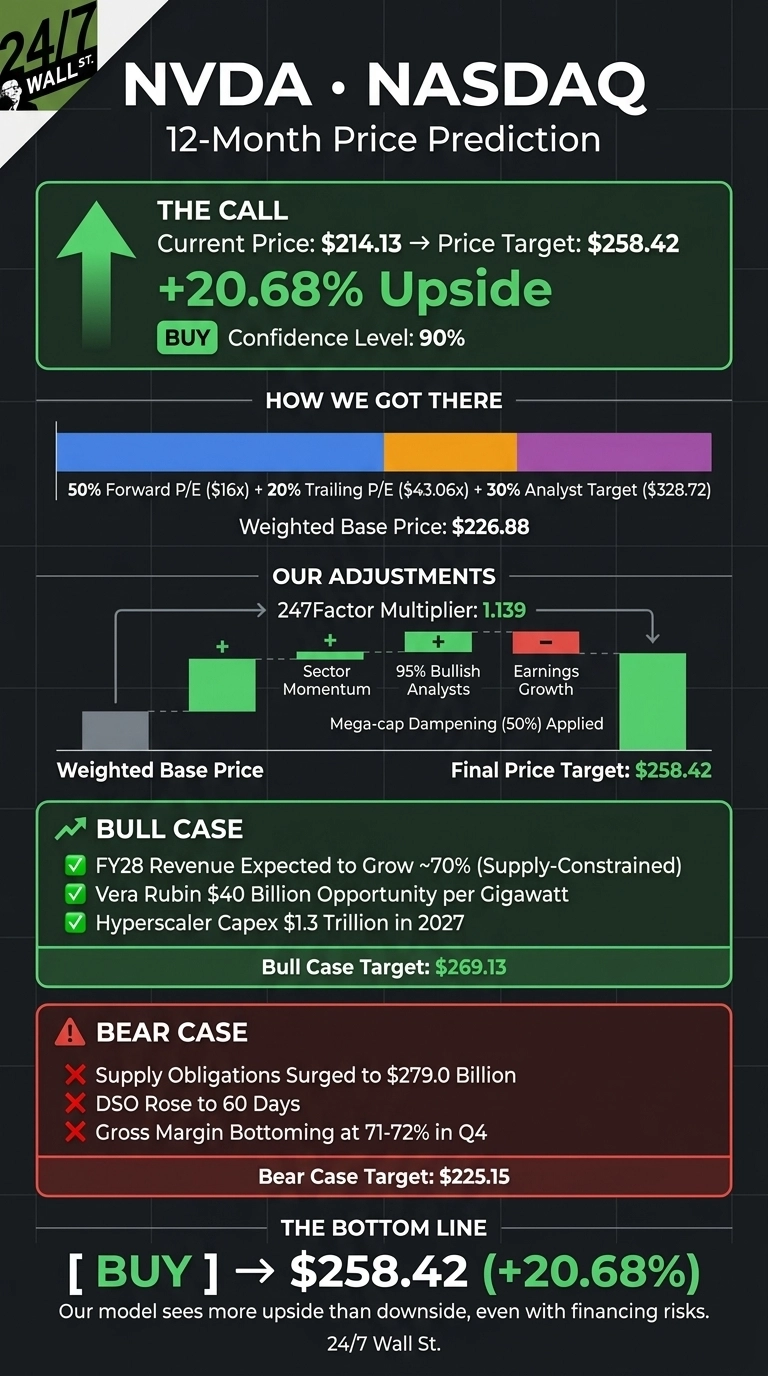

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $214.13 |
| 24/7 Wall St. Price Target | $258.42 |
| Upside/Downside | 20.68% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our model carries high confidence because NVIDIA trades at just 16 times forward earnings while revenue grew 105.8% year over year last quarter.
Wall Street agrees, with 59 Buy ratings against 2 Holds and 1 Sell. A sharp week of selling on AI financing concerns pulled shares lower, and our model treats that pullback as noise relative to the earnings trend.

AI Funding Jitters Drove a Weekly Slide Despite a Record Quarter
NVIDIA fell 6.61% over the past week, leaving shares up only 0.11% over the past month and 15.08% year to date. The stock sits between a 52-week high of $243.37 and a low of $163.90. The selloff tracked a global tech rout on AI funding worries, though CEO Jensen Huang said CoreWeave is improving and needs no backstop.
Fundamentals look far stronger. Fiscal Q2 2027 revenue reached $96.22 billion versus a $92.07 billion estimate, and non-GAAP EPS of $2.22 exceeded the $2.09 estimate, marking a fifth consecutive beat. Data Center revenue rose 117% to $89.02 billion.

Why Bulls See $269 and Beyond
Management expects fiscal 2028 revenue to grow about 70%, and called that outlook supply-constrained. Huang said, “We have supply for 70%. We have more supply than 70%, but about 70%. Our demand is much higher than that.”
Vera Rubin carries about $40 billion of revenue opportunity per gigawatt versus about $25 billion for Grace Blackwell, while top-five hyperscaler capex is expected to reach $1.3 trillion in 2027. Our bull case reaches $269.13, and the $328.72 consensus target shows how far optimists see room to run.
The capex wave reaches far beyond the GPU vendors, into the power, cooling, and networking suppliers quietly selling into every new data center (we pulled together seven of them in a report here: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers)).
Financing Exposure and Margin Pressure Worth Watching
Supply obligations grew to $279 billion, cloud-partner guarantees are capped at $108.5 billion, and days sales outstanding rose to 60 days from 45. Management acknowledged some may call its AI lab support “circular financing.”
Gross margin should bottom at 71% to 72% in Q4, and China data center computing is excluded from guidance. Our bear case lands at $225.15, still above today’s price.
The margin dip reflects rising memory costs, and management expects 72% to 73% in fiscal 2028 as price increases take effect.
NVIDIA Trades Cheaper Than AMD and Broadcom
Advanced Micro Devices (NASDAQ:AMD) is the most direct GPU rival, with a Meta deal for up to 6 gigawatts of Instinct GPUs. AMD trades at 40 times forward earnings on 50.11% revenue growth, a higher multiple for slower growth.
Broadcom (NASDAQ:AVGO) is the custom-silicon alternative for hyperscalers, with AI semiconductor revenue up 221% to $16.7 billion. At 19 times forward earnings, Broadcom is the closest valuation match.
| Company | Forward P/E | Latest Quarterly Revenue Growth |
|---|---|---|
| NVIDIA | 16x | 105.8% |
| AMD | 40x | 50.11% |
| Broadcom | 19x | 85.5% |
Applying Broadcom’s multiple to NVIDIA’s forward EPS implies about $255.89, close to our target. The peer group makes our 24/7 Wall St. price target look reasonable, even conservative.
Our Verdict: NVIDIA Earns a BUY Rating at $214
The 24/7 Wall St. price target of $258.42 carries a buy rating at 90% confidence. NVIDIA grows faster than its peers at a lower forward multiple.
Upside strengthens if Vera Rubin ramps on schedule and Q3 revenue lands near the $108 billion guide. The thesis weakens if AI lab financing stress turns into canceled orders. At this price, the model sees more upside than downside.
The chart below shows where our model projects NVIDIA could trade at each year-end, assuming current growth trend hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $219.16 |
| 2027 | $275.33 |
| 2028 | $309.60 |
| 2029 | $325.96 |
| 2030 | $368.42 |
These projections assume NVIDIA keeps executing on its current product cadence. China export policy, the strength of hyperscaler capex and custom silicon competition could move results sharply in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.