NVIDIA Trades at 13 Times Forward Earnings After a 27% Slide. Wall Street Still Sees $325+

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
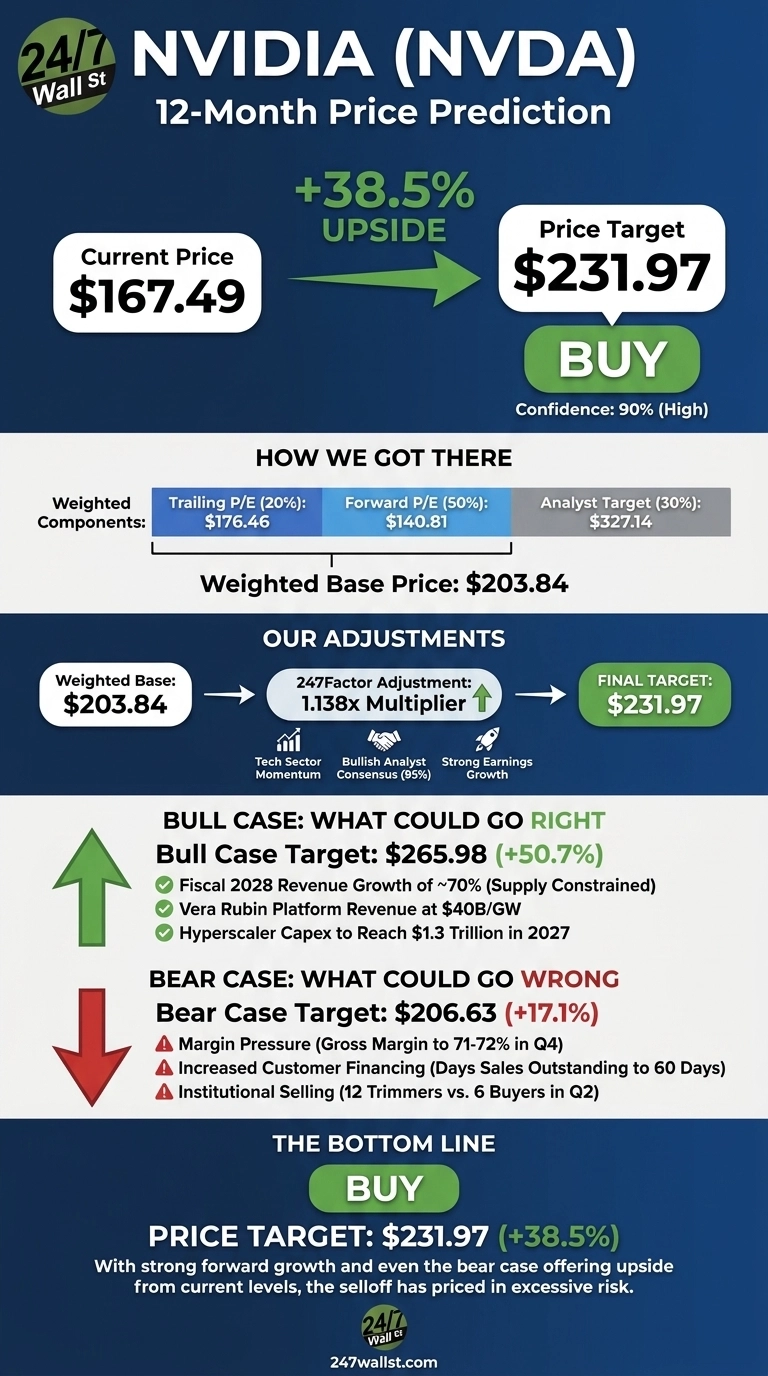
Our 24/7 Wall St. price target for NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) is $231.97. Shares traded at $167.49 at midday, so the target means about 38.5% upside. Our model rates the stock a buy with 90% confidence, which counts as high conviction.
| Metric | Value |
|---|---|
| Current Price | $167.49 |
| Price Target from 24/7 Wall St. | $231.97 |
| Upside/Downside | 38.5% |
| Recommendation | BUY |
| Confidence Level | 90% |

NVIDIA just doubled its revenue, yet the stock trades at about 13 times forward EPS of $13.1768. Wall Street’s consensus target of $326.92 sits well above our own figure.
Our model has held its buy rating through every weekly refresh since August 15, even as the target drifted lower along with the share price.
A 27% Monthly Plunge Pushed NVIDIA to the Edge of Its 52-Week Low
NVIDIA has fallen 17.11% over the past week and 26.95% over the past month. That leaves it down 9.98% year to date. The stock now sits about 31% below its 52-week high of $243.37 and only 2% above its low of $163.90.
Bloomberg called it a historic split from the S&P 500: NVIDIA kept dropping while the broader market rallied. The slide picked up speed in early November during a wider AI chipmaker selloff.

The business is still moving in the other direction. In fiscal Q2 2027, revenue rose 105.85% to $96.221 billion, ahead of the $92.069 billion consensus. Non-GAAP EPS of $2.22 also beat estimates, making it the sixth straight quarter of beats. For Q3, management guided to $108 billion in revenue, give or take 2%.
Vera Rubin and 70% Growth Drive the Case for $265
In our bull scenario, the stock reaches $265.98. On the August earnings call, CFO Colette Kress said NVIDIA expects “to grow revenue by approximately 70% in fiscal 2028. This is a supply-constrained outlook.”
Vera Rubin brings in about $40 billion per gigawatt, compared with $25 billion for Blackwell. Capex at the top five hyperscalers is expected to reach $1.3 trillion in 2027. Analysts are lopsidedly bullish, with 49 Buy and 10 Strong Buy ratings against a single Sell.

Margin Pressure and Customer Financing Could Cap the Rebound
Our bear case lands at $206.63, which is still above today’s price. Gross margin is expected to bottom at 71% to 72% in Q4 as memory costs rise. NVIDIA has also put nearly $50 billion into frontier AI labs, and days sales outstanding rose to 60 days. Among tracked institutional institutions, 12 trimmed their stakes in the June quarter, while only 6 added.
Each of these risks has a counterpoint. Management expects margins to return to 72% to 73% in fiscal 2028 once price increases kick in. It also says shipped compute goes to investment-grade customers or buyers backed by one.
NVIDIA Trades Below AMD and Broadcom on Forward Earnings
Advanced Micro Devices (NASDAQ:AMD) is NVIDIA’s most direct GPU rival. Its Data Center revenue rose 97% last quarter as its Instinct MI450 chips scaled up. Even so, AMD trades at 27 times forward earnings while growing revenue more slowly than NVIDIA.
With custom AI accelerators and networking chips, Broadcom (NASDAQ:AVGO) competes for the same hyperscaler budgets. AI semiconductor revenue rose 221%. Broadcom trades at 16 times forward earnings. At our target, NVIDIA would trade near 18 times forward earnings, still well below AMD. That makes our target look reasonable, even conservative.
| Company | Forward P/E | Latest Quarter Revenue Growth |
|---|---|---|
| NVIDIA | 13 | 105.85% |
| AMD | 27 | 44.68% |
| Broadcom | 16 | 85.5% |
Our Model Stays Bullish Because Even the Bear Case Points Higher
The 24/7 Wall St. price target of $231.97 comes with a buy rating and 90% confidence. Valuation decides it, since even our downside scenario sits above the current price.
I’d grow more confident if Q3 results confirm the $108 billion guide and Vera Rubin ramps on schedule. I’d get more cautious if margins fall below the guided floor or customer financing grows faster than revenue. At 13 times forward earnings, I think the selloff has priced in more risk than the numbers justify.
Here is where our model projects NVIDIA could trade over the longer term, assuming today’s growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $185.53 |
| 2027 | $231.79 |
| 2028 | $287.47 |
| 2029 | $334.82 |
| 2030 | $351.21 |
These projections assume NVIDIA stays on its current path. The biggest key factors are whether supply constraints ease or China export rules change.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.