NVIDIA Just Hit a New Buy Point. Morgan Stanley Raised Its Target. Where Does It End?
Morgan Stanley just raised its NVIDIA target as the stock closes in on all-time highs, but margin compression and a $50 billion financing controversy raise real questions about how much runway this rally has left.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Shares of NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) closed Friday at $233.95. That is within 1.7% of its 52-week high of $237.88, and the stock was indicated at $235.28 before the open.
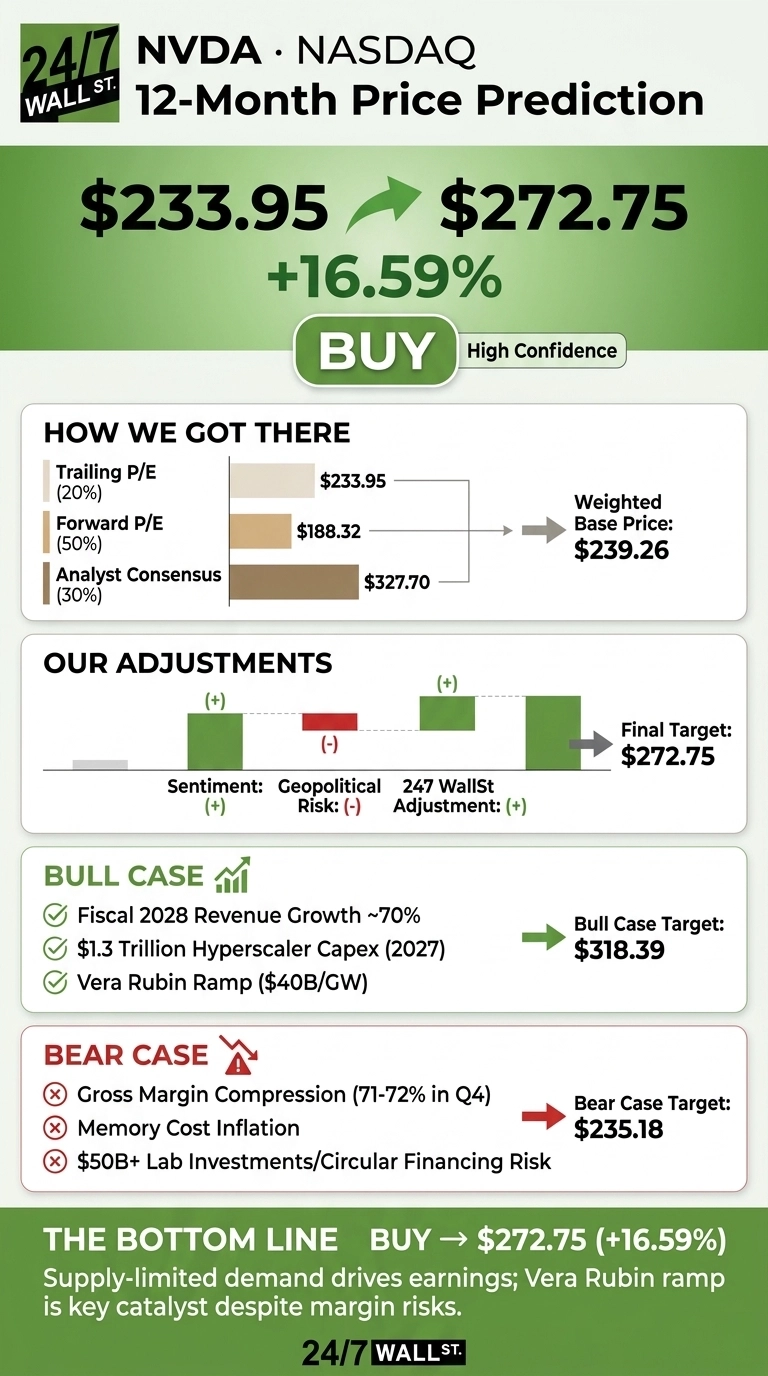
The 24/7 Wall St. price target stands at $272.75 over the next 12 months, which implies 16.59% upside. The stock earns a buy rating with high confidence from our model.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $233.95 |
| Price Target from 24/7 Wall St. | $272.75 |
| Upside/Downside | 16.59% |
| Recommendation | BUY |
| Confidence Level | 90% |
Shares traded near their 52-week high last week. Morgan Stanley (NYSE:MS) analyst Joseph Moore holds an Overweight rating. The key question now is how long supply limits support the cycle.

Record Highs Follow a $96 Billion Quarter
NVIDIA is up 4.54% over the past week, 4.97% over the past month and 26.45% year to date. The stock sits 42.7% above its 52-week low.
In the fiscal second quarter, revenue reached $96.22 billion against estimates of $92.07 billion. Non-GAAP EPS of $2.22 beat the $2.09 consensus. Data Center revenue rose 117% to $89.02 billion, and third-quarter guidance calls for $108 billion.

Why Bulls See $318 and Beyond
Management expects fiscal 2028 revenue to grow about 70% even with supply constraints. On the call, the company said “Our demand is much higher than that.” NVIDIA earns about $40 billion per gigawatt on Vera Rubin, compared with $25 billion on Blackwell.
The top five hyperscalers are expected to spend $1.3 trillion on capex in 2027. The consensus fiscal 2028 EPS estimate of $15.6951 has drawn 42 upward revisions and no cuts in 30 days. The average analyst target is $327.70, and our bull case points to $318.39.

Margin Compression and Vendor Financing Could Cap Gains
Management expects gross margins to bottom at 71% to 72% in the fourth quarter as memory costs rise. Days sales outstanding rose to 60 days from 45.
NVIDIA has invested nearly $50 billion in leading AI labs, and management admitted “some will call this circular financing.” Guidance also assumes no China data center compute revenue.
Bulls have a response: price increases should raised fiscal 2028 margins to 72% to 73%, and NVIDIA computing capacity can be moved to other customers. The bear case sits at $235.18.
NVIDIA Trades Between Broadcom and AMD on Forward Earnings
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| NVIDIA | 25x | 105.9% |
| AMD | 40x | 50.1% |
| Broadcom | 19x | 85.5% |
| TSMC | 21x | 36% |
Advanced Micro Devices (NASDAQ:AMD) competes directly with NVIDIA in GPUs but trades at a much higher forward multiple while growing revenue at less than half NVIDIA’s pace.
Broadcom (NASDAQ:AVGO) builds custom chips for the same hyperscalers at a cheaper multiple, reflecting market skepticism of AI silicon outside NVIDIA’s ecosystem.
Taiwan Semiconductor (NYSE:TSM) makes Blackwell and Rubin wafers. Compared with this group, NVIDIA’s premium appears justified, and our 18x forward input looks conservative.
Our Model Still Sees Room to Run
The 24/7 Wall St. price target sits at $272.75 with a buy rating and high confidence. Supply-limited demand keeps driving earnings estimates higher.
The setup improves if Vera Rubin supply expands on schedule and weakens if memory costs push margins below guidance. Keep an eye on the November earnings report.

Looking further out, here is our model projects NVIDIA could trade, assuming current growth rates and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 (12-month) | $272.75 |
| 2027 | $287.46 |
| 2028 | $307.06 |
| 2029 | $327.99 |
| 2030 | $357.65 |
The projections rest on NVIDIA executing its annual architecture cycle. Faster AI capex buildout could driving results above this path; a consolidation phase could pull them below. All of that hyperscaler spending has to be powered, cooled, and connected by somebody other than the chipmakers, and we rounded up seven of those suppliers in a free report here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.