The Coinbase Bull Case Comes Down to One Very Big Number
Coinbase shares have been cut nearly in half over the past year, yet one staggering market projection sits at the heart of the bull case and could justify a dramatic reversal if it plays out.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
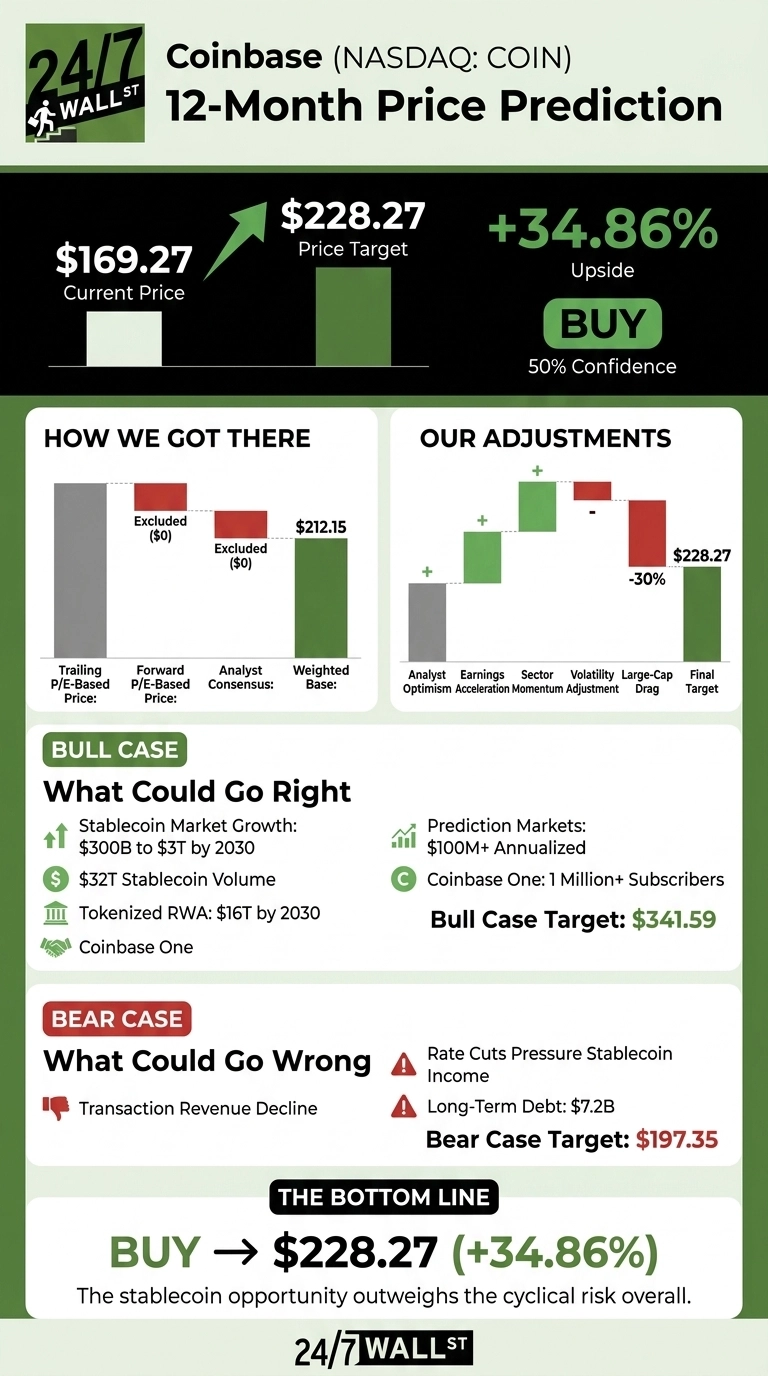
Our 24/7 Wall St. price target for Coinbase (NASDAQ:COIN | COIN Price Prediction) is $228.27 over the next 12 months. From the current price of $169.27, that means 34.86% upside. Our model rates the stock a buy with moderate confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $169.27 |
| Price Target from 24/7 Wall St. | $228.27 |
| Upside/Downside | 34.86% |
| Recommendation | BUY |
| Confidence Level | 50% |

That target may look high for a stock with back-to-back GAAP losses. The bull case rests on one very big number: a stablecoin market that Coinbase expects to grow from $300B to $3T by 2030. Through USD Coin (CRYPTO:USDC) economics and its Base blockchain, Coinbase sits close to the center of that market.
A Steep One-Year Slide Meets Multi-Year-Low Volatility
Shares fell 5.32% over the past week and 12.07% over the past month. They are down 24.47% year to date and 49.17% over one year, inside a 52-week range of $139.11 to $373.25.
Second-quarter revenue came in at $1.22B, down 18.5% year over year and short of the $1.29B consensus. EPS was -$1.36, missing the -$0.2278 estimate, as spot volume fell 25% from the prior quarter.
There were bright points, though. Trading market share reached an all-time high of 10.3%, and adjusted EBITDA of $207.8M was positive for the 14th consecutive quarter.
Why Bulls See $341 Ahead
Our bull case reaches $341.59. Stablecoins do much of the work.
CEO Brian Armstrong said Base processed about “$32 trillion in the last 12 months of stablecoin transfer volume,” and average USDC held in Coinbase products hit $20B. Tokenized real-world assets, which Coinbase projects could grow to $16T by 2030, add a second path to growth.
Prediction markets topped $100M annualized, and Coinbase One “passed a million subscribers.” CFO Alesia Haas pointed out that subscriber growth happened “during a down market.” Among analysts, 4 rate the stock Strong Buy and 19 rate it Buy.

What Could Go Wrong for Coinbase
Our bear case is $197.35, but a retest of the 52-week low is a real risk. Transaction revenue tracks volatility, and Q3 transaction revenue through July 26 was only about $130M. Rate cuts squeeze stablecoin income, and long-term debt has climbed to $7.2B.
One analyst rates the stock Sell and 1 rates it Strong Sell. There is a counterpoint: much of the Q1 loss came from $482.4M in losses on crypto held for investment, which were largely non-cash. Cash also stands at $8.61B.
Coinbase vs. Robinhood, Interactive Brokers and CME Group
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| Coinbase | N/A | -18.5% |
| Robinhood | 45x | 32.3% |
| Interactive Brokers | 28x | 13.5% |
| CME Group | 22x | 0.8% |
Robinhood Markets (NASDAQ:HOOD) competes directly with Coinbase for retail crypto and stock investors. It is valued at $88.89B, compared with Coinbase’s $38.02B, which shows what the market pays for multi-asset growth.
Interactive Brokers (NASDAQ:IBKR) is a brokerage with steadier growth, and its 1.37 beta contrasts sharply with Coinbase’s.
CME Group (NASDAQ:CME) lists crypto futures, which makes it the benchmark for Coinbase’s derivatives ambitions through Deribit. CME earns a 63.4% profit margin. Next to these peers, our target looks reasonable if transaction revenue recovers.
BUY Rating Rests on Stablecoin Scale
The 24/7 Wall St. price target of $228.27 carries a buy rating at 50% confidence. What tips the scale is subscription and services revenue, now 48% of net revenue.
I’d grow more constructive if crypto volatility comes back while USDC balances keep rising. I’d stay cautious if the next earnings report shows another quarter of shrinking transaction revenue. The stablecoin opportunity outweighs the cyclical risk overall.
Here is where our model projects Coinbase could trade if current growth trends and market conditions hold over the longer term.
| Year | Base Case | Bull Case |
|---|---|---|
| 2026 | $179.50 | $207.42 |
| 2027 | $237.29 | $333.50 |
| 2028 | $285.68 | $522.93 |
| 2029 | $313.37 | $687.60 |
| 2030 | $394.06 | $857.39 |
These projections hinge on Coinbase continuing to carry out its Everything Exchange strategy. Results could land well above or below these figures depending on stablecoin adoption, crypto volatility and the outcome of the Clarity Act.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.