Netflix Stock Has a Long-Term Opportunity That Short-Term Investors May Be Missing
Netflix just posted a strong earnings beat, then watched its stock sink to near 52-week lows as investors fixated on one number in the outlook. The real story is what the market may be pricing in wrong.

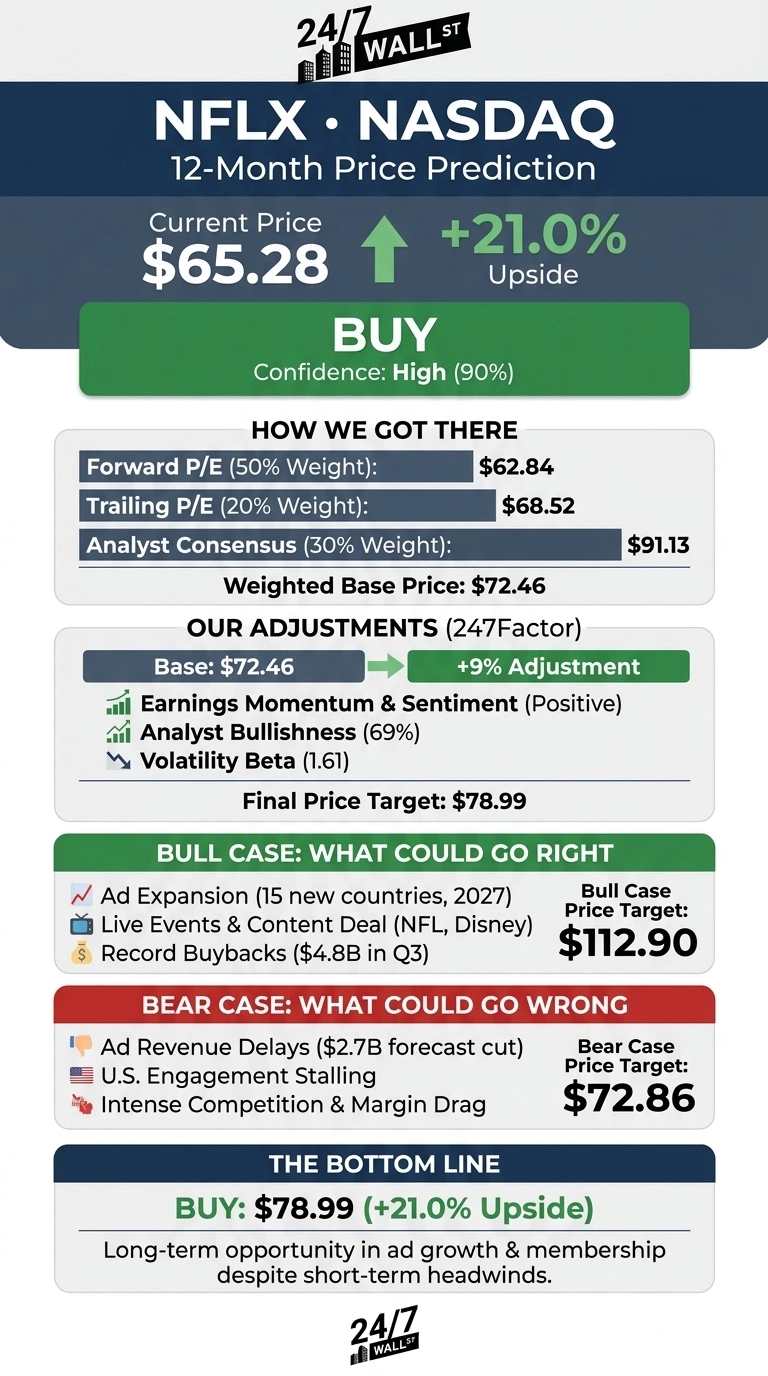
Our 24/7 Wall St. price target for Netflix (NASDAQ:NFLX | NFLX Price Prediction) is $78.99 over the next 12 months. Shares traded at $65.28 at midday on October 21. That places the target about 21.0% above the current quote.
The model’s own 15.27% upside figure was measured from the $68.52 close. Our rating is buy, and our confidence is high.
| Metric | Value |
|---|---|
| Current Price | $65.28 |
| Price Target from 24/7 Wall St. | $78.99 |
| Upside/Downside | 21.0% |
| Rating | BUY |
| Confidence Level | 90% |
The market is pricing in short-term frustration over ad schedule and U.S. engagement. Meanwhile, the long-term engine of pricing, membership growth and advertising continues compounding. We see the opportunity in the gap between sentiment and fundamentals.

Earnings Beat Collides With a Softer Forecast Near 52-Week Lows
Netflix fell 4.97% in today’s session. Shares are down 7.35% over the past week, 9.07% over the past month and 30.38% year to date. The stock sits just above its 52-week low of $65.08 and roughly 44% below its $116.73 high. Q3 revenue rose 11.85% to $12.87 billion, in line with estimates. EPS of $0.87 beat the $0.8229 consensus, and operating income climbed 37.26%.
The outlook is what spooked investors. Netflix cut its 2026 ad revenue forecast to about $2.7B from roughly $3B. It also guided to a Q4 operating margin of 26%, which includes a drag from headcount cuts.
Co-CEO Ted Sarandos acknowledged that Netflix “could do better”. Management responded by buying back 63.9M shares for $4.8B in Q3, its largest buyback quarter ever.
Why Bulls See $112.90 Within Reach
Netflix still expects full-year revenue of $51.1B (+13% YoY) and a 31.5% operating margin. The ad tier expands to 15 new countries starting March 2027, and management expects the ads business to grow over 80% this year even after the cut.
Live NFL games, a new licensing deal with Walt Disney (NYSE:DIS) and 24% growth in India view hours add more growth drivers. Of the analysts following Netflix, 35 rate it a Buy or Strong Buy. Our one-year bull case reaches $112.90.

Risks That Could Keep Netflix Range-Bound
Netflix admitted its U.S. slate is “just not growing as fast as it could”. Ad product delays and heavy competition for viewers’ time are real risks, and free cash flow guidance fell to $12B from $12.5B.
A real estate transaction drove the cash flow cut, and the margin drag comes from one-time layoffs. Co-CEO Greg Peters described the ad delay as “a modest short-term hit for a better long-term strategic position.” Our bear case still lands at $72.86.
Netflix Trades Between Disney and Spotify on Valuation
| Company | Forward P/E | Operating Margin (TTM) |
|---|---|---|
| Netflix | 19x | 33.4% |
| Spotify | 29x | 13.7% |
| Disney | 14x | 19.3% |
Spotify (NYSE:SPOT) is the closest pure-play subscription streamer, and its revenue rose 13.9% last quarter compared with Netflix’s 13.4%. Spotify earns a far lower margin yet trades at a much richer multiple.
Disney is Netflix’s main competitor and now also a content partner. It looks cheaper on earnings, but its revenue rose only 6.8%. Netflix offers growth on par with Spotify, the highest margin in the group and a mid-range multiple. Measured against these peers, our target looks reasonable, and arguably conservative.
Netflix Price Prediction 2026-2030
Our 24/7 Wall St. price target of $78.99 and our buy rating rest on 90% confidence. The deciding factor is a margin-rich business trading near its 52-week low while buying back stock at a record pace.
The bull case strengthens if ad monetization picks up after the 2027 expansion. The thesis weakens if U.S. engagement continues stalling into next year.

Our model projects where Netflix could trade if current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $68.80 |
| 2027 | $76.86 |
| 2028 | $87.70 |
| 2029 | $97.58 |
| 2030 | $101.57 |
The projections depend on Netflix continuing to execute its current strategy. Faster ad monetization would lift results well above this path, while weaker U.S. engagement could hold the stock back.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.