Netflix Stock Price Prediction: The Road Back to $100
Netflix shares have shed a third of their value in twelve months, but a powerful combination of record buybacks and a rapidly growing ad business is quietly building pressure beneath the surface.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Netflix has spent the last twelve months in the penalty box. After topping $126.71 last summer, shares of Netflix (NASDAQ:NFLX | NFLX Price Prediction) sit at $79.78 as of midday August 27, 2026, down 33.56% over the past year.
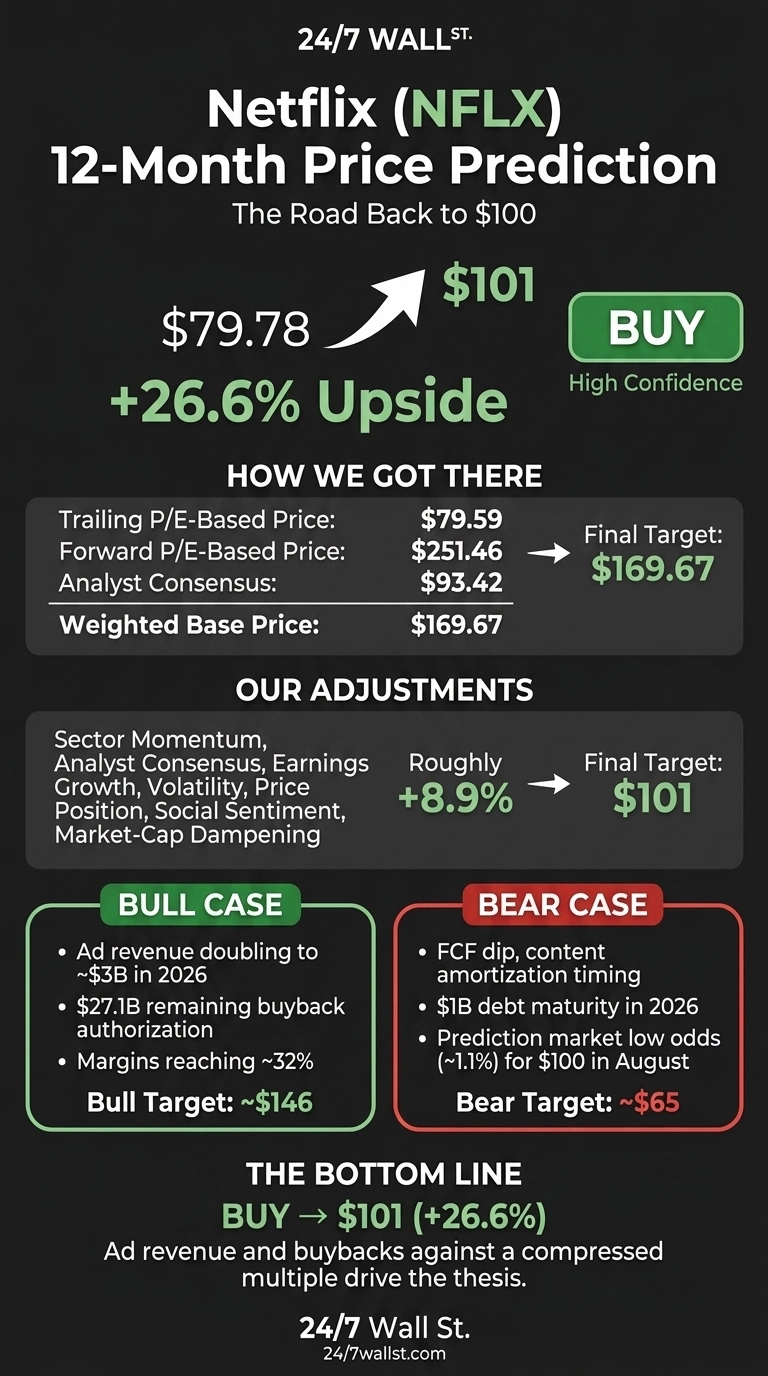
Our 24/7 Wall St. price target for Netflix is $101, implying 26.6% upside over the next 12 months. Our recommendation is buy at high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $79.78 |
| 24/7 Wall St. Price Target | $101 |
| Upside | 26.6% |
| Recommendation | BUY |
| Confidence Level | 90% |
How a Streaming Giant Fell Below $80
Netflix bounced sharply off lows, gaining 15.71% over the past month despite sitting down 13.12% year to date. The $65.08 52-week low came after July’s Q2 earnings, when shares fell 7.26% despite a modest EPS beat.
The quarter was solid: revenue of $12.56 billion grew 13.37% year over year, EPS of $0.80 topped the $0.7883 consensus, and operating margin hit 33.4%. The market reacted to a 32.73% drop in free cash flow to $1.53 billion, plus content amortization front-loaded in the first half.

Why Bulls See a Breakout Ahead
The bull case rests on advertising and buybacks. Management guides to $51 to $51.4 billion in 2026 revenue, 31.5% operating margin, and roughly $12.5 billion in free cash flow, with ad revenue doubling to about $3 billion. The ad tier drove over 60% of Q1 sign-ups in ad markets, and advertiser count is up 70% to more than 4,000 clients.
Netflix repurchased $4.7 billion of stock in Q2, its largest quarter ever, with $27.1 billion of authorization remaining. If ARPU keeps climbing and margins reach 32%, a bull scenario near $146 becomes reasonable within a year.

Risks Worth Watching
Content amortization was front-loaded, and Q1 2026 net income was inflated by a $2.80 billion Warner Bros. termination fee that will not repeat. Roughly $1 billion of debt matures later in 2026 into a higher-rate market. Prediction markets assign only 1.1% odds to NFLX hitting $100 in August.
Bulls counter that the FCF dip reflects higher cash taxes and content timing while underlying economics remain intact, and full-year FCF guidance holds at $12.5 billion. A bearish scenario retesting the $65 low is possible if ad growth stalls.

How Netflix Compares to Disney and Spotify
Walt Disney (NYSE:DIS) trades at a trailing P/E of 15 with an operating margin of 14.6%. Disney is cheaper on earnings, but Netflix’s 33.4% Q2 operating margin more than doubles Disney’s, justifying the multiple premium and supporting our $101 target.
Spotify (NYSE:SPOT) trades at a trailing P/E of 51 with 777 million MAUs. Spotify carries roughly twice Netflix’s multiple on similar top-line growth, framing our 24/7 Wall St. price target as conservative.
Why the Setup Looks Attractive Here
The 24/7 Wall St. price target for Netflix is $101, a buy at high confidence. The tipping factor is doubling ad revenue and record buyback pace against a compressed multiple.
The setup looks constructive if Q3 confirms the 33.2% operating margin guide and ad revenue stays on track for $3 billion. The thesis weakens if free cash flow slips further and the 2026 debt refinance surprises on cost.
The analyst community agrees: 29 Buys and 7 Strong Buys against zero Sells, with an average target of $93.42.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $101 |
| 2027 | $122 |
| 2028 | $148 |
| 2029 | $172 |
| 2030 | $195 |
These projections assume Netflix executes on its ad monetization roadmap and holds margins near 32%. Meaningful upside or downside could result from a step-change in live sports rights economics or an unexpected consumer spending pullback.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.