Netflix Is Playing a Bigger Game. Investors Should Take Notice
Netflix posted record profits, bought back nearly $5 billion of its own stock, and signed deals with Disney and the NFL, yet shares sit just above a 52-week low. Something about that gap deserves a closer look.

Netflix (NASDAQ:NFLX | NFLX Price Prediction) spent 2026 extending its reach. It added live NFL games, built its own ad technology and brought outside networks onto its platform.
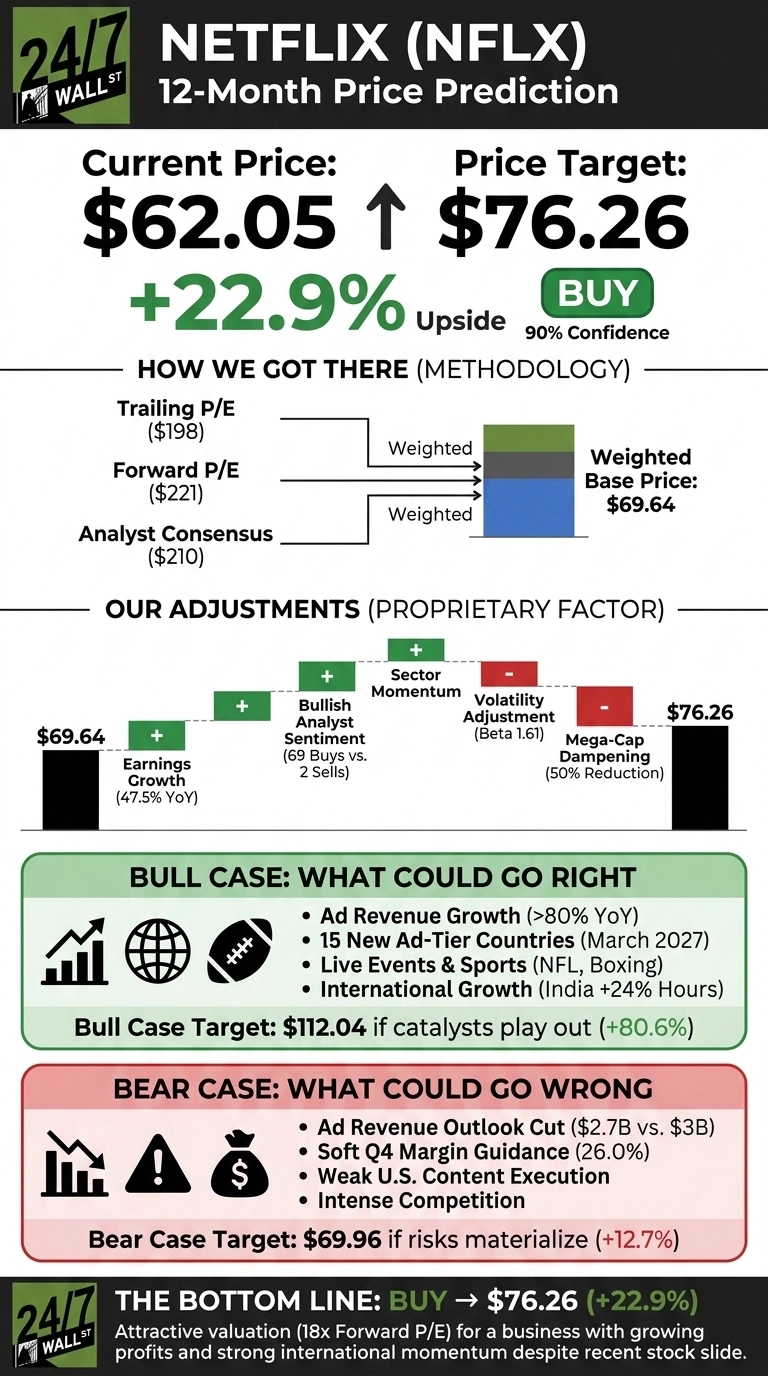
The stock fell anyway, and that gap is why the setup deserves a closer look. The 24/7 Wall St. price target for Netflix is $76.26, which means 22.9% upside from $62.05.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $62.05 |
| Price Target from 24/7 Wall St. | $76.26 |
| Upside/Downside | 22.9% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our model’s confidence is high. Netflix trades at a forward P/E of 18 and guides to 20%+ operating income growth in 2026. At that price, investors are paying a value multiple for a business whose profits are growing.
A 33% Slide Despite Record Profitability
Shares are down 6.67% over the past week, 10.98% over the past month and 33.26% year to date. The stock now sits just above its 52-week low of $61.39 and far below its high of $116.73. Since the earnings report, Morningstar has publicly asked whether the slide makes the stock a buy.
Third-quarter EPS came in at $0.87, beating the $0.8229 estimate. Revenue of $12.874 billion was about in line with estimates and grew 11.8%. Operating margin extending to 34.6% from 28.2%.
Netflix also bought back 63.9 million shares for $4.8 billion, its largest repurchase quarter ever. Earlier in the year, Netflix walked away from its interest of Warner Bros. Discovery (NASDAQ:WBD) and collected a $2.8 billion termination fee.

Why Bulls See $112 Ahead
Our one-year bull case reaches $112.04. Advertising is the main driver. Co-CEO Greg Peters said, “We are still growing our ads business over 80% this year.” The ad tier launches in 15 new countries starting March 2027. India’s view hours rose 24%, and non-English viewing now makes up more than a third of the total.
A new licensing deal with Walt Disney (NYSE:DIS) and live events, including a Christmas Day NFL doubleheader, add more fuel. Of the analysts covering the stock, 7 rate it Strong Buy and 28 rate it Buy.

Risks That Could Keep Netflix Pinned Near Its Lows
Netflix cut its 2026 ad revenue outlook to about $2.7 billion from $3 billion after delays in rolling out ad products. Its fourth-quarter operating margin guidance of 26% also looks soft.
That figure includes about 120 basis points of one-time costs from headcount reductions, and full-year margin guidance still stands at 31.5%. The bear case lands at $69.96. Even so, weak U.S. content execution could push shares through the 52-week low.

Netflix Sits Between Disney and Spotify on Valuation
Disney goes head to head with Netflix in streaming. It changes hands at a trailing P/E of 15 with an operating margin of 14.6%, about half of Netflix’s.
Spotify (NYSE:SPOT) is a fellow subscription-and-ads platform, and it commands 52 times earnings despite thinner margins.
| Company | Trailing P/E | Operating Margin |
|---|---|---|
| Netflix | 24 | 29.49% |
| Disney | 15 | 14.6% |
| Spotify | 52 | 12.8% |
Netflix’s margins are well above both peers, yet its multiple sits closer to Disney’s than to Spotify’s. That gap makes the 24/7 Wall St. price target look conservative.
Discounted Shares With Profits Still Growing
The 24/7 Wall St. price target of $76.26 carries a buy rating and 90% confidence. Valuation drives the call: a forward multiple of 18 for a business guiding to $51.1 billion in revenue this year.
The upside case strengthens if the ad product launch gets back on schedule in 2027. Continued decline in U.S. engagement would weaken it. For now, the risk and reward favor the upside.
Further out, here is where our model’s base case projects Netflix could trade, assuming current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $66.43 |
| 2027 | $77.14 |
| 2028 | $92.18 |
| 2029 | $98.74 |
| 2030 | $108.71 |
Netflix would need to keep executing on its current strategy for these projections to hold. Faster ad monetization could push results toward our five-year bull case of $241. A stalled turnaround in U.S. content could drag them toward the downside scenario.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.