The Next $100 Billion of Netflix’s Value Could Come From Here, 98% Upside Ahead
Netflix shares have shed more than a third of their value over the past year, yet the company's ad business is exploding and buybacks are hitting record pace. Our proprietary model sees a stark disconnect between where the stock trades…

Netflix (NASDAQ:NFLX | NFLX Price Prediction) has spent the last year giving back gains from its 2025 highs, but our proprietary model sees the setup as a rare mispricing in a mega-cap growth name.
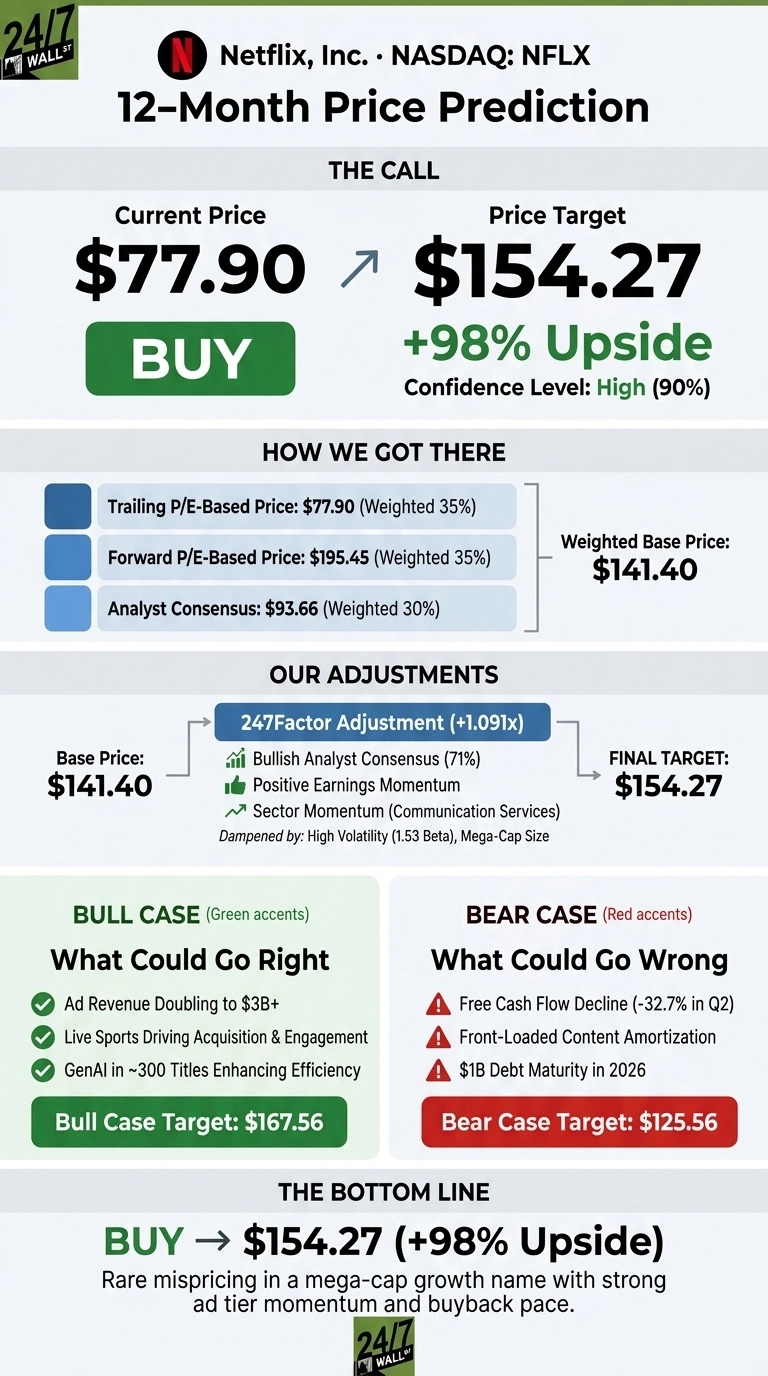
With the stock trading at $77.90 after a 35.21% one-year decline, the doubling of the ad business, a record buyback pace, and stubborn subscription pricing power all argue the shares are pricing in far too much caution.
| Metric | Value |
|---|---|
| Current Price | $77.90 |
| 24/7 Wall St. Price Target | $154.27 |
| Upside | 98.04% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our 24/7 Wall St. price target for Netflix is $154.27 over the next 12 months, implying 98% upside from here. That is one of the widest gaps we carry on a mega-cap, and our confidence is high.
Ad Doubling and a Record Buyback Reset the Story
Netflix shares are down 16.92% year-to-date and off 25% from a 52-week high of $124.86, yet the operating story keeps improving.
Q2 2026 revenue rose 13.37% to $12.56 billion with operating margin at 33.4%, and EPS of $0.80 beat consensus. Management guided full-year revenue to $51 to $51.4 billion, with ad revenue set to roughly double to $3 billion and free cash flow near $12.5 billion.
The board also authorized an incremental $25 billion in buybacks on top of remaining capacity, and Q2 repurchases of $4.7 billion were the largest quarter in company history. Netflix ultimately walked away from the pursuit of Warner Bros. Discovery (NASDAQ:WBD) and pocketed a $2.8 billion termination fee, refocusing capital on organic growth.

Why Bulls See a Breakout to $167
The bull case is straightforward. Management describes an addressable base of roughly 800 million households and just 7% of addressable revenue captured.
Doubling ads to $3 billion, live-sports rights that drove six of the top 10 sign-up days over the past five years, and GenAI in roughly 300 titles all support double-digit revenue and 20%+ operating income growth.
Our bull scenario puts the shares at $167.56 a year out. Analysts already lean heavily positive with 7 Strong Buys, 29 Buys, and 15 Holds.

What Could Go Wrong
The risks are real. Free cash flow fell 32.73% year over year in Q2 on higher cash taxes, content amortization is front-loaded in H1, and $1 billion in debt matures later in 2026.
Bulls would counter that the cash flow decline is a timing item and that content amortization growth of 10% still trails revenue growth. Our bear scenario at $125.56 assumes sports rights inflation and FX pressure erode margin, but even that outcome sits 61% above the current price.

How Netflix Compares to Disney, Spotify, and Warner Bros. Discovery
Disney (NYSE:DIS) is the closest scaled peer with combined Disney+/Hulu SVOD posting 15% subscription revenue growth last quarter, yet trades at a P/E of 15, roughly half of Netflix at 30. Disney’s operating margin of 15% also trails Netflix’s 29.49%, which supports Netflix’s premium multiple.
Spotify (NYSE:SPOT) offers the growth-multiple contrast, carrying a P/E near 52 on 777 million MAUs and 13.9% Q2 revenue growth. If Spotify commands that multiple on similar top-line, Netflix at 30x, with far higher margins and buyback firepower, looks conservatively valued and makes our $154 target defensible.
Warner Bros. Discovery is the M&A reference point. Its Streaming Adjusted EBITDA jumped 63% ex-FX in Q2, but the pending Paramount Skydance merger and 3.4x net leverage highlight why Netflix’s decision to keep its balance sheet clean matters.
| Company | P/E | Operating Margin |
|---|---|---|
| Netflix | 30 | 29.49% |
| Disney | 15 | 14.65% |
| Spotify | 52 | 12.79% |
Setup Looks Compelling at $77.90
The setup looks attractive at $77.90 as long as Q3 revenue comes in near the $12.86 billion guide and ad revenue tracks toward $3 billion.
The thesis weakens if operating margin slips below 30% or if sports rights bidding pushes content amortization above revenue growth. With the 24/7 Wall St. price target at $154.27, a buy recommendation, and 90% confidence, the risk-reward tilts firmly bullish.
Looking further out, here is where our model projects Netflix could trade, assuming current growth and margin trajectories hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $92 |
| 2027 | $170 |
| 2028 | $264 |
| 2029 | $366 |
| 2030 | $443 |
These projections assume Netflix continues executing on ad-tier growth, disciplined content spend, and aggressive buybacks. A sharp step-up in live-sports rights spending or a global consumer downturn are the clearest paths to downside.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.