Palantir Investors Have One Big Number to Watch in 2027
Palantir trades near all-time highs while Wall Street sees almost no room left to run, yet one number looming on the 2027 horizon suggests analysts may be thinking far too small.

Palantir Technologies (NASDAQ:PLTR | PLTR Price Prediction) has grown into the operating system that both the Pentagon and corporate America use for AI. Gotham handles government work, Foundry runs commercial data, and AIP turns large language models into working agents.
Chief executive Alex Karp summed up the second quarter this way: “Demand for AI sovereignty has now been unleashed.”
The stock is up 12.17% year to date at $199.38. It has climbed 87% from its 52-week low of $106.37. The number I’m watching for 2027 is $300, and several catalysts could get Palantir there.

Wall Street Sees Little Upside, but Estimates Keep Rising
The consensus price target is $206.43, which implies only 3.5% upside. Analysts are split, with 19 Buy ratings against 9 Holds. Valuation explains the caution better than the fundamentals do.
For 2027, analysts expect revenue of $12.33 billion, up 50%. They see EPS of $2.3505, up 45%. Ninety days ago, the 2027 EPS forecast was $2.0945, so it has risen 12% since then.

Here’s the Math Behind a $300 Palantir
Today Palantir trades at about 85x estimated 2027 earnings. At $300, that multiple would rise to roughly 128x. That’s steep, but Palantir’s Rule of 40 score is 155% and its adjusted operating margin is 62%.
Few software companies have combined growth and profitability at this level. If 2027 earnings come in above forecasts, the multiple needed at $300 shrinks.
How might Palantir reach $300?
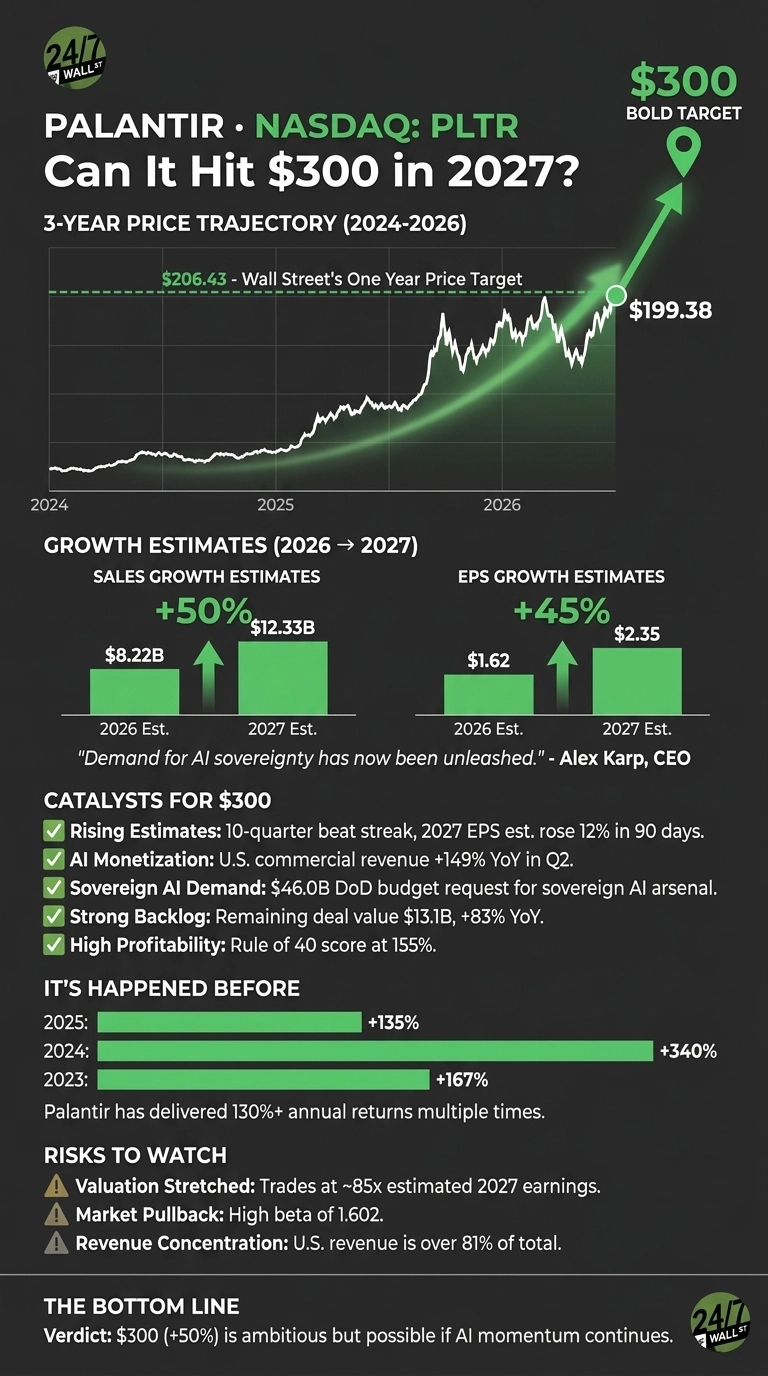
- A long beat streak: Palantir has topped estimates for 10 straight quarters. In Q2, EPS of $0.41 beat the estimate by 46.43%.
- Karp’s stretch goal: Karp said he is “driving the business to grow at a rate equal or above to what we have in U.S. commercial for the next 18 months.” U.S. commercial revenue grew 149% in Q2.
- Backlog: Remaining deal value reached $13.1 billion, up 83%. Net dollar retention hit 157%.
- Defense spending: The FY2027 Department of War budget request includes $46 billion for a sovereign AI toolkit. It also sets aside $2.3 billion for the Maven Smart System, a program Palantir already supports.

Palantir’s History Says 50% Gains Are Within Reach
Reaching $300 requires a gain of about 50%. Palantir has passed that bar several times. Shares rose 167% in 2023, 340% in 2024, and 135% in 2025.
Volatility cuts both ways, though. In 2022, the stock fell 65%. Its beta of 1.602 means a market pullback would hit Palantir harder than most stocks.

$300 Is a Stretch, but Here’s Why It’s Possible
Removing $300 means a gain of about 50%, far above what Wall Street’s target implies. Even so, the business is speeding up. Full-year 2026 revenue guidance calls for 82% growth, estimates are still climbing, and Palantir keeps beating them.
The main risks are the stock’s high valuation and its heavy reliance on U.S. customers. If AIP keeps converting pilot programs into large contracts and defense AI budgets come through, $300 is a reachable goal.
The traits that showed up early in past monster tech runs are the ones we cataloged in a free playbook on spotting the next Nvidia. Returns like this come unevenly from year to year, and this is the path for Palantir to post another outsized gain in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.