The Stocks Making Noise-And the Ones That Actually Matter
NVIDIA, Amazon, and Palantir are posting strong growth underneath a volatile October, but each stock needs something specific to happen before 2027 for bold price targets to hold up.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The AI trade has been volatile in late October. NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) is down 8.83% over the past month. Amazon (NASDAQ:AMZN) posted mixed Q3 results, and Palantir (NASDAQ:PLTR) is up just 5.83% year-to-date.
Underneath that volatility, all three businesses are posting strong growth, and here is what each stock needs to do to hit a bold 2027 target.
NVIDIA Has a Clear Path to $400 in 2027
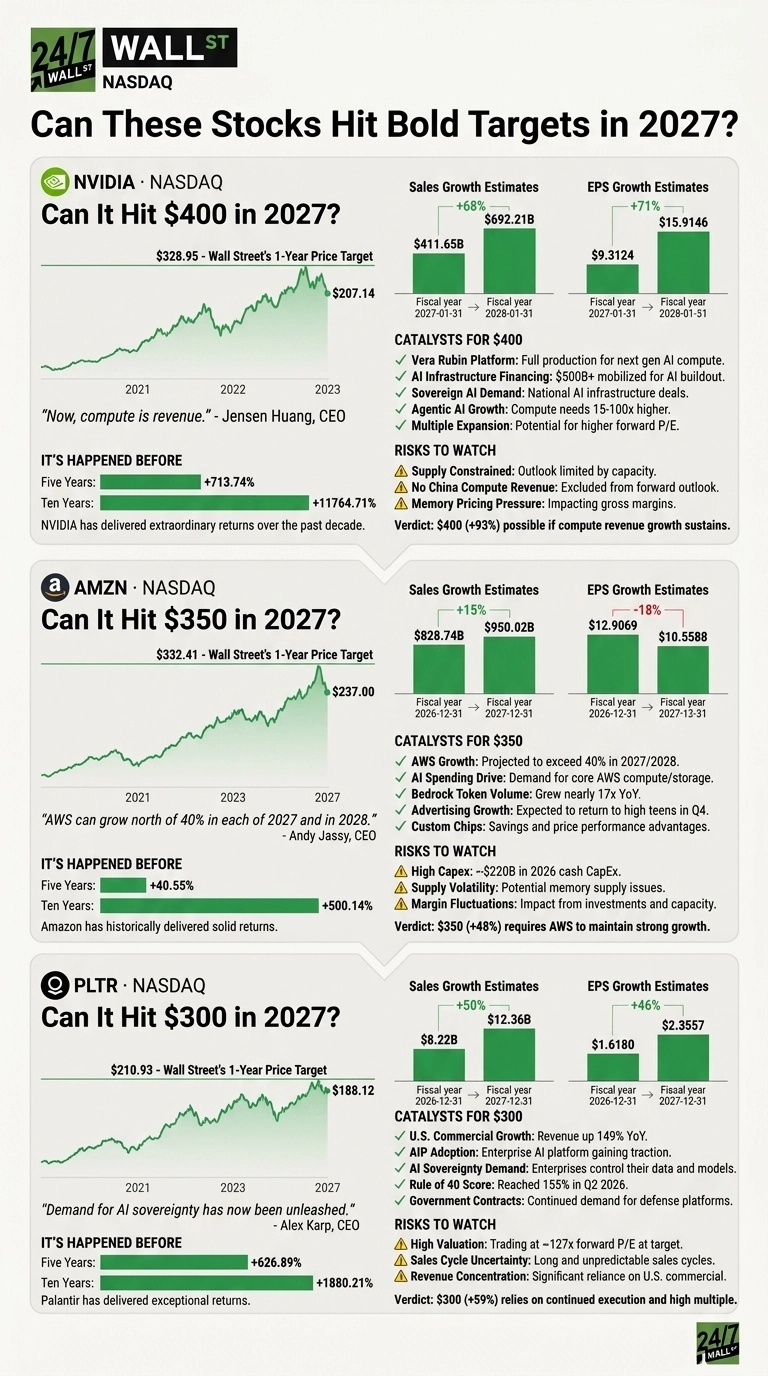
Jensen Huang summed up the thesis in one line: “Now, compute is revenue.” Fiscal Q2 revenue rose 105.8% to $96.22 billion, and EPS of $2.22 exceeded the $2.0887 estimate, the fifth straight beat. The CFO expects “to grow revenue by approximately 70% in fiscal 2028,” and calls that outlook supply-constrained.
Wall Street’s $328.95 target implies 59% upside from $207.14. Fiscal 2028 EPS estimates rose to $15.9146 from $12.8148 90 days ago. That puts shares at just 13x forward earnings.
At $400, NVIDIA would trade at 25x. That requires a 93% gain, but the stock has returned 713.74% over five years. The main hurdle is that the forecast assumes no China Data Center compute revenue.

AWS Acceleration Puts $350 Within Reach for Amazon
Q3 EPS of $1.89 missed the $1.9579 estimate, but AWS grew 39.3%, its sixth straight quarter of acceleration, with a $578 billion backlog. Andy Jassy said “AWS can grow north of 40% in each of 2027 and in 2028.”
The consensus target of $332.41 implies 40% upside from $237. 2027 EPS estimates rose to $10.5588 from $10.0087 90 days ago, which puts the stock at 22x.
At $350, the multiple would be 33x. That premium looks reasonable if Bedrock token volume keeps growing at anything close to the 17x it grew last year. The required 48% gain compares with 40.55% over five years, so Amazon needs a breakout year. Capex of $220 billion is the swing factor.

Palantir’s Growth Has to Keep Outrunning Its Multiple to Reach $300
Revenue grew 92.8% last quarter and U.S. commercial revenue rose 149%, raising the Rule of 40 score to 155%. Palantir has beaten EPS estimates 9 consecutive quarters. Alex Karp says “Demand for AI sovereignty has now been unleashed.” JPMorgan (NYSE:JPM) recently named it a favorite stock.
Wall Street’s $210.93 target implies 12% upside from $188.12. 2027 EPS estimates climbed to $2.3557 from $2.0945, putting the stock at 80x.
At $300, it would trade at 127x. That is steep, so the case depends on more beats pushing estimates higher. A 59% gain is modest next to the 626.89% five-year return.

Which of the Three Targets Looks Most Realistic
NVIDIA’s valuation math looks the most comfortable. Amazon’s case depends on AWS, and Palantir’s depends on execution. A weak market would make all three harder to reach.
Returns at these levels are rare, and this is how each stock could post outsized returns in 2027. The common thread is the data-center expansion underneath all of it, and we highlighted seven suppliers driving that boom, beyond the chipmakers, in a free report you can grab here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.