Prediction: Amazon Could Double by 2030 if This Part of Its Business Delivers
AWS just posted its fastest growth in 18 quarters, yet Amazon shares still sit well below their 52-week high. The path to $500 by 2030 exists, but it hinges on one part of the business clearing a very high bar.

Amazon (NASDAQ:AMZN | AMZN Price Prediction | AMZN Price Prediction) runs the world’s biggest cloud platform, and that cloud is speeding up again. AWS revenue reached $42.23B in Q2 FY26, up 37% YoY. That was its fastest growth in 18 quarters.
The stock is up 13.97% this year, which still trails what the business is doing. CEO Andy Jassy now says AWS could become “a trillion-dollar annual revenue business for us in time.” So can Amazon reach $500 per share by 2030?

Spending Fears Are Holding Amazon Back Right Now
Capex is the concern. Amazon raised its 2026 cash capex estimate to roughly $220 billion, up from about $200 billion, and cited higher memory costs. Free cash flow turned negative at -$7.6B TTM. Q3 guidance calls for only 9-12% sales growth, partly because Prime Day moved into Q2.
CNBC this week called it a “stumbling stock” that needs a path back to record highs. Shares sit at $262.59, below the 52-week high of $287.20. The past week (+1.74%) and month (+3.69%) show only a small rebound. With a beta of 1.456, the stock tends to amplify market moves.
Analysts Are Bullish, but Their Targets Stop Too Soon
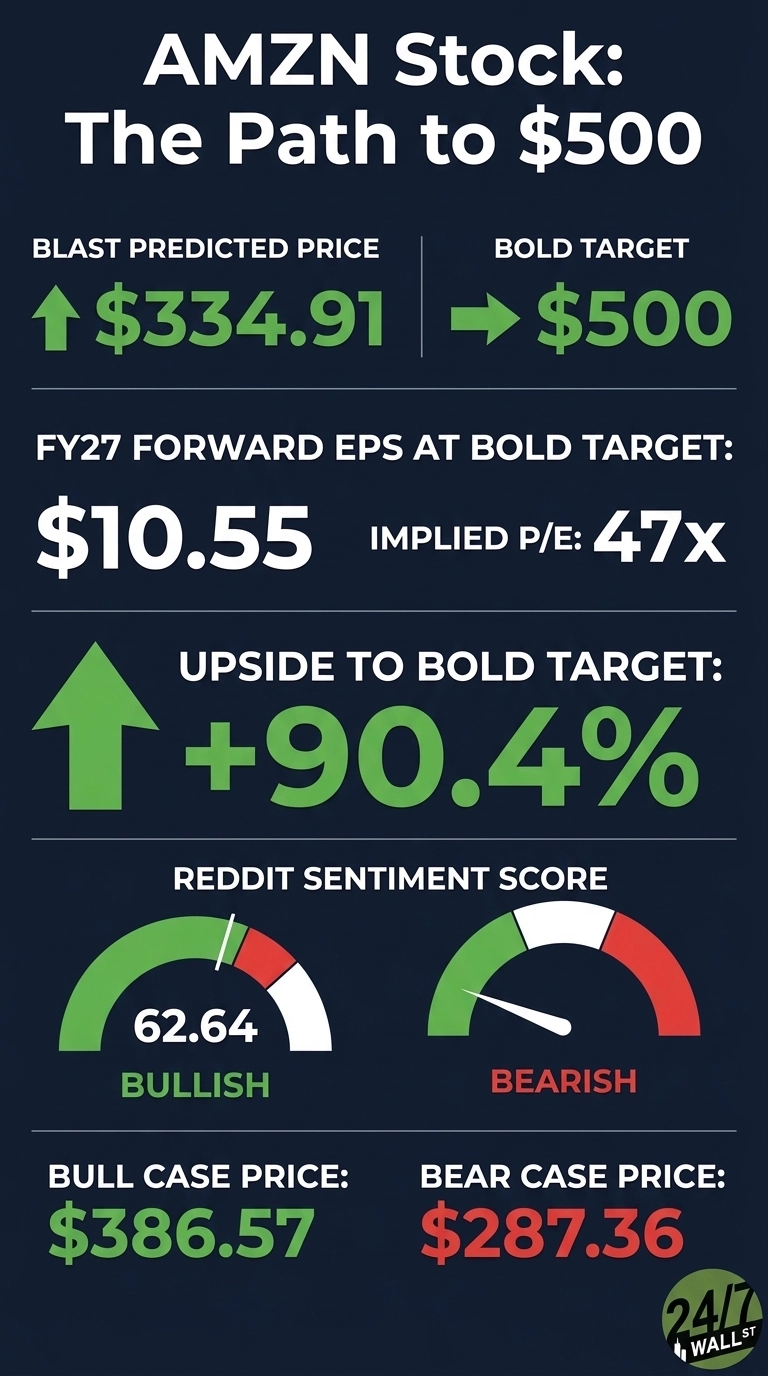
Wall Street’s consensus target is $331.46. The ratings include 16 Strong Buys, 43 Buys, 2 Holds, along with 0 Sells. The model puts shares at $334.91, a 27.54% gain. The bear case sits at $287.36, while the bull case reaches $386.57. Confidence in the model is 0.7, which is fairly high.

The consensus looks too short-sighted. Sentiment is 97% bullish, yet earnings growth adds only 0.03 to the factor after a mega-cap drag. One-year targets also leave out the AWS backlog. Our five-year base case puts shares at $489.98 by October 2030.
Here’s What It Takes for Amazon to Reach $500
Getting from today’s price of $262.59 to $500 would take a gain of 90.4%.
Consensus FY2027 EPS is $10.5519. At $500, that is a forward P/E of 47x. The $334.91 estimate works out to 32x on the same EPS, so the bold target needs roughly 16x of additional multiple expansion.
That gap closes if earnings compound through 2030. The highest FY2027 estimate is $15.0435, and at that level $500 is only 33x. The model’s 1.102 adjustment factor reflects “strong earnings acceleration.”
AWS backlog stands at $496 billion and is growing triple digits. The AI and chips businesses each run above $25 billion annualized. Anthropic and OpenAI have signed multi-year, multi-gigawatt Trainium commitments. Jassy added: “We will still not have enough capacity to meet all the demand we have in 2026.”
A key risk is that capex keeps climbing faster than AWS revenue and delays the free cash flow recovery past 2030.
Where Amazon Trades Today vs Its Earnings Power
Amazon trades at about 25x FY2027 EPS, versus a trailing P/E of 36x. For a company whose largest profit engine is growing 37% with a 39.4% operating margin, that multiple looks reasonable.
Shares sit inside a 52-week range of $196 to $287.20. The 10-year return is 542.43%. Today’s valuation gives earnings growth room to carry most of the load toward $500.
$500 Is a Stretch, but Here’s Why It’s Possible
A $500 price needs a 90.4% gain. My conclusion is that this is ambitious yet credible. Three things have to go right. AWS has to keep growing above 30%.
AI margins have to follow the core cloud path, which Jassy says is happening “a little ahead” of schedule. And revenue growth has to outpace capex so free cash flow turns positive again. A recession that hits enterprise cloud budgets would knock this off course.
Such returns shouldn’t be expected every year, but we’ve outlined the plan for how Amazon could reach $500 in 2030.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.