58 Analysts, Zero Sells, 28% Upside: Amazon’s Setup Right Now

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
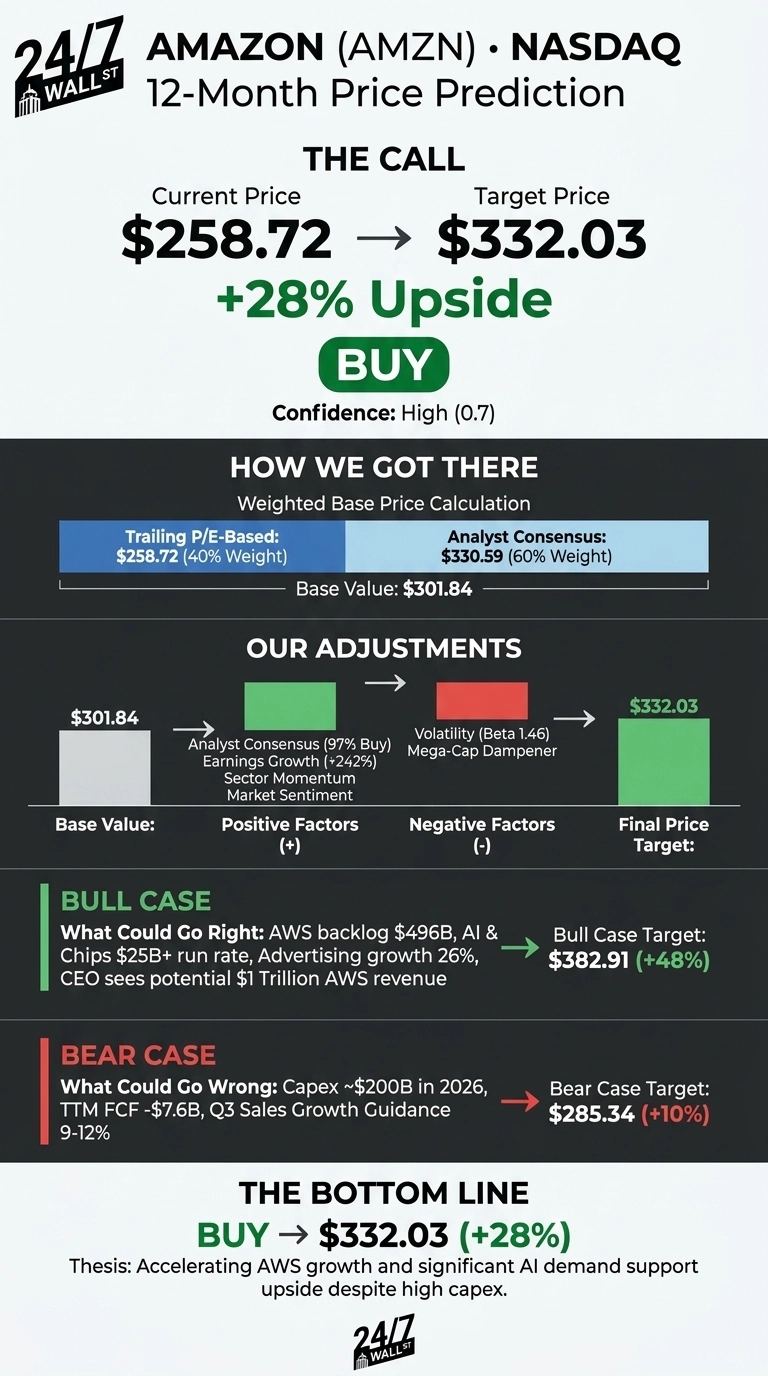
Our 24/7 Wall St. price target for Amazon (NASDAQ:AMZN | AMZN Price Prediction) is $332.03. From a current price of $258.72, that works out to 28.33% upside. Our model rates the stock a buy, and we hold that view with moderate-to-high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $258.72 |
| 24/7 Wall St. Price Target | $332.03 |
| Upside/Downside | 28.33% |
| Recommendation | BUY |
| Confidence Level | 70% |
Wall Street is close to unanimous here. Analysts have 15 Strong Buy and 43 Buy ratings on the stock, against 2 Holds and zero Sells. Needham’s Laura Martin made the case for owning Amazon on CNBC this week (CNBC).

AWS Acceleration Keeps Amazon Within 10% of Its High
The stock has risen 3.66% over the past week and is flat over the past month at -0.1%. It is up 11.89% year to date. Shares sit 9.9% below the 52-week high of $287.20 and 32% above the low of $196.
Second-quarter revenue came in at $200.61 billion, up 19.62% and ahead of the $196.43 billion estimate. GAAP EPS of $5.75 got a large lift from Anthropic investment gains. Comparable EPS of $1.88 still beat the $1.83 consensus. AWS grew 37% with a 39.4% operating margin.

Why Bulls See $382.91 on the Table
AWS backlog stands at $496 billion, and management says the “lion’s share of capacity in 27…is largely reserved.” The AI and chips businesses each run above $25 billion annualized. Advertising grew 26%.
CEO Andy Jassy thinks AWS could become “a trillion dollar annual revenue business for us in time.” If those trends compound, our bull case makes $382.91, a 48% return.

Capex and Earnings Quality Are the Risks to Watch
Amazon plans about $200 billion in 2026 capex, and trailing free cash flow has turned negative at -$7.6 billion. Third-quarter guidance calls for only 9% to 12% sales growth. Management has offered counterpoints.
Prime Day moved into Q2, and excluding that shift, Q3 growth would be “nearly 400 basis points higher.” Most AI capacity is also signed for “at least five-year terms.” Our bear case sits at $285.34.
Amazon Trades Between Its Cloud and Retail Rivals
Microsoft (NASDAQ:MSFT) competes with AWS through Azure, which grew 43%. It trades at 29x earnings with far higher margins.
Alphabet (NASDAQ:GOOGL) competes with Amazon in both cloud and ads. Google Cloud grew 82%, though Alphabet’s 16x multiple is flattered by equity gains.
Walmart (NASDAQ:WMT) is Amazon’s closest retail rival. Its eCommerce sales grew 23%, yet it trades at 39x earnings on thinner margins.
| Company | Trailing P/E | Operating Margin |
|---|---|---|
| Amazon | 36x | 11.16% |
| Microsoft | 29x | 46.78% |
| Alphabet | 16x | 32.06% |
| Walmart | 39x | 4.18% |
Amazon trades below Walmart and above its cloud rivals. With AWS margins expanding, the 24/7 Wall St. price target looks reasonable next to this group.
Amazon Price Prediction 2026-2030
Our 24/7 Wall St. price target of $332.03 comes with a buy rating and 70% confidence. What tips the scale is AWS growth speeding up even as the business gets bigger.
The case strengthens if AWS stays above 30% growth and the reserved capacity turns into revenue. It weakens if free cash flow continues falling after 2027. On balance, the reward outweighs the risk.
Looking further out, here is where our model projects Amazon could trade at each year-end, assuming current growth trends hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $274.63 |
| 2027 | $348.17 |
| 2028 | $416.92 |
| 2029 | $463.32 |
| 2030 | $503.44 |
These projections assume Amazon keeps executing on its current strategy. The returns on its AI infrastructure spending could push the result well above or below this path.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.