4 Data Center REITs With Growing Dividends and an AI Tailwind
AI data centers consume enough power to light entire cities, and the landlords collecting rent on those facilities are quietly growing their dividends. Four REITs sit at the center of this buildout, but their payout safety and growth outlooks differ…

A report from Colorado Legislative Council Staff notes that a single data center, when operating, can consume over a gigawatt of power, enough to power about 750,000 homes. Someone has to own the buildings, land, fiber, and power hookups behind that load, and four US-listed REITs collect rent on them. These names offer dividend growth with modest starting yields. Each pays a quarterly dividend covered by operating cash flow, and each is seeing demand from AI and cloud customers. Here is how safe each payout looks and what could slow it down.
American Tower: Tower Rent Today, CoreSite Growth Tomorrow
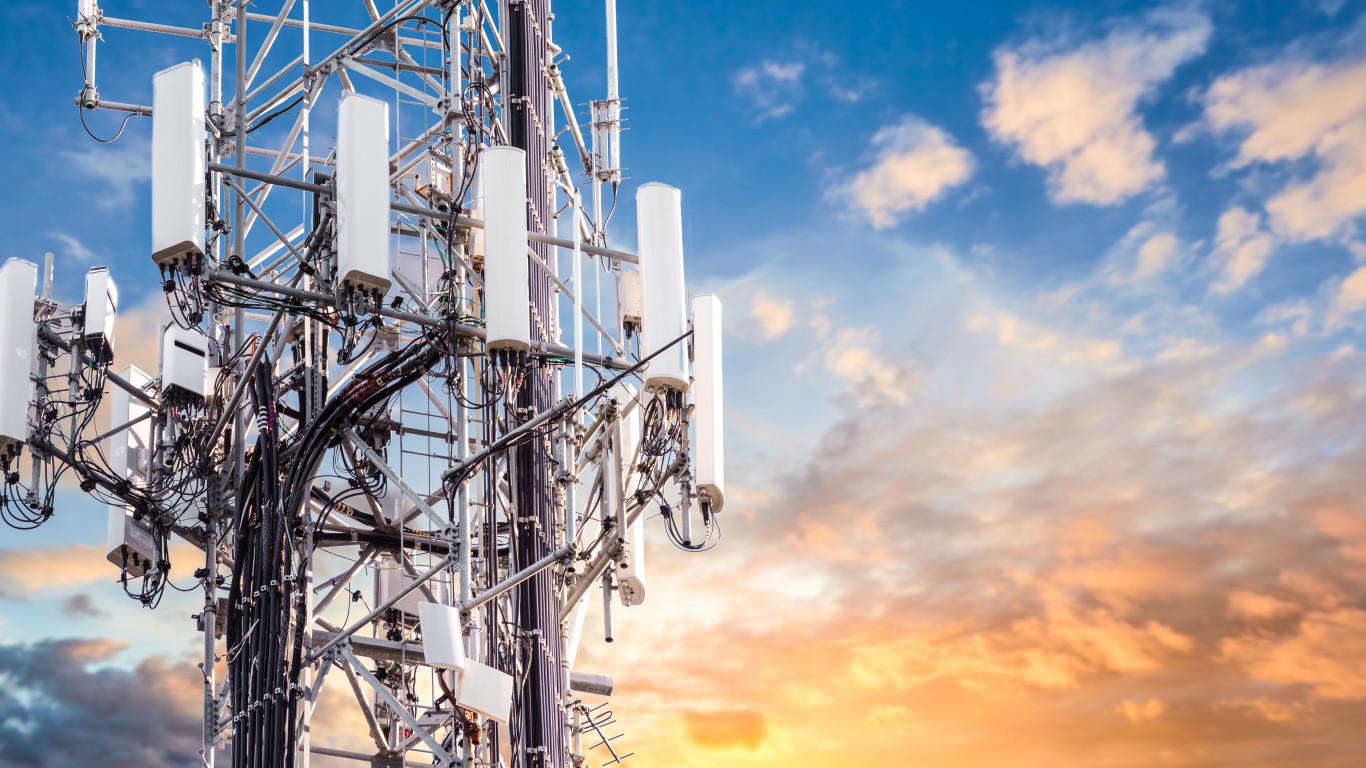
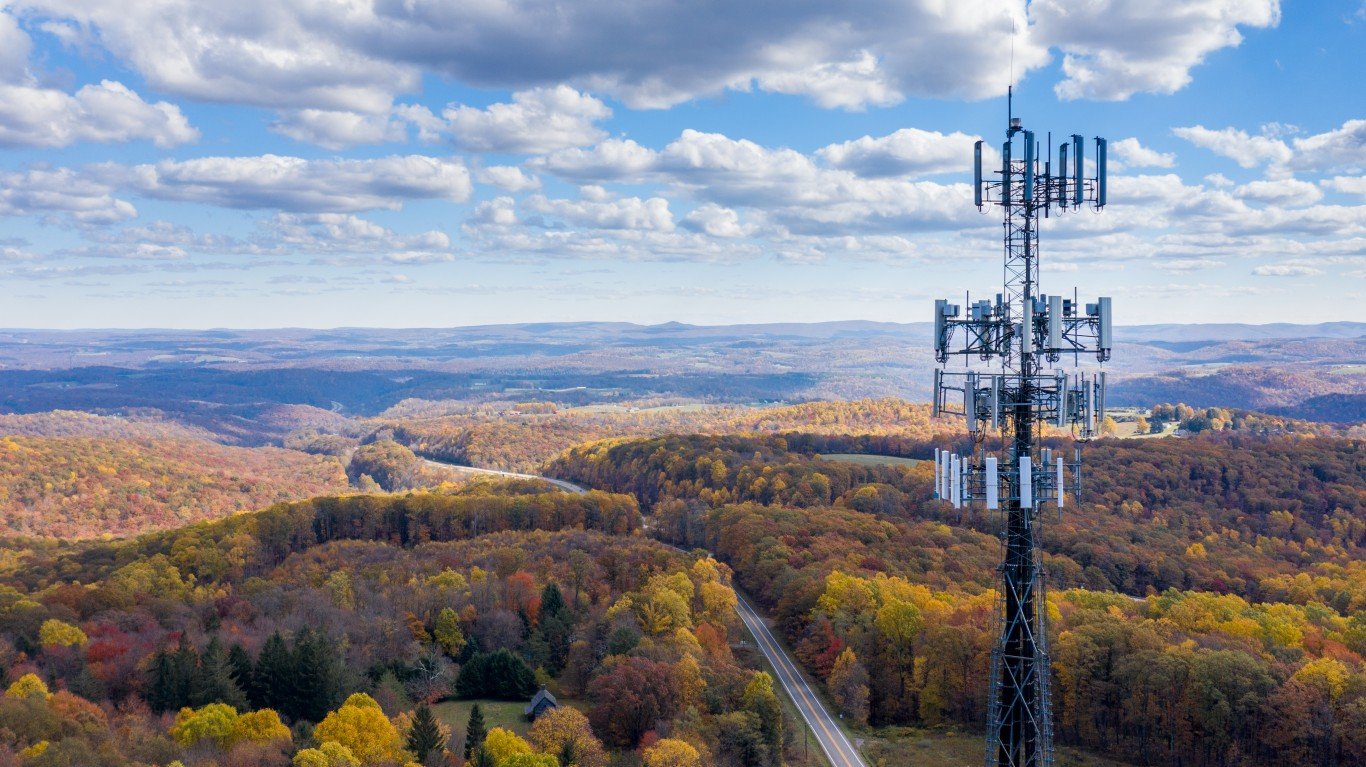
American Tower (NYSE:AMT) owns over 148,000 communications tower sites, which it leases to wireless carriers under long-term, non-cancellable contracts. Through its CoreSite subsidiary, it also runs heavily interconnected US data centers. Towers still make up most of the business, but data centers are growing faster: Data Centers revenue rose 13.4% year over year to $297M in Q2, while US & Canada property revenue fell 2.5%.
At $188.97, the stock yields 3.93%, the highest in this group. The quarterly payout is $1.79, or $7.16 annualized.
Dividend safety: Management raised its full-year AFFO per-share guidance to $11.00-$11.17, well above the annual dividend. In Q2, free cash flow came to $1.158B, up 18.5%, against a quarterly distribution of about $834.1M. Net leverage of 4.9x sits within its 3 to 5x target range. The chief financial officer named supporting a growing dividend as the first capital priority. The quarterly payout dropped from $1.70 to $1.62 at the start of 2024. It then rose to $1.70 in 2025 and $1.79 in 2026.
Bull case: Chief executive Steven Vondran said “CoreSite’s campuses have become critical destinations for AI traffic and data exchange,” with nine of the top ten AI companies already in its facilities. The company raised its 2026 data center growth outlook to about 15% and expects “mid-teens or better stabilized yields” on new CoreSite investments. Its next earnings report comes October 27 before the open.
Risk: DISH-related cancellations cut $63M from US & Canada property revenue in Q2, and that turnover is still weighing on the largest segment.
Iron Mountain: Records Boxes Help Fund an AI Data Center Buildout
Iron Mountain (NYSE:IRM) stores more than 735 million cubic feet of physical records across about 1,300 facilities, and the average box stays for about 14.5 years. That steady storage rent funds its newer businesses: 31 data centers in 21 markets with about 1.4 gigawatts of potential capacity, plus IT asset lifecycle management. Data centers, digital solutions and asset lifecycle management together now make up about 35% of revenue. Total revenue grew 18.5%, and data center revenue rose 38.8% to $262.9M.
The shares yield 2.94% at $109.94 per share. The quarterly dividend is $0.864, or $3.456 a year.
Dividend safety: The trailing four-quarter AFFO payout ratio was 60%, in line with management’s target in the low 60s. Full-year AFFO per share guidance was raised to $5.87 to $5.93. The company calls its latest 10% raise its fourth consecutive year of dividend increases, and the quarterly rate has risen from $0.65 to $0.715, then $0.785, then $0.864. Net lease-adjusted leverage ended Q2 at 4.8x.
Bull case: Data center leasing reached 110 MW year to date through July, and the backlog supports an additional $370 million of revenue beyond 2026. Chief executive William Meaney said recent London and Amsterdam deals were “a direct result of the large and expanding pipeline we have around AI inference.” Records retention held at 93.4%.
Risk: The company’s finances are extended. Shareholders’ equity is negative at $(955M), net debt is about $17.3B, and the newest bond carries a 6.25% coupon, so interest costs are rising.
Digital Realty: Pure-Play Scale With a Dividend Due for a Raise
Digital Realty (NYSE:DLR) owns only data centers: 309 of them across 55+ markets and 30+ countries, with about 3.0 gigawatts of IT capacity in place and about 6.3 gigawatts planned. It reports one Data Center Services segment covering colocation, interconnection, and hyperscale leases for more than 5,500 customers. Quarterly revenue grew 29.9% year over year, the fastest pace in this group.
The stock yields 2.77% at $172.38 on a $1.22 quarterly dividend, or $4.88 a year.
Dividend safety: Q2 Core FFO excluding promote income was $2.13 per share, up 14%, and well above the $1.22 quarterly payout. Debt-to-adjusted EBITDA is 4.7x, below the company’s long-term 5.5x ceiling, and liquidity stands near $6 billion. The dividend record dates back to 2004 and trended higher over that period, but the payout has stayed at $1.22 per quarter since 2022. With FFO growing and the dividend flat, coverage continues to expand.
Bull case: Total backlog hit a record $1.9 billion at 100% share. Chief executive Andy Power said strong hyperscale leasing “drove our backlog to a new all-time high, derisking future growth.” That backlog adds visibility to future cash flow.
Risk: Quarterly earnings fell 58.7% year over year. FFO is the better measure of REIT coverage, but a drop that large in reported earnings is worth tracking as development costs and depreciation build.
Equinix: Smallest Yield, Strongest Dividend Growth Commitment
Equinix (NASDAQ:EQIX) operates more than 270 data centers in more than 70 markets. It makes money from colocation (space, power, and cooling), interconnection (direct connections between customers), managed infrastructure, and its hyperscale xScale joint ventures. Quarterly revenue grew 16.7%, and Q2 brought a record 9,700 net interconnections.
At $955.03, the yield is 1.98%. The quarterly dividend is $5.16, or $20.64 annualized.
Dividend safety: Management set the payout ratio at 50%, the most conservative in this group. AFFO per share guidance is $42.69 to $43.29. Net leverage is 3.6x adjusted EBITDA, with about $7.7 billion in liquidity. The regular quarterly dividend has gone up every year in the record, from $1.69 in 2015 to $5.16 in 2026.
Bull case: Management expects dividend per share growth to about match AFFO per share growth, which it projects at 9-12% a year from 2027 through 2029. Chief executive Adaire Fox-Martin said, “Eight of the top ten model providers as well as eight of the top ten neo clouds are already running their key networking workloads on Equinix today.” Equinix reports October 28 after the close.
Risk: Spending is rising fast. Capex is guided at $5.0 to $6.0 billion for 2026 and $5.0 to $7.0 billion a year through 2029, with leverage projected to rise by about one turn over that period.
Which Income Investors This Group Fits
These four REITs fit dividend-growth investors with a long horizon who will take a smaller check today for one that grows. American Tower pays the most up front. Iron Mountain has the strongest recent run of increases. Equinix has the clearest link between dividend growth and AFFO growth.
Digital Realty has the widest gap between rising FFO and a flat payout. Investors focused on maximum current income can find higher starting yields elsewhere, while these four REITs collect rent as landlords in the AI expansion. (For readers who want to look past the landlords to the power, cooling, and networking suppliers feeding the same expansion, we rounded up seven of them in a free report here.)
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.