Make or Break for VRT on Oct. 28: Proving the ‘AI Factory’ Thesis Amid a Brutal Valuation Reset.
Vertiv's stock sits 39% below its recent peak despite five straight earnings beats, and the Oct. 28 report will force management to prove that delayed AI shipments finally landed or face a valuation reset that keeps accelerating.

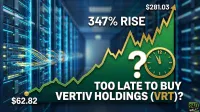
Vertiv (NYSE:VRT | VRT Price Prediction) reports third-quarter results on Oct. 28. Shares fell 21.89% over the past month to $194.31. The report needs to show that the delayed AI projects management promised in July are now shipping.
Record Profits, Falling Stock
On paper, Vertiv’s second quarter was strong. Adjusted EPS of $1.52 rose 60% and came in $0.12 above guidance. Revenue climbed 24.1% to $3.27 billion, and adjusted operating margin expanded 410 basis points to 22.6%.
The stock still dropped 17.26% on earnings day. Organic growth slowed to 18%, and management pointed to supply chain congestion and the timing of phased projects. CEO Giordano Albertazzi called it a learning curve on highly complex projects, then raised full-year adjusted EPS guidance to $6.65 to $6.75. He added, “We are not assuming all stars align.”

Since then, the selloff has deepened. Shares were at $319.09 at the Q1 report and now sit 39% lower, which cuts the year-to-date gain to 20.03%. The stock now trades at about 29x 2026 consensus EPS.

Wall Street Expects 47% EPS Growth
Consensus stands just above management’s guidance midpoints of $1.80 EPS and $3.75 billion in revenue.
| Metric | Consensus | Prior Year Actual | YoY Growth |
|---|---|---|---|
| Q3 2026 Normalized EPS | $1.8237 | $1.24 | 47% |
| Q3 2026 Revenue | $3.76B | $2.68B | 41% |
| FY 2026 EPS | $6.7341 | $4.19 | 61% |
| FY 2026 Revenue | $14.00B | $10.23B | 37% |
Delayed Projects and Margins Will Set the Tone
Guidance calls for organic growth of about 35%, with the Americas and APAC in the high 30s and EMEA in the mid to high teens. That rate is nearly double Q2’s, so the key question is whether the slipped revenue actually shipped. It’s also worth asking whether new capacity in Malaysia and five Americas plant expansions came online on schedule.
Margins come next. The company pointed to a 24.5% adjusted operating margin, up 220 basis points, after the Americas reached 27.6% last quarter. The guidance assumes positive price-cost even after tariffs, so that’s the assumption you should test.
The AI factory story also needs fresh proof. On Oct. 21, Vertiv said its NVIDIA (NASDAQ:NVDA) DSX approach targets up to 30% more cumulative AI token output in the first 12 months, and Polar is using it at a site in Norway. I want updates on 800V DC customer validation, which is scheduled for 2026. Vertiv is exactly the kind of non-chipmaker AI supplier we profiled in a free report on seven companies powering the data-center buildout.
Orders matter as much as earnings. In Q1, Vertiv beat EPS estimates by 15.68% and still fell 2.34% that day. Worries about hyperscaler capex and power grid bottlenecks make any soft backlog comment risky. Options traders are positioned defensively, with a full-chain put/call ratio of 2.54.
A Cheaper Stock Puts Execution on Trial
Vertiv has raised guidance every quarter this year and beaten EPS estimates five straight times, yet the stock lost its premium anyway. That says me the market wants proof of delivery more than talk about demand. If second-half shipments land and margins expand as forecast, the AI factory thesis gets its credibility back at a far lower multiple. Management’s tone on 2027 orders will matter as much as the quarter itself. If timing shifts again, the valuation reset could keep going.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.