Vertiv Looks Like Its Comeback is Finally Materializing
Vertiv shares collapsed 34% from their spring peak before a single earnings report sent them surging 25% in a week. Now analysts are split on whether the order book signals a genuine recovery or a temporary reprieve ahead of a…

Vertiv (NYSE:VRT | VRT Price Prediction) trades at $245.95. A stronger-than-expected third quarter just reset expectations for AI infrastructure stocks after a painful slide from spring highs.
Vertiv sells power, cooling and thermal management systems that keep data centers running in more than 130 countries, exactly the kind of picks-and-shovels AI exposure we featured alongside six others in a free report on the suppliers behind the AI buildout. It joined the S&P 500 in March 2026, yet shares fell from $319.09 at its first-quarter report to $211.09 on third-quarter release day. They have since climbed 25.75% in a week.
Triple-Digit Order Growth Powers the Bull Case
Adjusted EPS hit $2.21 against a $1.82 consensus, and revenue of $4.31B rose 61.2%, exceeding the $3.76B estimate. Organic orders grew over 100%, and adjusted operating margin expanded 290 bps to 25.2%. Management raised full-year EPS guidance to $7.10-$7.20.
On the $9.1945 consensus 2027 EPS estimate, shares trade near 27x, with a PEG ratio of 0.688. Catalysts include full native 800-volt DC revenue beginning in 2027 and the newly closed UtilityInnovation Group deal.
Quality Scares and High Volatility Arm the Bears
Trailing P/E is 47, price-to-sales at 8.15, and beta at 2.048. On the call, an analyst raised reports of burned-out compressors and overheating UPS systems. Management granted new products can show a higher initial quality curve, and second-quarter supply-chain problems pushed an estimated $100 million to $150 million of revenue into the third quarter.
Management also flags tariffs, unpredictable customer ordering and possible failure to realize backlog. Power availability, permitting and skilled labor shortages could slow customer projects.
Execution Proof Still Matters Before 2027
Shares are already up 51.92% this year and remain below the $269.86 200-day moving average. Management offered no formal 2027 revenue or margin guidance, so the next milestones are fourth-quarter EPS within the $2.22-$2.28 range and cleaner quality data.
Analysts See 35% Upside as Vertiv Outpaces the S&P 500
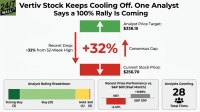
The $333 consensus target implies 35.4% upside across 29 analysts. Targets are one input and carry no guarantee. The ratings break down as follows:
- Strong Buy: 3
- Buy: 22
- Hold: 4
- Sell: 0
Vertiv’s year-to-date gain of 51.92% compares with 12.84% for the S&P 500. Over one year, Vertiv rose 23.56% against the index’s 11.94%. Shares still sit 35% below the $379.76 52-week high, and the 2026 consensus EPS estimate climbed to 6.7341 from 6.4847 over 90 days.
Vertiv’s Comeback Takes Hold as Earnings Estimates Rise
At $245.95, Vertiv’s outlook rests on its order book.
The selloff priced in a demand slowdown, and the order book points the other way. Orders above 100% growth commonly convert within 12 to 18 months, which gives visibility into 2027. Chairman Dave Cote put it bluntly: “The rumors of our demise have been greatly exaggerated.”
Getting there depends on the fourth-quarter report, a 2027 outlook calling for “continued significant above-market organic sales growth,” and 800-volt DC validation. A net cash balance sheet and $2.6B-$2.8B of expected free cash flow cushion execution stumbles.
The bull case falls apart if orders slow down rapidly, margins slip below the 24% full-year target, or quality complaints turn into lost customers. Given a beta above 2, volatility will stay high either way.
Vertiv trades at a discount to its highs while its earnings estimates keep rising, and that gap frames the debate for investors.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.