88% Profit Surge Expected on Oct. 28: Why Peter Thiel-Backed Vista Energy is Wall Street’s Favorite Shale Play
Vista Energy reports on October 28 with Brent oil briefly topping $130 and a full quarter of newly acquired Vaca Muerta assets on the books. Whether that windfall survived peso costs and geopolitical chaos on its way to free cash…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
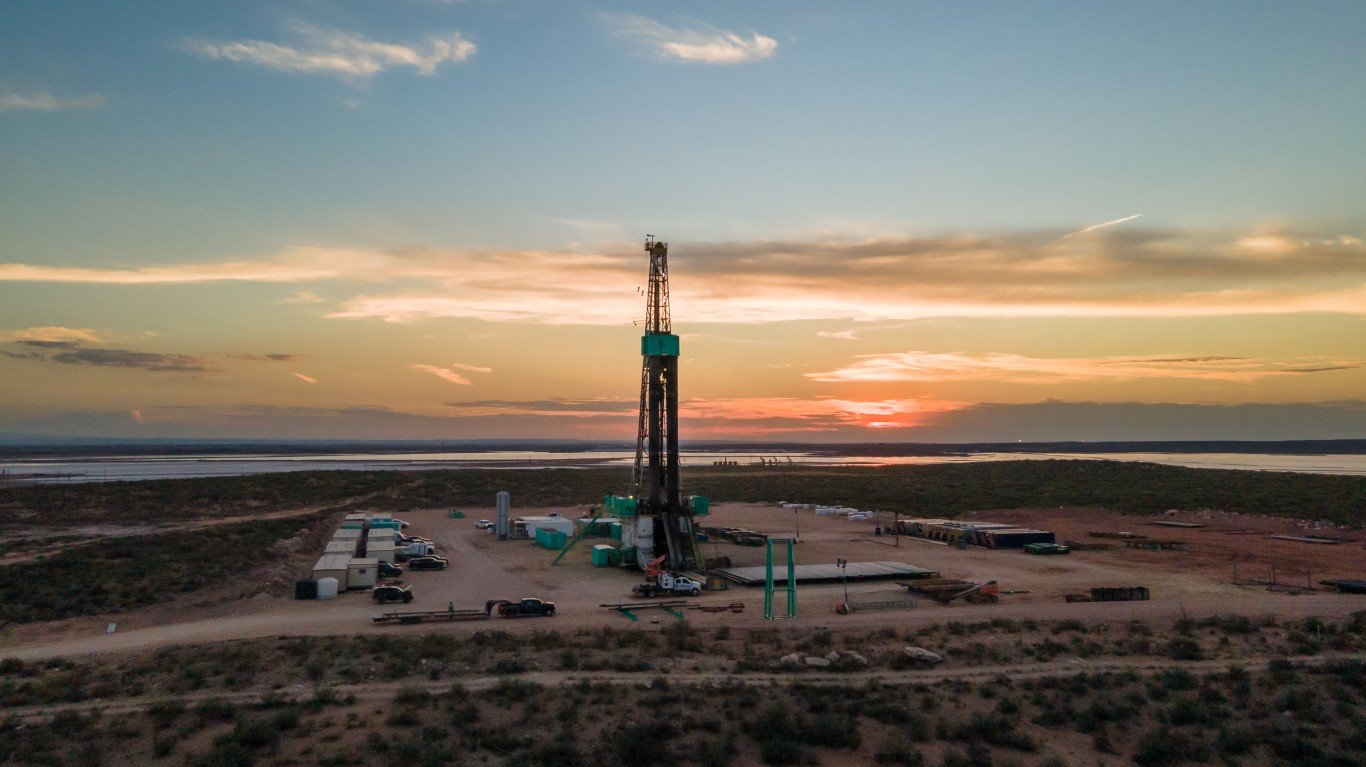
Vista Energy (NYSE:VIST) reports third-quarter results on October 28. This is the first full quarter with the Equinor assets consolidated, and Brent topped $130 in September. The report will show how much of that gain reached the bottom line.
Bigger Barrels Meet a Brent Spike
Last quarter set a high bar. Revenue reached $1.15 billion, up 89% year over year, and adjusted EBITDA rose 99% to $805 million. Vista sold 100% of its oil at export parity for a realized $89.40 per barrel.
Free cash flow, net of the Equinor payment, came in at $491 million and brought net leverage down to 1.41x. On the July call, Chairman and CEO Miguel Galuccio called it a “very strong quarter.”
Since then, Peter Thiel’s hedge fund, Thiel Macro, has disclosed a stake. Shares closed at $74.84 on October 23, up 53.8% year to date and 88.32% over the past year. Fourteen analysts rate the stock a Buy, with an average target of $99.60.
Consensus Calls for Another Big Step Up
The EPS consensus has fell to $43.469 from $48.5585 a week ago. Revenue expectations still point to strong growth.
| Metric | Consensus | Comparison Base | Implied Growth |
|---|---|---|---|
| Q3 2026 EPS | $43.469 | $20.6837 (Q3 2025 consensus) | 110.2% |
| Q3 2026 Revenue | $1.17 billion | $706 million (Q3 2025 actual) | 65.8% |
| FY2026 EPS / Revenue | $190.2346 / $4.34 billion | N/A | N/A |
| FY2027 EPS / Revenue | $194.3328 / $4.42 billion | FY2026 consensus | 2.2% / 1.8% |
Vista reported EPS of $3 in both Q3 2025 and Q2 2026, far below consensus each time. For that reason, I lean on revenue and EBITDA for a cleaner read.
Peso Costs and Realized Prices Will Set the Tone
The first number I’ll check is the realized oil price. Brent ran from $68.53 on July 2 to $130.80 on September 15. Since Vista sells its oil at export parity, its realized price will show how much of that rally made it into revenue.
Costs are next. Lifting cost rose from the prior quarter to $4.50 per boe as peso-denominated costs went up while exchange rates stayed flat. Selling expenses rose 8% to $4.10 per boe as higher oil prices lifted turnover tax. Rising cost of sales already dragged on Q2 earnings, so cost control matters most this time.
Integration counts too. Bandurria Sur and Bajo del Toro added 14.2 thousand boe/d in Q2 from May 1. Their run rate of about 21,000 boe/d shows up in full for the first time in Q3. July production through mid-month reached 162,000 barrels per day.
You should also look at leverage. Management is aiming about 1.0x by year-end after spending $467 million on capex in Q2. I also want an update on the VMOS export pipeline. Shipment of its mooring buoy was affected by the Strait of Hormuz closure.
A Chance to Prove the Windfall Turns Into Cash
Vista is now a large-scale Vaca Muerta producer, and the Thiel stake has drawn more attention to it. Policy and currency risk in Argentina is still there, and oil prices can turn quickly. Brent fell to $115.22 by October 20. If high realized prices turn into free cash flow while peso costs stay controlled, the deleveraging story gets much more credible. That would also clear the way for the buybacks management has kept under consideration.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.