Prediction: The Next Chapter for Apple Could Be Its Most Important Yet
A leadership handoff, a supply-constrained iPhone, and an AI rollout colliding at once: Apple is navigating more moving parts than it has in years, and where the stock lands depends on which force wins out.

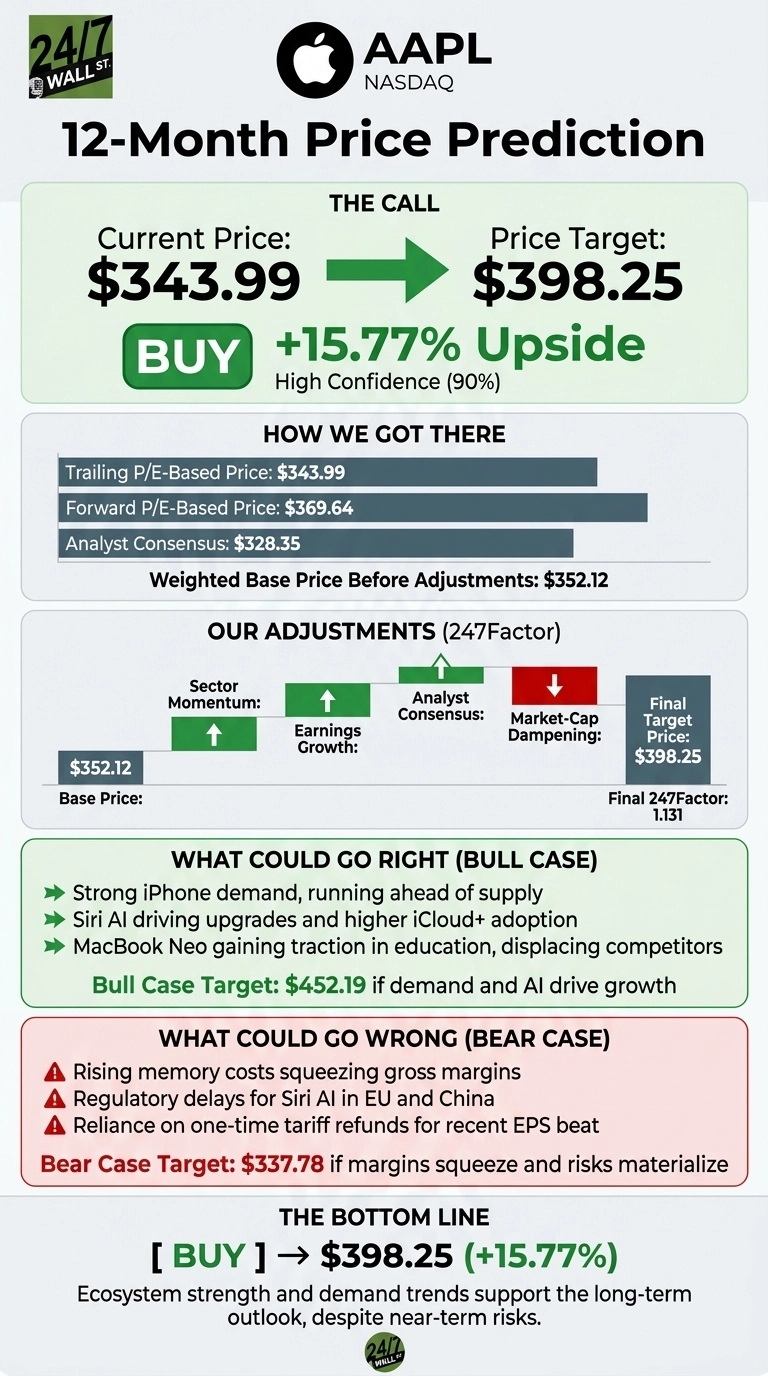
The 24/7 Wall St. price target for Apple (NASDAQ:AAPL | AAPL Price Prediction) is $398.25 over the next 12 months. That means 15.77% upside from $343.99. We rate the stock a buy, and our model holds high confidence in that call.
| Metric | Value |
|---|---|
| Current Price | $343.99 |
| Price Target from 24/7 Wall St. | $398.25 |
| Upside/Downside | 15.77% |
| Recommendation | BUY |
| Confidence Level | 90% |

Apple is heading into its most important stretch in years. A leadership handoff is underway, Siri AI is rolling out, and iPhone demand is running ahead of supply. Our model sees those forces adding up to meaningful upside, even after a strong run.

A Record June Quarter Fueled Apple’s 28% Rally
Shares have gained 1.57% over the past week, 2.24% over the past month, 8.35% over the past quarter and 28.12% year to date. That puts the stock near the top of its 52-week range of $242.76 to $348.15.
In fiscal Q3, revenue came in at $109.42 billion, up 16.4% and ahead of the $108.96 billion consensus. EPS of $2.02 exceeded expectations of $1.89.
iPhone revenue rose 22% and Mac grew 29%. Tim Cook said that July 30 call was his final one as CEO and that John Ternus was expected to lead future calls. This week, CNBC reported that the iPhone Duo is in short supply.

Why Bulls See $452 Within Reach
The bull case is $452.19, a 31.46% return. Apple has over two and a half billion active devices and more than one and a half billion paid subscriptions. Management expects Siri AI to push some users into higher iCloud+ levels.
The MacBook Neo is also pulling schools away from Windows and Chromebook devices. Guidance for the September quarter calls for 9%-11% revenue growth, with iPhone growth in the mid-teens.
On the Street, Apple has 6 Strong Buy and 19 Buy ratings, against 3 Sells and 3 Strong Sells.

Memory Costs Could Squeeze Apple’s Margins
The bear case is at $337.78, or -1.8%. Cook called the memory market “a 100-year flood” and warned that costs keep rising. Gross margin guidance of 47%-48% includes about one percentage point from one-time tariff refunds.
Those refunds also added $0.11 to Q3 EPS. Siri AI is still delayed in the EU and China. Among tracked institutions, 8 cut their positions in the June quarter. Berkshire Hathaway (NYSE:BRK-B) kept its 227,917,808 shares unchanged.
Bulls would point out that operating expenses rose 23% mainly because of R&D. That spending climbed to $11.73 billion from $8.9 billion, a planned investment in AI.
How Apple Compares to Microsoft and Alphabet
Because it is Apple’s closest rival for the title of most valuable company and competes for the same AI dollars, Microsoft (NASDAQ:MSFT) belongs here. The stock trades at a trailing P/E of 29 with a 40.3% net margin.
In mobile platforms and AI assistants, Alphabet (NASDAQ:GOOGL) competes with Apple. Its P/E of 14 is held down by a $99.03 billion equity gain. Alphabet also posted negative free cash flow and suspended buybacks.
| Company | Trailing P/E | Latest Revenue Growth |
|---|---|---|
| Apple | 45 | 16.4% |
| Microsoft | 29 | 17.75% |
| Alphabet | 14 | 24.23% |
Apple carries a clear premium over both peers. Our target looks reasonable, but it relies on Apple’s capital returns and ecosystem lock-in rather than on further multiple expansion.
Apple Price Prediction 2026-2030
The 24/7 Wall St. price target of $398.25 supports a buy with high confidence. What tips the scale for me is iPhone demand exceeding supply.
The bull case improves if Siri AI drives upgrades and memory costs level off. The outlook weakens if gross margin falls below guidance once tariff refunds wear off. On balance, Apple’s ecosystem and demand trends support our long-term outlook.
This is where our model projects Apple could trade, assuming current trends hold. The 2026 figure reflects our model’s January 2027 update.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $351.30 |
| 2027 | $397.25 |
| 2028 | $443.95 |
| 2029 | $491.53 |
| 2030 | $523.62 |
These projections assume Apple keeps performing under new leadership. The biggest swing factors are Siri AI adoption and memory pricing.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.