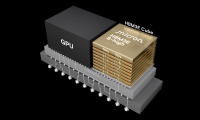
The Memory Bottleneck Divide: SK Hynix Sells out to Tier-1s, Micron Absorbs the Spills
SK hynix has already sold out its AI memory capacity while Micron scrambles to lock buyers into long-term contracts, and the distance between those two positions could decide which stock survives the next downturn intact.

SK hynix (NASDAQ:SKHY) and Micron Technology (NASDAQ:MU | MU Price Prediction) both just reported AI-driven memory quarters, but they hold different places in the HBM line. SK hynix leads the field, providing Tier-1 accelerator builders. Micron takes the excess and locks buyers into multiyear contracts while packaging capacity remains tight. SK hynix reports again soon, so the gap between those two roles matters now.
Pricing Power Lifts Hynix While Contracts Anchor Micron
SK hynix posted Q2 revenue of KRW 79.32 trillion, up 256.8% YoY, but missed consensus of about KRW 84.12 trillion. The miss matters less once you see operating profit of KRW 60.54 trillion, up 557.2%. Pricing power in DRAM and NAND, plus a shift toward premium AI memory, drove that result. A 48.6% operating margin tells you customers have few places to go.
Micron’s fiscal Q4 revenue reached $54.23 billion, beating the $50.97B consensus. Non-GAAP EPS of $33.42 exceeded the $31.35 estimate. Core Data Center led at $18.00B, a sign that AI servers now set Micron’s pace. Mobile and Client brought in $13.11B even as bit shipments fell sequentially, so higher prices did the work there. CEO Sanjay Mehrotra said the company’s “Strategic Customer Agreements provide added confidence in the durability of Micron’s financial performance.”
| Business Driver | SK hynix | Micron |
|---|---|---|
| Main Engine | HBM for Tier-1 AI accelerators | Data center DRAM, HBM, SSDs |
| Demand Lock | HBM capacity largely sold out | More than 75% of FY2027 shipments committed |
| Soft Spot | Revenue missed consensus | Mobile and client bits declined |
Hynix Rations Supply as Micron Widens the Net
SK hynix operates like a high-margin utility for Tier-1 AI clusters . It previously told the Financial Times that its “DRAM, NAND, as well as HBM capacity for next year has been sold out.”
Micron spreads its risk across 26 strategic customer agreements, including 10 new signed this quarter. Those deals reach every business unit and include customers of all sizes. The company is also co-designing an HBM4E product with NVIDIA (NASDAQ:NVDA) and has “increased that pricing significantly for calendar year ’27.” Management says it has “no line of sight to when supply and demand balance.” Memory is cyclical, so I treat that confidence with some caution.
HBM4E and Hynix’s Next Report Will Decide the Gap
Micron guided fiscal Q1 revenue to $61.5B ± $1.5B, which points to further gains. It is also pushing back on Chinese competition and says it is “at least two nodes ahead.” When SK hynix reports Q3, I will check whether revenue catches up with consensus . Both stocks have pulled back. Over the past month, SKHY fell 25.55% and MU fell 16.49%, a sign that cycle risk may already weigh on both stocks.
Which Memory Maker Carries More Downside Exposure
Both stocks are cyclical. I think Micron has more downside exposure. Its HBM share is smaller and its commodity memory business is wider, so a delay in data center capex or a round of inventory digestion would likely hit Micron first . SK hynix’s sold-out HBM book gives me more comfort, though ADS holders still face currency risk.
My view would change if Micron’s NVIDIA co-design turns into real HBM4E share, since the excess supplier could become a primary one. Until then, SK hynix holds the stronger HBM position.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.