Apple’s Hardware Strength Fuels Analyst Optimism, Multiple Analysts Raise Price Targets
Three major Wall Street firms just revised their Apple targets after a record quarter, yet shares tumbled premarket as investors zeroed in on one number buried in the guidance that could define the stock's next move.

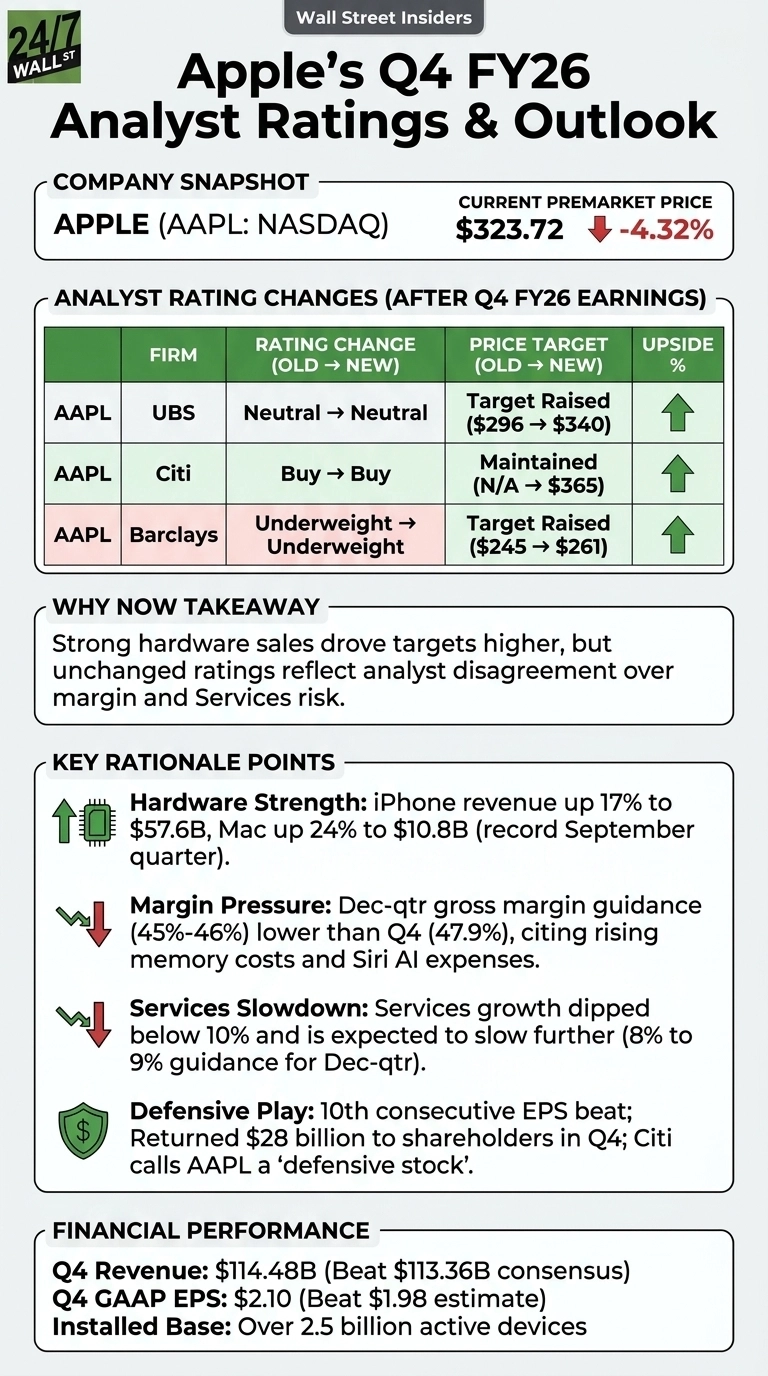
Wall Street split three ways on Apple (NASDAQ:AAPL | AAPL Price Prediction) after its fiscal fourth-quarter report. UBS lifted its price target to $340 from $296 and kept a Neutral rating. Barclays raised its target to $261 from $245 and kept an Underweight rating. Citi maintained a Buy rating with a $365 target.
Strong hardware sales drove targets higher, but the unchanged ratings show analysts still disagree about margin and Services risk in Apple stock.

| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| AAPL | Apple | UBS | Target Raised | Neutral | Neutral | $296 | $340 |
| AAPL | Apple | Citi | Maintained | Buy | Buy | N/A | $365 |
| AAPL | Apple | Barclays | Target Raised | Underweight | Underweight | $245 | $261 |
Inside the Analysts’ Case
UBS analyst David Vogt called the quarter generally in line. He said iPhone and Mac strength made up for weaker Wearables and supply-constrained iPad results. He also warned that three issues could pressure earnings expectations: below-consensus December-quarter gross margin guidance, slower Services growth as AI threatens to eat into search, and rising Siri costs.
Citi said the quarter beat estimates, but the fiscal Q1 outlook was mixed. Higher product revenue was partly offset by slower Services growth and lower gross margins. The firm remains positive on Apple’s long-term path and calls it a “defensive stock.”
Barclays analyst Tim Long said results and guidance were close to consensus. He noted that Macs keep outperforming but make up only high-single-digits of revenue, while Services growth dipped below 10% and is expected to slow further.
Company Snapshot: A Record September Quarter
Revenue came in at $114.48B versus $113.36B consensus, up 11.7% YoY. GAAP EPS of $2.10 beat the $1.98 estimate. iPhone revenue reached $57.6 billion, up 17%, and Mac revenue rose 24% to $10.8 billion.
iPad fell 10% and Wearables fell 8%. For the full fiscal year, revenue amounted $478.83B and EPS came to $8.98.

Why the Move Matters Now: Margins Take Center Stage
Apple expected December-quarter revenue growth of 7% to 10%, Services growth of 8% to 9% and gross margin of 45% to 46%. That compares with 47.9% last quarter, a figure that included a tariff-refund benefit of about one point. Chief executive John Ternus called memory pricing “unprecedented.”
Investors focused on that guidance. Shares traded at $323.72 premarket, down 4.32%, with headlines calling the results as a disappointment.
The stock sits below the $332.39 consensus target and trades at about 36x forward earnings. Wall Street’s ratings remain mixed: 6 Strong Buy, 18 Buy, 13 Hold, 3 Sell and 3 Strong Sell.

What It Means for Your Portfolio
Long-term investors get a clear trade-off here. Demand for new devices is running ahead of supply, Apple has beaten EPS estimates for 10 consecutive quarters, and the company returned $28 billion to shareholders last quarter. Against that, rising memory costs, Siri AI expenses and slowing Services growth could pressure earnings at a premium valuation.
Retirement-focused holders should watch December-quarter gross margins and how quickly iPhone Duo supply catches up with demand. Both will shape how far the revised targets can go.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.