Apple Is at a Record Going Into Earnings. Wall Street’s Target Is Below It
Wall Street's consensus target sits below where Apple already trades, yet our model sees a very different number ahead of the November earnings report. Here is why the Street may have badly misjudged where this stock is going.


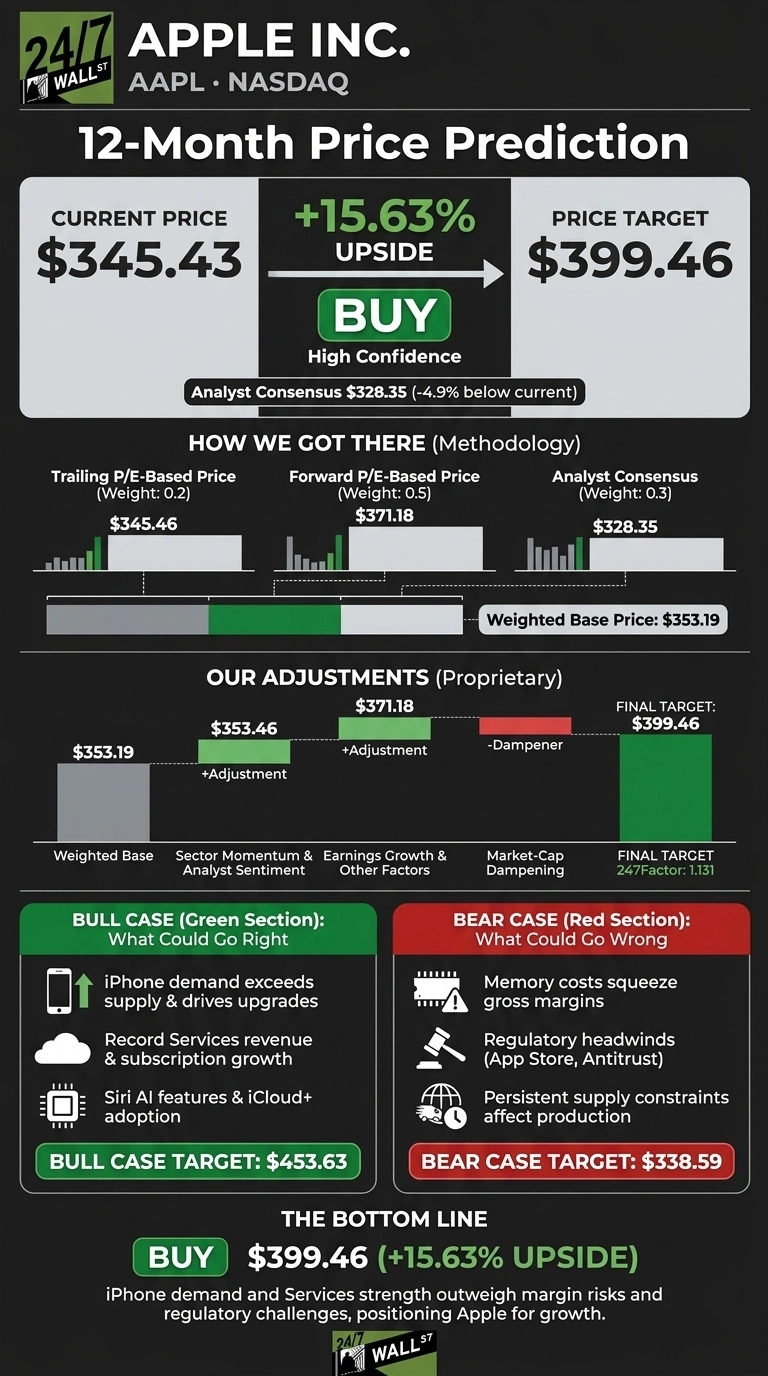
The 24/7 Wall St. price target for Apple (NASDAQ:AAPL | AAPL Price Prediction) is $399.46. That represents 15.63% upside from $345.43. Wall Street’s consensus target of $328.35 sits about 4.9% below the current price, and that gap is the story of this article.
| Metric | Value |
|---|---|
| Current Price | $345.43 |
| Price Target from 24/7 Wall St. | $399.46 |
| Upside/Downside | 15.63% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our model rates Apple a buy with high confidence. The stock trades 1.8% below its 52-week high of $351.73.
The September-quarter report is expected November 2 after the close, a date Apple has not yet confirmed. In my view, the analyst consensus has fallen behind the earnings path.

Up 27% in 2026 and a Post-Earnings Drop That Didn’t Last
Shares rose 0.57% over the past week and 2.5% over the past month. They are up 27.41% year to date and sit 42.3% above the 52-week low. Fiscal Q3 revenue grew 16.4% to $109.42 billion, and EPS of $2.02 exceeded the $1.89 consensus. The stock still fell 7.35% on earnings day, then gained 5.25% over the next 30 days.
The current story is about leadership and positioning. CNBC calls Apple an “anti-AI trade,” and the rally has tightened the race for world’s most valuable company. The iPhone Duo launch is also underway. That July call was Tim Cook’s last as CEO, and John Ternus was expected to lead future calls.
Why Bulls See $453 Within Reach
Apple guided September-quarter iPhone growth to the mid-teens. Management also described supply constraints as a demand-forecast problem. Services hit a June-quarter record of $30.7 billion, and paid subscriptions passed one and a half billion.
Add Siri AI and a $100B buyback authorization, and our bull case reaches $453.63. Analysts lean positive, with 6 bullish ratings and 19 on the buy side.

Memory Costs Could Squeeze Margins
Gross margin guidance of 47%-48% compares with 50.1% last quarter, and it includes about one percentage point of tariff refunds. Cook described memory pricing as a “100-year flood.”
Foreign exchange and App Store rulings weigh on Services, and 3 Sell and 3 Strong Sell ratings remain. Our bear case is $338.59. One offset: excluding the $0.11 tariff benefit, Q3 EPS of $1.91 still beat consensus.
How Apple Compares to Microsoft and Alphabet
As a mega-cap platform peer that also competes in AI services, Microsoft (NASDAQ:MSFT) belongs here. Its revenue grew 17.75% at a P/E of 29, while Apple trades at 45. However, Microsoft’s free cash flow is weighed down by capex that rose 109.63%, and that drives its P/FCF above Apple’s.
Alphabet (NASDAQ:GOOGL) competes with Apple in mobile platforms and subscriptions. Its P/E of 14 is inflated by a $99 billion equity gain.
| Company | Trailing P/E | P/FCF |
|---|---|---|
| Apple | 45 | 51 |
| Microsoft | 29 | 58 |
| Alphabet | 14 | 53 |
On free cash flow, Apple is the cheapest of the three. That makes our target look reasonable.
Our Model Says Buy Ahead of November 2
Our 24/7 Wall St. price target of $399.46 has a buy rating and 90% confidence. What tips the scale for me is iPhone demand running ahead of supply.
My case gets stronger if Siri AI drives upgrades and iCloud+ revenue. I’d grow cautious if memory costs push margins below guidance. My view: the Street is too low.

Here is where our model projects Apple at each year’s end, assuming current growth holds.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $348.46 |
| 2027 | $409.02 |
| 2028 | $455.41 |
| 2029 | $495.65 |
| 2030 | $538.52 |
Apple would need to keep executing under its new leadership for these projections to hold. AI monetization or a prolonged memory-cost spike could move the result sharply in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.