Apple’s Pain Could Be Micron’s Gain as Memory Prices Surge
Memory prices are climbing fast, and that single cost is splitting two tech giants onto opposite sides of a trade. One company's suffering feeds the other's record margins, and the gap between them keeps widening.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Memory has become one of the most contested costs in technology. Micron Technology (NASDAQ:MU | MU Price Prediction) is posting record margins as DRAM and NAND prices rise. Apple (NASDAQ:AAPL) is paying more for every iPhone and Mac it makes.
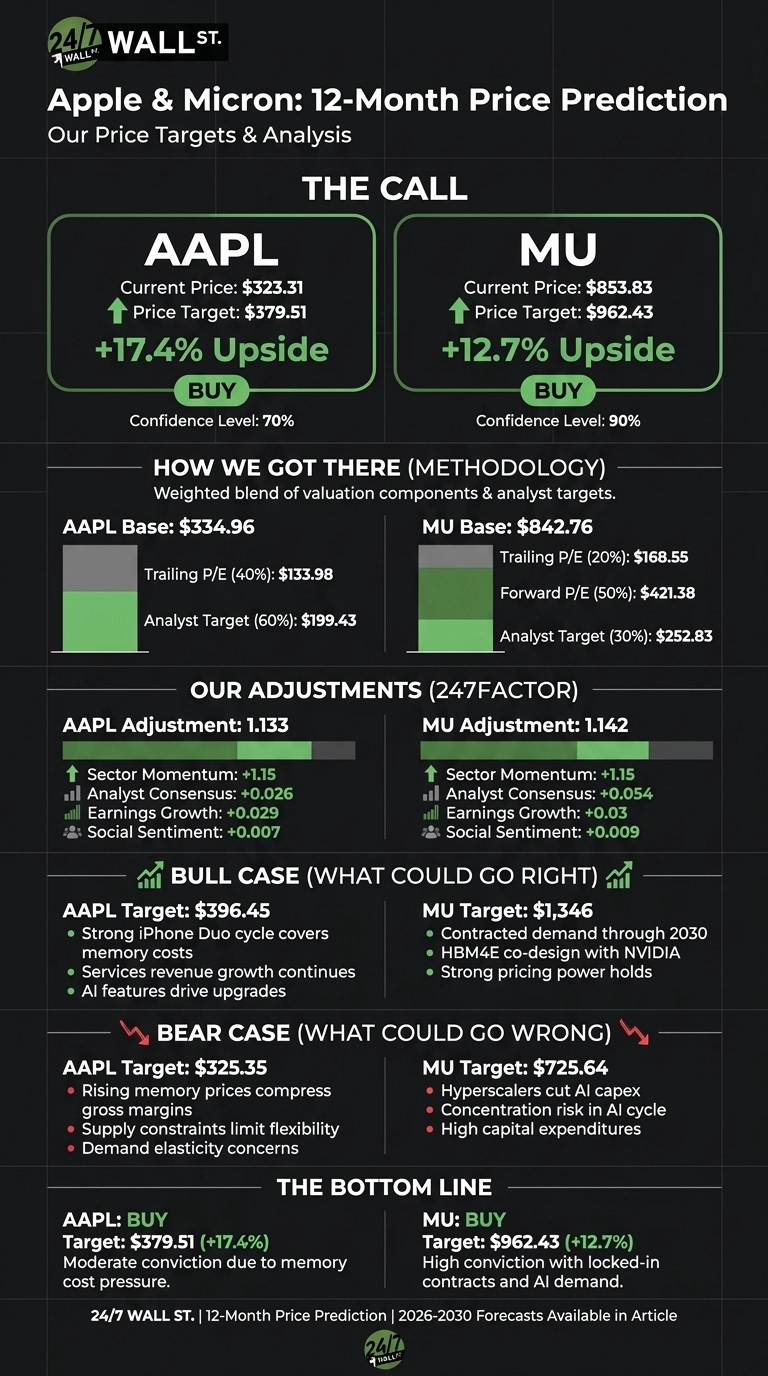
The 24/7 Wall St. price target for Micron is $962.43, about 12.7% above its $853.83 premarket price. For Apple, the 24/7 Wall St. price target is $379.51, roughly 17.4% above $323.31.
24/7 Wall St. Price Target Summary
| Metric | Apple | Micron |
|---|---|---|
| Current Price | $323.31 | $853.83 |
| Price Target from 24/7 Wall St. | $379.51 | $962.43 |
| Upside | 17.4% | 12.7% |
| Model Rating | BUY | BUY |
| Confidence Level | 70% | 90% |
Our model has high conviction on Micron because contracted demand runs through 2030. Conviction on Apple is moderate because memory inflation directly threatens its record margins.
Apple Slides After Earnings as Micron Cools From Its Peak
Apple fell 4.44% before the opening bell after its fiscal Q4 report. That leaves the stock down 5.99% for the week but up 19.25% year to date.
Revenue of $114.48 billion rose 11.7%, and EPS of $2.10 beat the $1.98 estimate. That was Apple’s 10th straight beat. Gross margin of 47.9% included roughly one point from tariff refunds, and inventories jumped to $14.54 billion from $5.72 billion.

Micron is up 199.39% year to date but down 20.55% over the past month, and Barron’s noted three hurdles the stock needs the market to clear.
Fiscal Q4 revenue of $54.23 billion rose 379.3%. Non-GAAP EPS of $33.42 beat the $31.35 estimate, and gross margin reached 87%. Micron guided Q1 revenue to $61.5 billion.

Why Bulls See Micron Near $1,346 and Apple Near $396
More than 75% of Micron’s fiscal 2027 shipments are already committed. Micron has signed 26 supply agreements running through 2030 and is co-designing HBM4E with NVIDIA (NASDAQ:NVDA).
Its president, Manish Bhatia, said Micron has “no line of sight to when supply and demand balance.” Analysts agree: 36 rate it Buy, with a consensus target of $1,561.91. Our bull case reaches $1,345.98.

Apple’s iPhone revenue rise to $57.58 billion from $49.02 billion, and Services reached $31.57 billion. The iPhone Duo and a new Siri lead the holiday lineup, and JPMorgan still sees upside despite memory costs. Our bull case is $396.45.

What Could Go Wrong as Memory Costs Climb
In July, Tim Cook, then Apple’s CEO, called memory pricing “a 100-year flood”. The CFO said “more than 100%” of the sequential margin decline came from memory. The bear case is $325.35. Apple’s growing Services revenue and price increases help handle that pressure, and the inventory makes may reflect early purchases.
Micron’s beta of 2.23 and fiscal 2026 capex of $30.71 billion raise the risk if AI spending slows. In the latest 13F data, 10 tracked funds cut positions while 3 added. Management counters that much of the capex funds clean rooms for 2028, and “the spend there doesn’t translate into bits.” The bear case is $725.64.
How SanDisk and Dell Frame Both Targets
SanDisk (NASDAQ:SNDK) benefits from the same NAND pricing rise as Micron. Shares trade at 13 times earnings with a 71.5% gross margin. Micron earns a higher margin at a lower forward multiple, which makes $962.43 look reasonable, even conservative.
Dell Technologies (NYSE:DELL) buys memory in bulk, much like Apple. Shares trade at 21 times earnings and carry a 20% gross margin. Apple’s premium multiple looks rich next to Dell. Its far wider margin gives it more room to handle memory inflation, which makes $379.51 look reasonable.
| Company | P/E | Gross Margin |
|---|---|---|
| Micron | ~5x (forward, model) | 87.0% (Q4) |
| SanDisk | 13 | 71.5% |
| Apple | 44 | 46.9% |
| Dell | 21 | 20.0% |
Micron Has the Stronger Setup as Both Targets Point Higher
Our model sets a 24/7 Wall St. price target of $962.43 for Micron (90% confidence) and $379.51 for Apple (70% confidence), and projects upside for both.
Locked-in contracts tip the scale toward Micron. Micron’s outlook improves if agreement pricing holds into 2028, and it weakens if hyperscalers cut capex. Apple’s outlook improves if the iPhone Duo cycle covers memory costs, and it weakens if gross margin slides below guidance.
Apple and Micron Price Prediction 2026-2030
Looking further ahead, the 24/7 Wall St. price target model projects where each stock could trade, assuming current trends hold.
| Year | Apple | Micron |
|---|---|---|
| 2026 | $347.43 | $868.24 |
| 2027 | $384.06 | $986.46 |
| 2028 | $406.29 | $1,029.53 |
| 2029 | $454.07 | $1,215.47 |
| 2030 | $481.59 | $1,293.53 |
These projections assume both companies keep performing. A memory supply glut or a stall in AI spending would change the path sharply.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.