Micron Stock Has Some Eye-Popping Analyst Targets. Here’s My Price Prediction
Wall Street analysts are chasing Micron with targets that leave our model cold, and the gap between their optimism and our measured call comes down to one overlooked risk lurking beneath record-breaking earnings.

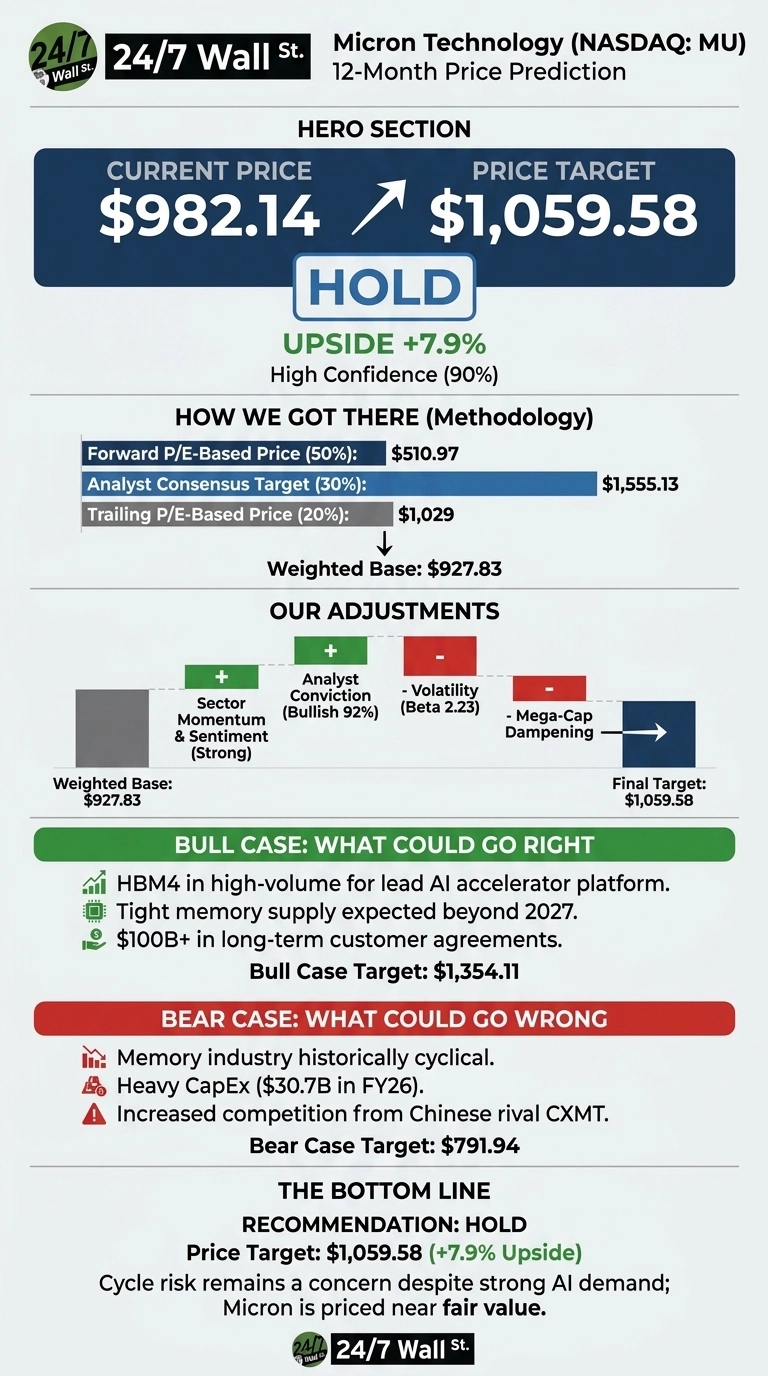
Our 24/7 Wall St. price target for Micron Technology (NASDAQ:MU | MU Price Prediction) is $1,059.58 over the next 12 months. With shares at $982.14 in Monday trading, that implies about 7.9% upside. Our call is hold, and our model carries a high confidence reading of 90%.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $982.14 |
| Price Target from 24/7 Wall St. | $1,059.58 |
| Upside/Downside | 7.9% |
| Recommendation | HOLD |
| Confidence Level | 90% |

The Street’s targets run well above ours. The consensus analyst target of $1,555.13 implies roughly 58% upside, and 92% of covering analysts lean bullish. My model is more measured, and the reasons come down to where memory sits in its cycle.

China Competition Fears Hit a Stock Up Over 240% This Year
Micron has fallen 8.63% over the past week and 4.44% over the past month, though it remains up 244.33% year to date. Monday’s 4.55% drop followed reports that Chinese rival CXMT is progressing a new chip (Barron’s). Shares now trade about 22% below the 52-week high of $1,254.81.
The fundamentals remain extraordinary. Fiscal Q4 revenue reached $54.23 billion, beating estimates of $50.97 billion, while non-GAAP EPS of $33.42 exceeded the $31.35 consensus. Guidance for fiscal Q1 calls for $61.50 billion in revenue and EPS of $38.15.
Why Bulls See $1,354 Ahead
Management expects DRAM and NAND conditions to “remain tight beyond calendar 2027,” and HBM4 is now in high-volume shipments for the lead AI accelerator platform. The bigger story is the Strategic Customer Agreements.
Micron said 14 of its first 16 agreements carry roughly $100 billion in minimum-price revenue, with floor prices delivering margins above any prior cycle peak. If that visibility earns a higher multiple, our bull case reaches $1,354.11.
Cyclical History Still Matters
Micron posted EPS of -1.91 as recently as fiscal Q2 2023, a reminder of how fast memory pricing can reverse. Capex hit $30.7 billion in fiscal 2026, and CXMT’s progress raises supply questions.
The bear case sits at $791.94. In fairness, that spending funds capacity backed by take-or-pay contracts, and fiscal Q4 free cash flow of $33.20 billion covers it well.
Micron Looks Cheap Next to SanDisk and NVIDIA
SanDisk (NASDAQ:SNDK) offers the best pure-play NAND comparison. It trades at a forward P/E of 8x, slightly higher than Micron’s 7x, despite Micron’s added HBM exposure.
NVIDIA (NASDAQ:NVDA) drives much of Micron’s HBM demand. Its forward P/E of 25x and PEG of 0.479 compare with Micron’s PEG of 0.16. Our target looks conservative relative to both peers.
| Company | Forward P/E | Analyst Target |
|---|---|---|
| Micron | 7x | $1,555.13 |
| SanDisk | 8x | $2,173 |
| NVIDIA | 25x | $328.72 |
Micron Price Prediction 2026-2030
The 24/7 Wall St. price target of $1,059.58 supports a hold rating with 90% confidence. The deciding factor is cycle risk.
A more positive position would emerge if more agreements close and margins hold near guidance of 86.25%. I’d stay cautious if CXMT gains ground or pricing moderates. Micron is a high-quality business priced near fair value today.

Our model projects where Micron could trade at each year’s end, assuming current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $1,015.05 |
| 2027 | $1,107.38 |
| 2028 | $1,089.59 |
| 2029 | $1,171.88 |
| 2030 | $1,233.84 |
The projections rest on Micron continuing to execute on HBM and contract pricing. A faster AI expansion or a memory downturn could swing results sharply. For readers hunting the next monster run in AI silicon, we reverse-engineered what the biggest tech winners looked like early in a free playbook here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.