Broadcom Stock Could Be Approaching a Major Turning Point. Here’s the Price Target
Broadcom's share price keeps falling while its AI revenue explodes to record highs, and that widening gap between fundamentals and stock performance rarely lasts long before something gives.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
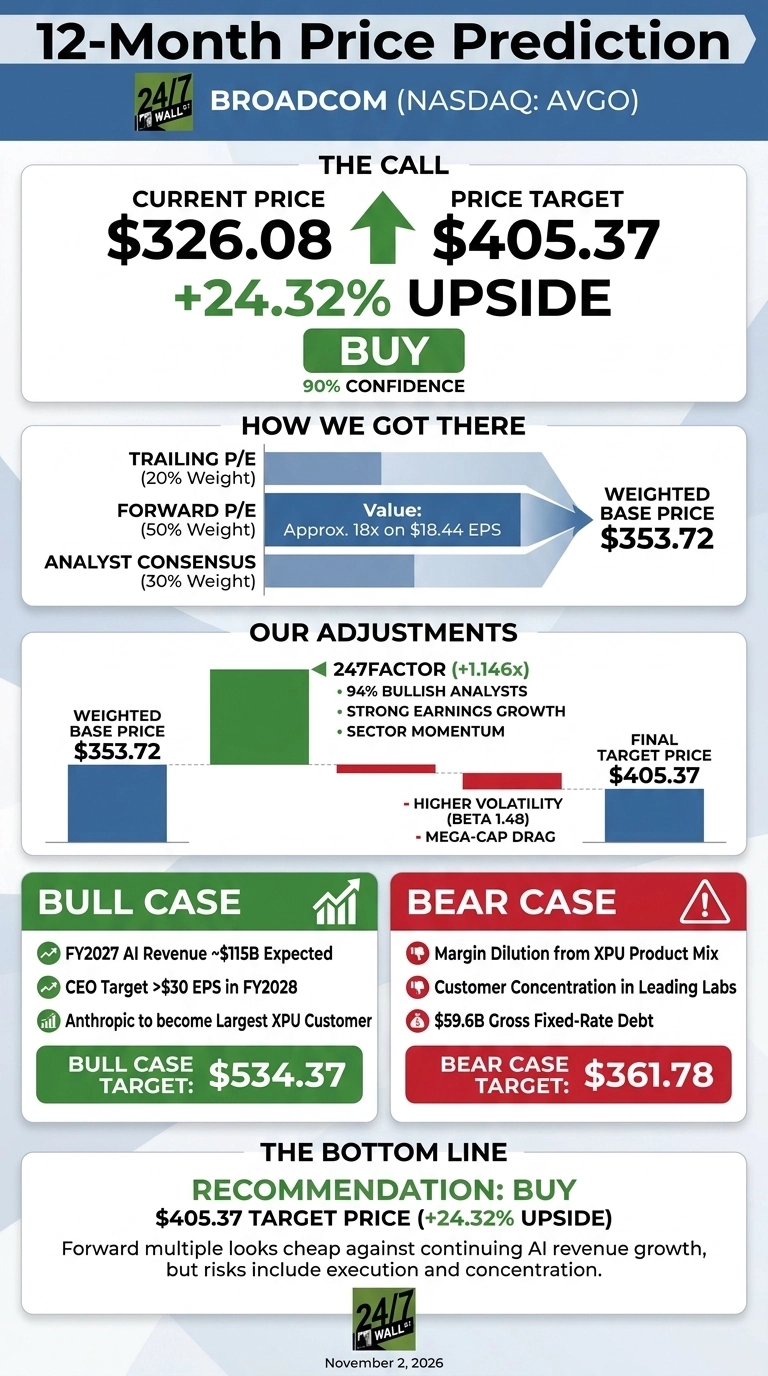
Broadcom (NASDAQ:AVGO | AVGO Price Prediction) closed at $326.08. The 24/7 Wall St. price target for Broadcom is $405.37 over the next 12 months. That implies 24.32% upside, and our model carries a buy rating with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $326.08 |
| Price Target from 24/7 Wall St. | $405.37 |
| Upside/Downside | 24.32% |
| Recommendation | BUY |
| Confidence Level | 90% |

The setup looks like a turning point to me. The stock sits 33.9% below its 52-week high even as management guides fiscal Q4 revenue to $34.8 billion, up 93% year over year. The share price and the fundamentals are moving in opposite directions, and I expect that gap to close.
A Sharp October Pullback Despite Record AI Sales
Shares fell 5.48% on October 30. Over the past month they are down 7.15%, and they are down 5.27% year to date. The stock trades 12.85% above its $288.95 52-week low.
Fiscal Q3 revenue came in at $29.591 billion, ahead of the $29.44 billion consensus. Non-GAAP EPS of $3.32 beat the $3.2382 estimate. AI semiconductor revenue reached $16.70 billion, up 221%.
Broadcom also set up an AI financing platform with Apollo Global Management (NYSE:APO) and Blackstone (NYSE:BX) that targets more than 20 gigawatts of compute for OpenAI and Anthropic. That expansion has to be powered, cooled and connected by somebody, and we featured seven suppliers behind the scenes in a free AI infrastructure report.
Why Bulls See $534 Within Reach
Management expects AI revenue of about $115 billion in fiscal 2027 and $230 billion in fiscal 2028. CEO Hock Tan said Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028.”
He also said “Anthropic is on track to become our largest XPU customer in 2027.” The consensus analyst target is $530.14, with 47 Buy or Strong Buy ratings and 3 Holds. Our bull case is $534.37.

Margin Dilution and Customer Concentration Top the Risk List
Gross margin guidance for Q4 is about 73%, compared with 78% a year ago, because memory-heavy XPUs make up a growing share of sales. Operating margin is guided near 66% as revenue increases much faster than expenses.
A few of leading research labs drive most AI demand, and gross fixed-rate debt stands at $59.6 billion. Broadcom did repay $5.6 billion of that debt in Q3. Our bear case is $361.78, which is still above today’s price.
Broadcom Trades in Line With NVIDIA and Far Below AMD
NVIDIA (NASDAQ:NVDA) is the GPU leader that Broadcom’s custom accelerators compete against. NVIDIA increases revenue 105.85% at a P/E of about 41, which is nearly the same multiple Broadcom carries.
Advanced Micro Devices (NASDAQ:AMD) is fighting for the same hyperscaler budgets. AMD trades near 190x earnings on 50.11% growth. Next to these two peers, our target looks conservative.
| Company | Trailing P/E | Revenue Growth (YoY) |
|---|---|---|
| Broadcom | 42 | 85.5% |
| NVIDIA | 41 | 105.85% |
| AMD | 190 | 50.11% |
Growth at a Discount Makes Broadcom Compelling
The 24/7 Wall St. price target stands at $405.37, with a buy rating and 90% confidence. What determines it for me is the forward multiple, which looks cheap against AI revenue that is still growing.
Upside builds up if Q4 AI revenue reaches $21.7 billion while operating margins hold. The outlook weakens if a major lab delays its deployments. The case for Broadcom remains positive for now.

Broadcom Price Prediction 2026-2030
Looking further out, this is where the 24/7 Wall St. price target model projects Broadcom could trade if current growth and market conditions continue.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $405.37 |
| 2027 | $412.08 |
| 2028 | $459.78 |
| 2029 | $542.97 |
| 2030 | $589.32 |
The projections rest on Broadcom continuing to execute on its custom accelerator roadmap. Results could land well above or below these figures depending on hyperscaler spending, supply bottlenecks and how fast AI networking is adopted.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.