Jim Cramer’s Surprise Midterm Winner: Apple, Because Fewer Data Centers Could Mean Cheaper Memory
Voters rejected data center projects at the ballot box, and Wall Street pounced on an unlikely beneficiary in Cupertino. Skeptics call it a positioning trade, so one number in Apple's next report could decide who is right.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Jim Cramer has picked an unexpected winner from the midterm election results: Apple (NASDAQ:AAPL | AAPL Price Prediction). On Mad Money on November 4, he argued that voters who turned against new data center construction may have relieved Apple’s biggest cost problem, which is memory chips.
“If a lot of data center projects are being put on hold because the electorate has spoken, it’s possible that DRAM prices could stabilize. Or worse, they could even plummet. DRAM prices are the single biggest cause of Apple’s price increases,” Cramer said. He added: “I think Apple’s stock soared because the outlook for new data center construction may have changed, perhaps radically, because of these midterm election results.”
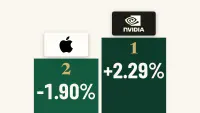
Cramer said Apple hit an all-time high that day. That was a fast reversal from the session before, when the stock “just got hammered in part because the gross margins of the company were coming down” on rising memory costs. Apple closed November 4 at $349.51 per share, which was up 29.0% year to date.
Why Apple and AI Data Centers Compete for the Same Chips
DRAM is the working memory inside phones, computers, and servers. It holds the data that a processor is using at a particular moment. Every iPhone, Mac, and iPad carries DRAM, plus NAND flash for storage. Cramer pointed out that “these modern AI data centers can have a gigantic amount of DRAMs in them.” As hyperscalers rush to fill new facilities, memory makers shift capacity toward them, and device makers like Apple pay more for whatever supply remains.
That pressure showed up in the fiscal fourth-quarter report Apple released on November 2. Gross margin came in at 47.9%, and tariff refunds added about one percentage point to that figure. Apple then guided December-quarter gross margin to 45% to 46%, and CEO John Ternus said, “we see the pricing for memory purchases continuing to increase.” Inventories also rose to $14.54 billion from $5.72 billion a year earlier, according to Apple’s earnings release filed with the SEC.

Election Data Points to a Slower Buildout
Co-host Carol Massar said on Bloomberg Businessweek that Bloomberg counted something like 40 local ballot measures that would limit data center development, and “all but one of them went against data centers.”
On CNBC’s Halftime Report, Scott Wapner relayed Dan Ives’ estimate that 10% of data centers will now not happen. Wapner also passed along a Goldman Sachs estimate that the election potentially affects 45% of planned data center capacity expansion. Rob Sechan drew the link to semiconductors on the same show: “If there’s going to be less data center buildout, there’s going to be pressure on the chips.”
Pushback That Caps Apple’s Upside
Some of CNBC’s own observers doubt the rally will last. On Fast Money, Tim Seymour put the move down to positioning and short covering and asked: “Are we to believe there’s never going to be another data center again? That’s not going to happen.” Melissa Lee called it “more of a slowdown than an end.”
Cramer hedged too. Earlier on November 4, he told CNBC that data centers will keep getting built, though “it’s going to make financing much harder for data centers.” On Mad Money he added a warning: “Never confuse what happens in the stock market with what happens in reality.” He continued, “The elections did not upend the business cycle.”
A slower pace of new projects still leaves current facilities buying memory. Contracts signed before the vote keep running, and memory makers decide how to split capacity between servers and consumer devices over quarters, so any relief on Apple’s costs would build gradually.
Gross Margin Will Prove or Break Cramer’s Thesis
Cramer’s argument depends on memory prices actually steadying or falling, and on that relief reaching Apple’s gross margin. That makes gross margin the figure to track. The December-quarter guide of 45% to 46% already reflects the memory hit, and results for that quarter are due when Apple posts them on its investor relations earnings call page.
Gross margin landing at the top of that range, or management moderating its view that memory pricing will keep rising, would be the first hard evidence for Cramer’s case. If the guidance holds and memory commentary stays the same, the November 4 move looks more like a positioning trade than a change in Apple’s cost picture. Keep an eye on the stock, but the earnings report will settle it.


Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.