Palantir’s CEO Just Said What Wall Street Doesn’t Want to Hear About AI
Palantir CEO Alex Karp called out Wall Street investors for getting rich on AI that isn't working the way they think, then backed it up with numbers that tell a complicated story about whether his own company proves his point.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
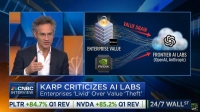
Palantir Technologies (NASDAQ:PLTR | PLTR Price Prediction) CEO Alex Karp used the company’s Q3 earnings call on Nov. 2 to question how investors price AI. A DA Davidson analyst asked about the AI market, and Karp replied, “I think really what happened on Wall Street is everybody invested in these firms early. Bless you guys. It’s hard to see the reality when you’re getting rich on something that’s not actually working the way you think it is.”
He also said that “the reality is, though, in industry, people realize when it gets real, you need us. And that market is much larger than we can service.”
Karp’s Real Target: Who Captures AI Profits
Karp still believes in AI’s potential. His question is which companies actually make money from it. He described buyers who are tired of “software companies that are reselling tokens and it counts as revenue.” He also praised the model makers. He called the labs partners and said “we are actually in a symbiotic relationship with them commercially because they’re growing a market that’s probably much, much bigger than it is today.”
Builders Versus Deployers Explains the Pitch
Chief Technology Officer Shyam Sankar laid out the reasoning behind Karp’s comments. “Palantir is obsessed with turning tokens into economic value,” he said. He called Palantir “the diffusion layer” and argued that “the fundamental unit of the enterprise is the workflow.” In his view, making individual workers faster can produce “no actual ROI.” Foundry, Ontology and AIP work at that workflow level. They plug fine-tuned open-weight models into the operations customers already run.

Third-Quarter Numbers Support the Argument
Revenue reached $2.313 billion, up 96% year over year. Adjusted operating margin hit 62%, compared with 51% a year earlier. Net dollar retention, which shows how much more existing customers spend over time, rose to 165%, an increase of 800 basis points from the prior quarter.
U.S. commercial revenue rose 148% to $984 million, exceeding U.S. government revenue for the first time. Trial deals are turning into much larger contracts. One industrial materials company turned a nearly $3 million pilot into a $29 million ACV deal. Management raised full-year revenue guidance to $8.53 billion to $8.534 billion.

Wall Street Is Still Holding Back
If Karp is right, Palantir benefits when investors start demanding returns on AI spending, because buyers move money toward projects that pay off. The stock doesn’t reflect that view yet. Shares traded at $173.11 midday, down 12.94% over the past week and 13.65% over the past year. Shares fell after the report as analysts pointed to slowing total contract value. Total contract value grew just 6%, and stock-based compensation rose to $318.9 million from $172.3 million a year ago.
At a market cap of about $396.5 billion and a trailing P/E near 252, Palantir has little room for mistakes. Total remaining deal value rose 55% to $13.4 billion. If that backlog keeps turning into revenue as fast as recent pilot programs have, Karp’s criticism of Wall Street will look early. If contract growth stays in single digits, that multiple will be hard to defend. Keep an eye on fourth-quarter revenue against guidance of $2.649 to $2.653 billion.

Contact [email protected] for any questions or corrections.
Joel South covers large-cap stocks, dividend investing, and major market trends, with a focus on earnings analysis, valuation, and turning complex data into actionable insights for investors.
He brings more than 15 years of experience as an investor and financial journalist, including 12 years at The Motley Fool, where he served as an investment analyst, Bureau Chief, and later led the Fool.com investing news desk. He has also co-hosted an investing podcast and appeared across TV and radio discussing market trends.