This Is the Number That Could Change Nvidia Stock’s Outlook for 2027
Wall Street already sees big upside in Nvidia, but one specific price target for 2027 reframes the entire investment case. The math behind it is simpler and more compelling than most investors expect.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

On the August earnings call for NVIDIA (NASDAQ:NVDA | NVDA Price Prediction), the chief executive put the whole business case into one line: “AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable. Now, compute is revenue.”
NVIDIA has the results to support it. Fiscal second-quarter revenue reached $96.22 billion, up 105.8% from a year earlier, and Data Center revenue grew 117% to $89.02 billion.
The stock has trailed the business. At $207.03, shares are up 11.27% year to date. They are also down 9.35% over the past month and sit below the 52-week high of $243.37. That gap brings me to the number that matters for 2027: $350 per share. Here’s how NVIDIA could get there.

Wall Street Already Sees 59% Upside
The average analyst price target is $328.95, which means about 59% upside. Ratings lean heavily bullish: 10 strong buys and 49 buys against 2 holds and 1 sell.

That optimism rests on growth. Analysts expect fiscal 2028 EPS of $15.9146 on revenue of $692.21 billion, compared with $9.3124 for the current fiscal year. That works out to about 71% EPS growth.
Management’s outlook lines up with it. NVIDIA expects fiscal 2028 revenue to grow approximately 70%, and the CEO said that figure is held back by supply: “Even though our demand is much greater than 70%, our supply allows us to confidently deliver 70%.”
Here’s What It Takes for NVIDIA to Reach $350
At today’s price, NVIDIA trades at 13x fiscal 2028 estimated earnings. At $350, the multiple would be 22x, close to the S&P 500’s forward P/E of 21x to 23x. In other words, NVIDIA only needs a market-average multiple while it grows earnings far faster than the market.

How NVIDIA could reach $350.
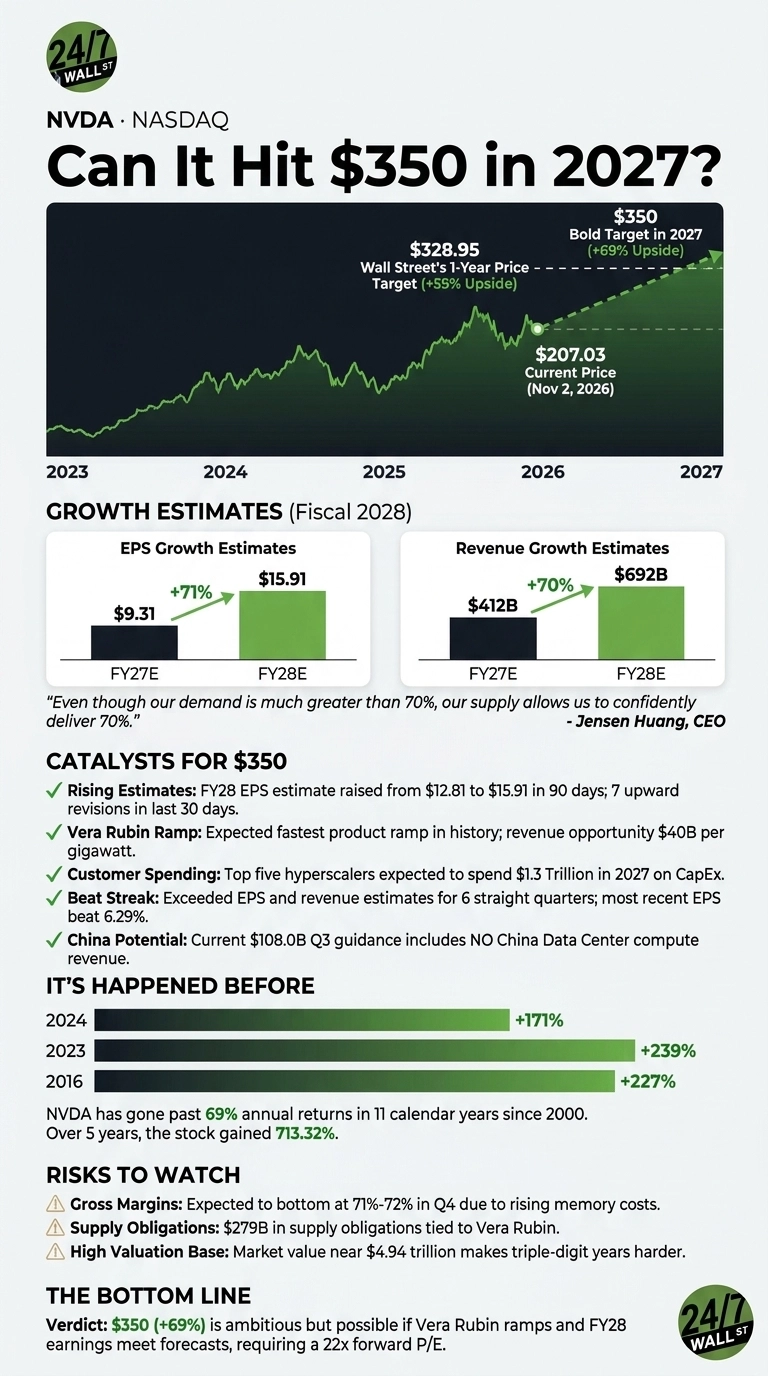
- Rising estimates: 90 days ago, analysts expected $12.8148 in fiscal 2028 EPS. Today the figure is $15.9146, and there were 7 upward revisions and no cuts over the past 30 days.
- Beat streak: NVIDIA has exceeded EPS and revenue estimates for 6 straight quarters. Its most recent EPS beat was 6.29%.
- Vera Rubin ramp: Management expects the fastest product ramp in NVIDIA’s history. Revenue opportunity per gigawatt rises to $40 billion, up from $25 billion with Blackwell.
- Customer spending: The top five hyperscalers are expected to spend nearly $800 billion in 2026 and $1.3 trillion in 2027.
- China potential: Guidance for $108B in third-quarter revenue includes no China Data Center compute revenue.

NVIDIA’s History Says $350 Is Within Reach
A 69% gain sounds aggressive, but NVIDIA has gone past that mark in 11 calendar years since 2000. Shares rose 239% in 2023, 171% in 2024 and 227% in 2016. Over the past five years, the stock has gained 713.32%.
NVIDIA’s market value near $4.94 trillion means triple-digit years will be harder to repeat. Reaching $350 depends on delivering on earnings and earning a market multiple.
The expansion behind those hyperscaler budgets also feeds power, cooling, and networking suppliers that often get overlooked next to NVIDIA (we rounded up seven of them in a free report here: 7 Stocks Powering the AI Boom).
$350 Is a Stretch, but the Math Holds Up
Reaching $350 would take a 69% gain. Wall Street already sees 59% upside, estimates keep rising and NVIDIA keeps beating them.
The main hurdles are gross margins expected to bottom at 71% to 72% in the fourth quarter as memory costs rise, plus $279B in supply obligations. If Vera Rubin ramps on schedule and fiscal 2028 earnings meet or beat the forecasts, a 22x multiple would get NVIDIA to $350.
Returns at this level shouldn’t be expected every year, but I’ve laid out how NVIDIA could deliver outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.