SanDisk Just Crashed 22% On Midterms, Down 43% Over 3 Months: One Of The Highest Ranked Sell Side Analysts Just Doubled Down That It Will Nearly Quadruple
SanDisk posted record results, yet the stock keeps sinking as Texas threatens data center moratoria. One of Wall Street's top-ranked analysts says the market has this wrong, and his reasoning hinges on three pillars.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

SanDisk (NASDAQ:SNDK | SNDK Price Prediction) currently trades at $828.80, and the average analyst price target is $2,023.62. That difference points to 144.16% upside.
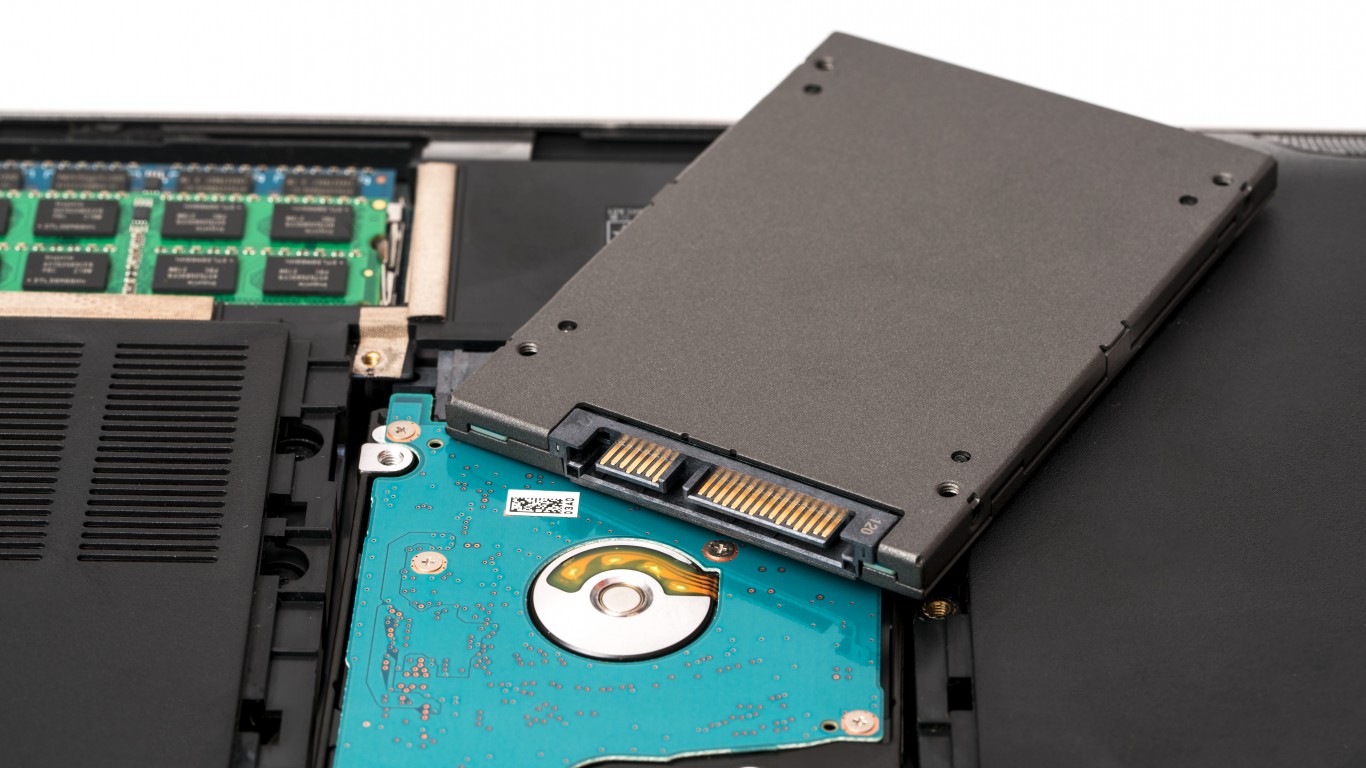
SanDisk makes NAND flash storage. It sells enterprise SSDs to AI data centers, embedded storage for phones, cars and industrial equipment, and retail memory cards. Since its spinoff from Western Digital (NASDAQ:WDC), it has become one of the market’s most-watched AI infrastructure names, and it is still up 249.14% year to date even after the latest rout.
Implied upside is well above 40%, and the stock has dropped more than 30% in a matter of weeks. Even so, one of the highest-ranked analysts on Wall Street is sticking with his call.
Midterm Results Turned an AI Winner Into a Data Center Policy Casualty
SanDisk fell 20.11% as investors started pricing in slower U.S. data center construction after Democratic gains in the midterms. That ended a 37.69% one-week decline and a 50.09% one-month collapse. Over three months the stock is down 38.63%.
Texas was the biggest worry. Its new governor campaigned on an immediate moratorium on new data centers. Goldman Sachs (NYSE:GS) economists warned that Democratic wins “are likely to lead to short-term data center moratoria, potentially affecting about 45% of planned US data center capacity expansion.”
The selling started before the election. SanDisk posted revenue of $11.03 billion, up 377.9%, and non-GAAP EPS of $49.51 against $46.27 expected. The stock still fell 13.47% that day. The only weak spot was consumer revenue of $397 million, down 39% year over year.
Rasgon’s $3,000 Target Backs Fundamentals Over Politics
Bernstein’s Stacy Rasgon repeated his Buy rating and his $3,000 12-month target after the selloff. That target is the high mark among standard sell-side models, and it implies 261.97% upside. He blames the pullback on macro noise and election sentiment, and he says enterprise memory fundamentals are solid.
His thesis rests on three pillars. First, dense storage is a constraint for AI clusters, so enterprise SSDs and High-Bandwidth Flash have to be deployed alongside GPUs (the same early AI infrastructure setup we cataloged in our free Next Nvidia playbook). Second, NAND supply is structurally tighter than the market thinks, which should push up average selling prices and gross margins. Third, operating leverage turns into free cash flow that pays for buybacks.
Datacenter revenue rose 61% sequentially to $4.8 billion. Guidance calls for $12.2 billion to $12.6 billion in revenue at 84.5% to 85.5% gross margins. About 50% of next year’s bits and roughly two-thirds of the following year’s are locked under multi-year agreements. CEO David Goeckeler said “our NBM pipeline exceeds our supply throughout the end of the decade.”
The broader Street agrees. Ratings break down as follows:
- Strong Buy: 4
- Buy: 17
- Hold: 3
- Strong Sell: 1
Estimates are still rising. The consensus for fiscal 2027 EPS rose to $226.2798 from $212.9458 90 days ago, with no downward revisions in the past month. Keep in mind that targets are opinions and do not guarantee results. Management itself told investors to model conservatively for the seasonally weak fiscal third quarter.
Every Memory Stock Fell, and SanDisk Fell Hardest
The whole group sold off together, and SanDisk took the deepest hit.
Shares of Micron Technology (NASDAQ:MU) fell 15.81% on the day and 37.21% over a month. At $669.51 against a $1,561.91 target, it implies 133.29% upside. Analysts are overwhelmingly bullish, with 36 Buy and 3 Hold ratings.
Western Digital fell 16.2% on the day and 34.89% over a month. It trades at $271.39 against a $613.38 target, or 126.01% upside, with no Sell ratings.
Shares of Seagate Technology (NASDAQ:STX) fell 15.44% on the day and 42.09% over a month. At $471.07 against a $1,044.83 target, it implies 121.80% upside, with 18 Buy ratings.
SanDisk has the largest implied upside in the group. It also fell the furthest, so it carries the most AI-linked risk among these stocks.
SanDisk Now Trades at 5x Forward Earnings Despite Triple-Digit Growth
At $828.80, SanDisk carries about 144.16% implied upside to the $2,023.62 consensus target, and only one analyst rates it a Strong Sell. Its forward P/E is about 5x, and the balance sheet holds no debt. Prices are quoted before the upcoming 8-for-1 stock split.
Over the past month SanDisk lost 50.09%, while the S&P 500 fell 5.92%. Year to date, SanDisk is up 249.14%, compared with 7.49% for the S&P 500.
Bull Case Leads, but Policy Risk Deserves a Real Discount
The upside scenario holds if data center bans stay local and short-lived, its multi-year contracts hold up, and pricing keeps rising modestly as management expects. The downside scenario gains weight if Texas-style restrictions spread, hyperscalers delay deployments, and NAND’s history as a cyclical business catches up with record margins.
A 5x forward multiple on a debt-free company returning 100% of excess cash already prices in a lot of bad news. That valuation leaves room for upside if the thesis holds. The next earnings report and any state moratorium headlines are the signals that will show whether Rasgon’s target is realistic or out of reach.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.