Nvidia Isn’t Staying in The $180s for Long
A political earthquake in Washington and a boardroom investigation into its CEO have rattled Nvidia shares, yet analysts keep raising their numbers. Two upcoming answers could decide which side of this standoff turns out to be right.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) trades at $186.64. Post-midterm panic and a headline about its CEO sent the stock down, while earnings estimates kept climbing.
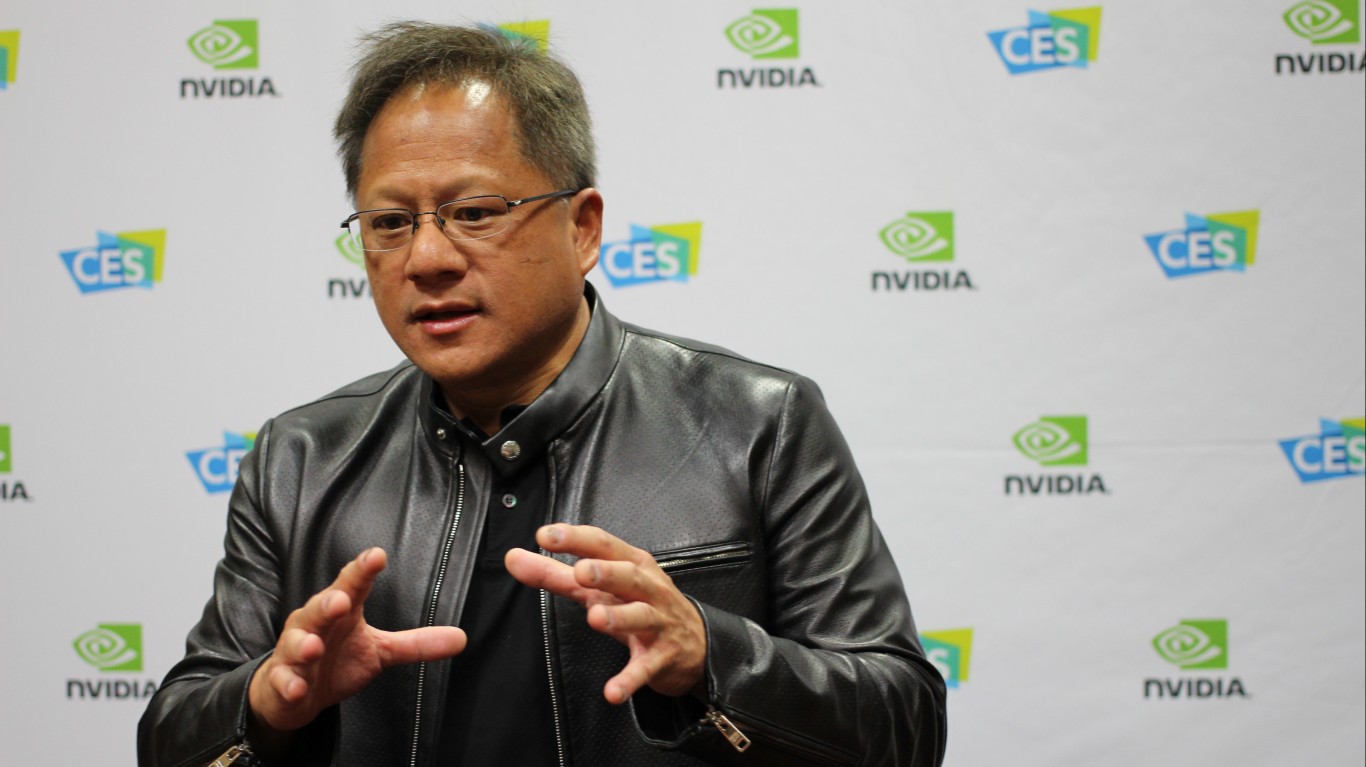
NVIDIA supplies the GPUs, networking gear and CUDA software that run most AI data centers. Last quarter, revenue rose 105.8% to $96.22 billion, and Data Center sales reached $89.02 billion. Two shocks caused the slide. First, Democrats won full control of Congress after running against unchecked data center expansion. Second, the board opened an independent investigation into reporting that CEO Jensen Huang was the target of a foreign intelligence effort.
Twelve Times Next Year’s Earnings Prices in Almost No Growth
NVIDIA trades at about 20x fiscal 2027 consensus EPS of $9.3124 and roughly 12x the fiscal 2028 estimate of $15.9146. Ninety days ago that fiscal 2028 figure stood at $12.8148, and analysts made zero downward revisions over the last 30 days.
The company has exceeded EPS estimates for six consecutive quarters. Most recently it posted $2.22 against a $2.09 consensus and guided third-quarter revenue to $108.0 billion. Vera Rubin is in full production at CoreWeave (NASDAQ:CRWV), Google Cloud, Azure, Oracle (NYSE:ORCL) and Nebius Group (NASDAQ:NBIS). A $327.14 consensus target and $99.0 billion in remaining buyback authorization add support.
Washington and the Corner Office Are Now Live Risks
Democrats with control of Congress are expected to push legislation that could curb the expansion of AI infrastructure, and Texas’s governor-elect promised a moratorium on new data centers. Any slowdown spreads past the chipmaker to the power, thermal, and networking suppliers feeding those sites (we covered seven of them in a free AI infrastructure report). NVIDIA carries $279 billion in supply commitments, guarantee obligations of up to $108.5 billion, and DSO that extended to 60 days from 45. A capex slowdown would hit all three at once.
Governance risk adds pressure. Republicans are also scrutinizing Huang’s ties to the alleged spy, and reports say companies linked to her kept buying Nvidia chips. With a beta of 2.247, NVIDIA amplifies every market shock.
Third-Quarter Results and Board Findings Will Set Direction
Patient investors can wait for two answers. The third-quarter report is due, and the board says it has no reason to believe national security or company secrets were compromised. Neither the investigation’s outcome nor actual legislation is known yet. A clean report plus a quick board resolution would ease both concerns. Concrete data center restrictions would add pressure to the outlook.
Analysts See 75% Upside While Shares Lag the Market
NVIDIA trades at $186.64. The $327.14 average target implies about 75% upside, though targets are estimates and carry no guarantee. The 62 covering analysts break down as follows:
- Strong Buy: 10
- Buy: 49
- Hold: 2
- Sell: 1
The trailing P/E is 24. Shares fell 21.4% over the past month, while the S&P 500 (via SPDR S&P 500 ETF Trust (NYSEARCA:SPY)) dropped 5.56%. Year to date, NVIDIA is up 0.31% against 7.83% for the index. The full-chain put/call ratio of 0.73 still leans bullish.
Catalysts That Could Move NVIDIA From the $180s
At $186.64, NVIDIA’s outlook rests on a few near-term catalysts.
The path higher starts with the third-quarter report. Revenue guidance of $108.0 billion excludes China, and the quarter’s consensus EPS is $2.4733. Another beat would refocus the market on underlying demand.
New legislation takes months to pass, while Vera Rubin shipments arrive every quarter. As the post-midterm shakeup cools, attention may return to earnings power that trades at only 12x next year’s estimates.
Two things would break the thesis: findings that Huang compromised company secrets, or binding federal limits on data center construction. Watch the board’s updates and congressional committee activity.
NVIDIA trades at 12x forward earnings after a quarter in which revenue doubled.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.