Nvidia Expects Chip Sales to Double in 2027
Jensen Huang just told a Scotland audience something about 2027 chip demand that sent analyst models scrambling and put NVIDIA's stock within striking distance of an all-time high.

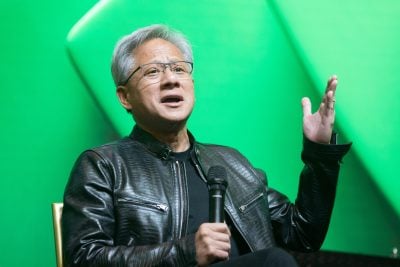
Shares of NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) are trading higher Thursday, up 2% to $219 in late-morning trading, after CEO Jensen Huang told an audience at a Scotland tech gathering that chip sales in 2027 are projected to roughly double compared to 2026. The move puts the stock back within reach of its 52-week high of $236.

Huang Signals a Doubling in 2027 Chip Sales
Huang confirmed at the event that shipment and sales volumes are expected to increase twofold next year, echoing what management already told investors on the August 26, 2026 earnings call. On that call, the CFO said “Customers’ forecasts point to our growth doubling next year” and framed the fiscal 2028 outlook, which calls for roughly 70% revenue growth, as “a supply-constrained outlook.” Huang added that “The unconstrained is significant.”
The doubling narrative is being driven by the Vera Rubin platform, which entered full production alongside continued Blackwell deployment. Vera Rubin is expected to be “the fastest product ramp in NVIDIA’s history,” with per-gigawatt revenue opportunity rising to roughly $40 billion, up from $25 billion on Blackwell. Huang also stressed at the Scotland event that AI safety is paramount and that unsafe products should be withheld from the market.
Supply Commitments and Sovereign AI Are Locking In Demand
The demand backdrop is visible in NVIDIA’s own balance sheet. Supply obligations swelled to $279.0 billion, largely tied to memory procurement for Vera Rubin, per NVIDIA’s most recent 8-K filing. Management also disclosed guarantee obligations capped at $108.5 billion for AI cloud partners and said financing platforms with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs, and KKR are expected to mobilize over $500 billion of third-party capital for AI infrastructure.
Sovereign and enterprise AI, which Huang calls the invisible half of the business, is “growing 100% a year.” Sovereign AI revenue alone grew 35% sequentially and more than tripled year over year. Neocloud partners are expected to exit the year with eight gigawatts of installed capacity, versus roughly three gigawatts at the end of 2025. AWS is deploying an additional 2 million GPUs through fiscal 2029, and OpenAI’s existing and planned commitments now represent roughly 12 gigawatts of NVIDIA compute. All those gigawatts have to be powered, cooled, and networked by somebody, which is why we profiled seven of those suppliers in a free AI infrastructure report.
Estimate Revisions Are Racing to Catch Up
Analyst models are re-rating quickly. Consensus EPS for the fiscal year ending January 2028 has climbed from $12.67 ninety days ago to $15.57 today, with 39 upward revisions in the past 30 days and zero cuts. Revenue for that year is now pegged at roughly $678 billion. NVIDIA’s most recent quarter delivered $96.22 billion in revenue, up 105.8% year over year, and management guided Q3 to $108.0 billion, so the doubling comment lands on top of an already-hot setup.

At $219, NVIDIA trades at a forward P/E of 23, with a $329 average analyst target and a market cap of roughly $5.29 trillion. Shares are up 17.8% year to date despite a 2% pullback over the past month.

What to Watch Next
Keep an eye on the stock into the close to see whether today’s move holds above the $213 50-day moving average. The next hard catalyst is the fiscal Q3 report, where investors will look for confirmation that Vera Rubin is on pace to hit management’s target of roughly 20% of data center revenue in the current period.

Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.