Despite CoreWeave Plummeting 55% Over 6 Months This Wall Street Team Maintains That a 400% Return Will Materialize

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
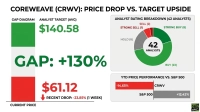
CoreWeave (NASDAQ:CRWV) is priced at $48.98, while Wall Street’s average price target sits at $131.53. That gap implies 168.5% upside.
CoreWeave runs a cloud built specifically for AI training and inference, renting out massive clusters of GPUs. Its contracted revenue backlog stood at roughly $104B at the end of the second quarter, with more than $25B in net new commitments added early in the third. Customers include OpenAI and Anthropic, and NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) holds a $2B equity interest.
CoreWeave is one piece of a much larger AI infrastructure trade. The suppliers that handle electricity, thermal management, and data-center interconnects for these GPU clusters rarely make headlines, and we rounded up seven of them in a free report here: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers).
The gap matters now because CoreWeave reports quarterly results this week. The market prices it as a credit risk. Analysts still price it as a growth story.
Debt Fears Sent CoreWeave Down 57% in Six Months
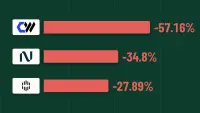
Credit anxiety caused the collapse. Shares fell 57.3% over six months. The past month alone took 40.33% off the stock. Yields on some CoreWeave bonds maturing in 2031 jumped above 16%, and its five-year credit default swap spread rose above 1,240 basis points. Politics added pressure. After the midterms, voters rejected data centers in all but one of the 41 ballot measures. CEO Michael Intrator wrote that the company does “not anticipate any impact to CoreWeave’s existing customer commitments or associated backlog”.
The balance sheet explains why lenders pulled back. Second-quarter revenue rose 112.3% to $2.575B, yet the net loss widened to $626M from $290M. Interest expense climbed to $640M from $267M, and capex of $6.422B produced free cash flow of -$5.743B. A securities class action alleging hid data center construction delays adds legal risk.
Rosenblatt Holds a $250 Target Implying a 410% Rebound
Rosenblatt Securities analyst John McPeake keeps the highest target on Wall Street at $250.00, even after sector-wide target revisions. From the current price, that implies 410.4% upside. His thesis rests on CoreWeave’s first-mover advantage, a revenue run-rate growing as commitments convert to live clusters, and aggressive use of debt to buy next-generation NVIDIA hardware before traditional clouds catch up. That third pillar is exactly what the bond market now doubts.
The broader Street still leans bullish. Of 42 analysts, 8 rate it Strong Buy, 24 Buy, 7 Hold, 2 Sell and 1 Strong Sell.
Bulls point to operating evidence. Adjusted EBITDA reached $1.510B at a 59% margin, operating cash flow turned positive at $679M, and EPS of -$1.14 beat the -$1.447 consensus. Active power is 1.5 GW against 3.7 GW contracted, with a goal above 8 GW by 2030. The 12-month thesis depends on converting that contracted power into revenue faster than interest costs compound.
Every Neocloud Fell, but Applied Digital Screens Cheapest to Analysts
The whole peer group sold off together, so CoreWeave’s slide reflects sector-wide stress.
Nebius Group (NASDAQ:NBIS) dropped 36.02% in a month but remains up 68.99% year to date. At $141.45 against a $281 target, implied upside is 98.7%, smaller than CoreWeave’s. Ratings stand at 2 Strong Buy, 13 Buy, 6 Hold and 1 Sell.
Applied Digital (NASDAQ:APLD), which rents AI data centers to customers including CoreWeave, fell 29.39% in a month. With shares at $16.72 and the average target at $60.94, implied upside is 264.5%, with 14 Buy-side ratings among 16 and no Sells.
IREN (NASDAQ:IREN) lost 39.16% in a month. At $21.41 against a $64.08 target, implied upside is 199.3%. Ratings show 3 Strong Buy, 13 Buy, 4 Hold and no Sells.
Applied Digital carries the largest analyst-implied upside, followed by IREN. CoreWeave sits mid-pack, so its discount is shared across the group. Targets for every name here are estimates, and the analysts behind them can be wrong.
CoreWeave Trails the S&P 500 by a Wide Margin This Year
CoreWeave is priced at $48.98, against a 42-analyst average target of $131.53 and implied upside of 168.5%. The stock is down 31.6% year to date, while the S&P 500 is up 10.37%.
Over one year, CoreWeave fell 52.91% versus a 12.17% gain for the index. Shares sit near the $40.58 52-week low and far below the $138.25 high.
CoreWeave’s Upside Hinges on Its Lenders
Optimism builds if this week’s report shows backlog converting to revenue fast enough to outrun interest costs, and if management secures financing at rates that calm the bond market. The downside deepens if bond yields keep climbing and the company must raise capital on punitive terms or dilute shareholders heavily.
The bull path is clear: bring contracted gigawatts online, let that 59% EBITDA margin generate cash, and the stock re-rates toward targets. On the bear side, total liabilities of $72.05B against $5.024B of equity leave little margin for construction delays or a political backlash against data centers.
Financing remains the key variable. Rosenblatt’s $250 target requires the financing engine to keep running, and right now the credit market is indicating otherwise. Keep an eye on the stock after earnings for any shift in borrowing costs.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.