Hedge Funds Dumped Tech at a Near-Record Pace Right Before Chip Stocks Jumped 7%

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
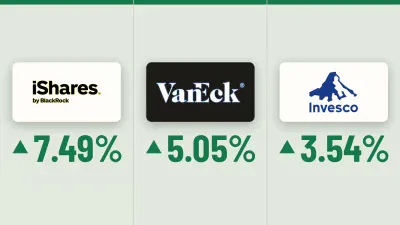
Goldman Sachs prime brokerage data through November 6, 2026, showed hedge funds sold technology stocks at a pace roughly matching the highest levels on record since 2016. The morning that data was reported, November 9, the Philadelphia Semiconductor Index rose 6.9%, its best day since July 30.
The iShares Semiconductor ETF (NASDAQ:SOXX) closed at $146.76, up $10.23, or 7.49%, and then slipped to $146.41 after hours. The VanEck Semiconductor ETF (NASDAQ:SMH) gained $23.45, or 5.05%, to $487.41. The Invesco QQQ Trust (NASDAQ:QQQ) rose 3.54% to $679.35.
For chip fund holders, the central question is how much of this move reflected forced selling and how much reflected a review of AI demand. The expansion thesis still depends on the companies providing power, cooling, and networking to the data centers, which we profiled in a free report on seven AI infrastructure names that are not chipmakers.
What the Prime Brokerage Data Actually Shows
Tech was the most heavily net-sold sector, both globally and in the U.S. That selling produced the biggest wave of single-stock net selling in four months. Funds also sold U.S. industrials at the fastest pace since April 2020.
Among U.S. fundamental long/short funds, gross leverage fell 8.7 percentage points to 207.5%, the largest drop since March 2020. Gross leverage is a fund’s total long plus short positions measured against its capital, so a drop this size means funds cut both sides at once.
Net leverage measures how much a fund is leaning on the market’s direction. It fell 3.7 points to 43.3%, the largest drop since the April 2025 “Liberation Day” tariff week. By November 6, funds had turned net buyers, mostly to cover index and ETF shorts.
Why Chip Funds Bounced Harder Than the Market
The selling came during a post-midterm rout. On November 5, the Nasdaq-100 had its deepest drop since the Covid pandemic and lost $2.3 trillion in market value in a single day.
On November 9, the S&P 500 rose 2.4%, or 173.08 points, to 7,549.94. The Nasdaq Composite gained 2.7% to 25,253.14, and the Nasdaq-100 added 3.4%.
Funds cut their shorts along with their longs. Buying back those shorts can push prices up quickly even when nobody has new confidence in the stocks.
The rally was also broad. Bespoke posted on X on November 9: “The semis are up 5% even though its biggest member is down 5%. Wild times.” A rally that wide likely helped SOXX more than SMH, because a fund that leans harder on its largest holding would trail on a day like that.
Strategists Split on Whether the Selling Is Done
JPMorgan’s Dubravko Lakos-Bujas said the unwind of long momentum positions against the market was the largest in about 40 years, and he called the pullback largely a “deleveraging event.” Lakos-Bujas and his team kept their year-end S&P 500 target of 8,000.
Morgan Stanley’s Michael Wilson said the correction is in its final phase, with the S&P 500 approaching his downside target of 7,100 to 7,300. Citigroup strategists, meanwhile, cut U.S. stocks and global tech to neutral.
Light positioning can support a rebound, but it does not indicate when selling will end. Funds can start selling again if chip guidance or AI spending plans weaken.
What Washed-Out Positioning Means for SOXX Holders
The evidence suggests the SOXX selloff was driven largely by positioning. Gross leverage fell far more than net leverage, which looks more like forced risk-cutting than a permanent change in how funds view chips.
The fund was still up 46.45% year to date after a 21.29% drop over the past month. SMH was up 35.34% for the year after a 19.21% monthly decline.
QQQ has carried smaller swings over the same stretch. It fell 9.57% over the month, is up 10.59% for the year, and holds software, retail, and consumer stocks alongside chipmakers.
The next test is the October CPI report at 8:30 a.m. ET on November 10. A hot inflation reading followed by a SOXX close below $136.53, where it started on November 9, would mean the case that this was only deleveraging is wrong.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.