Qualcomm Price Prediction: Automotive Boom Could Spark a Surprise Rebound

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
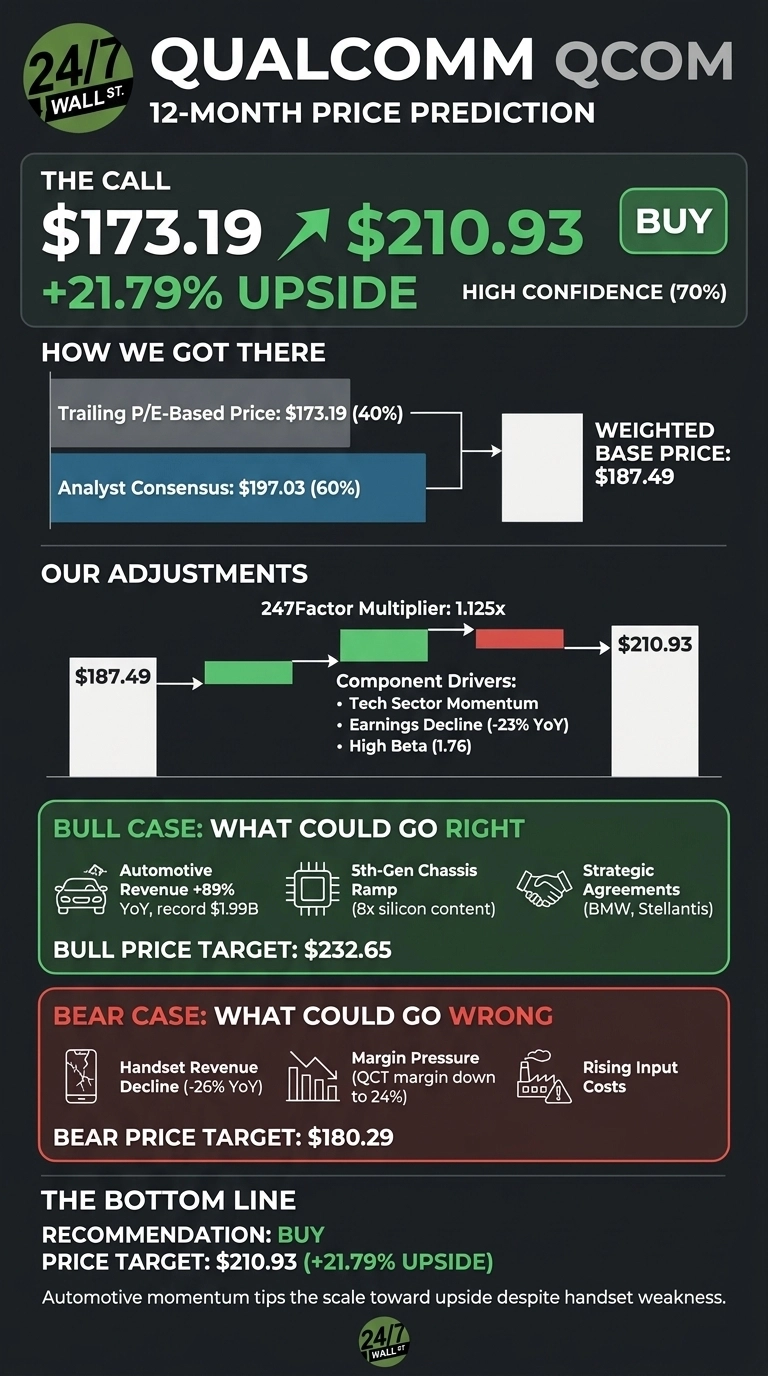
The 24/7 Wall St. price target for Qualcomm (NASDAQ:QCOM | QCOM Price Prediction) is $210.93. That is 21.79% above the latest price of $173.19, and the stock earns a buy rating.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $173.19 |
| Price Target from 24/7 Wall St. | $210.93 |
| Upside/Downside | 21.79% |
| Recommendation | BUY |
| Confidence Level | 70% |
The thesis rests on a segment many investors still miss. Automotive revenue reached a record $1.99 billion in fiscal Q4, up 89% year over year, while handset revenue fell 26%.
Our model expects the growth drivers to win that contest over the next 12 months. Confidence sits at a fairly high level because real earnings pressure offsets a diversification story that keeps gaining traction.
Record Auto Quarter Collides With a Shrinking Handset Business
Shares fell 5.35% over the past week and 4.2% over the past month, but they are up 2.85% year to date. The 52-week range runs from $120.88 to $257.56. On November 4, the stock rose 5.33% in regular trading.
The move came on the same day SpaceX signed a deal with Qualcomm to provide network technology for U.S. mobile service. After the bell, shares slid as smartphone weakness clouded the growth push.
Fiscal Q4 revenue of $10.32 billion came in ahead of the $10.14 billion estimate, yet it fell 8.4% year over year. Non-GAAP EPS of $2.17 exceeded the $2.1561 consensus. Management said automotive ended fiscal 2026 at an annualized run rate of about $8 billion, “well above the $7 billion expectations we provided last quarter.”
Why Bulls See $232 and Beyond
Commercial shipments of the fifth-generation Snapdragon digital chassis began in the September quarter. Management called it Qualcomm’s “largest generation-to-generation content increase”, with silicon content 8x higher than the third-generation platform. Strategic agreements with BMW and Stellantis support the ramp, and the company-wide design win pipeline grew 70%.
Data center adds a second driver: an Amazon collaboration, a $5 billion fiscal 2027 target and projected non-handset growth above 60%. The analyst consensus includes 2 Strong Buy ratings alongside 9 Buy ratings. The bull case reaches $232.65.

What Could Keep the Rebound in Check
Analyst ratings lean toward hold, with 23 holds. GAAP EPS was $1.17 and operating income fell 53.5%. Much of that gap reflects $235 million in restructuring, $141 million in acquisition charges and a $120 million legal settlement.
The QCT margin fell to 24% from 29% on rising input costs, although pricing actions should show their full benefit in the second half of fiscal 2027. Automotive and IoT revenue is guided “approximately flat sequentially” for fiscal Q1. The bear case is $180.29.

Qualcomm Trades Between Texas Instruments and NVIDIA
Texas Instruments (NASDAQ:TXN) is a good comparison because, like Qualcomm, it sells chips to car manufacturers. TI trades at 27x forward earnings on quarterly revenue growth of 27.7%. At 17x, Qualcomm looks cheap if automotive growth eventually raised its total revenue.
Another competitor in both data center and automotive is NVIDIA (NASDAQ:NVDA). Its automotive revenue was $604 million in its fiscal Q4, against Qualcomm’s $1.99 billion, and it trades at 13x forward earnings. Compared with these two peers, our target looks reasonable.
| Company | Forward P/E | Quarterly Revenue Growth YoY |
|---|---|---|
| Qualcomm | 17x | -4% |
| Texas Instruments | 27x | 27.7% |
| NVIDIA | 13x | 105.9% |
Automotive Momentum Tips the Scale Toward Upside
The 24/7 Wall St. price target of $210.93 carries a buy rating at 70% confidence. Even our bear case sits above the current trading price.
A more positive position would develop if the fifth-generation chassis keeps auto revenue climbing and pricing restores QCT margins. A more cautious view would follow if handset declines deepen beyond management’s flat-to-down outlook.
This shows where our model projects Qualcomm could trade, assuming current trends hold:
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $210.93 |
| 2027 | $214.62 |
| 2028 | $246.59 |
| 2029 | $278.04 |
| 2030 | $302.67 |
The projections depend on Qualcomm continuing to execute on diversification. Data center traction or a sharper handset slump could move results significantly both ways.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.