Qualcomm Stock Has an AI Opportunity Most Nvidia Investors May Be Overlooking
Qualcomm just posted a 61% automotive surge and quietly signed two hyperscaler custom silicon deals, yet the market still prices it like a handset company. Here is why that gap may not last much longer.


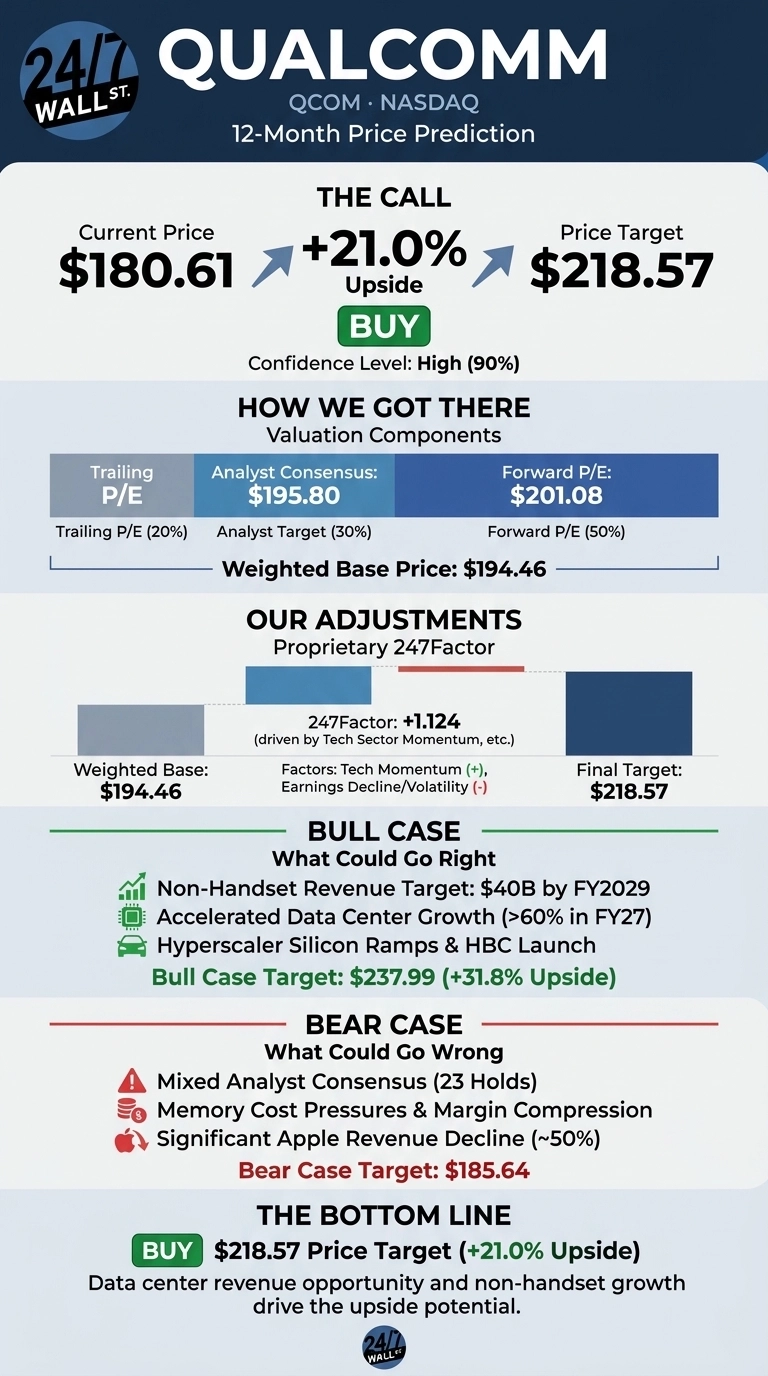
Our 24/7 Wall St. price target for Qualcomm (NASDAQ:QCOM | QCOM Price Prediction) is $218.57 over the next 12 months. That is 21% above the current $180.61. Our model rates the stock a buy, and our confidence is high.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $180.61 |
| Price Target from 24/7 Wall St. | $218.57 |
| Upside | 21.0% |
| Recommendation | BUY |
| Confidence Level | 90% |
Most AI investors stay focused on NVIDIA (NASDAQ:NVDA). Meanwhile, Qualcomm is quietly building a data center business that includes two hyperscaler custom silicon engagements.
Both should start producing revenue in the December quarter. At a forward P/E of 18, the market is valuing Qualcomm as a handset company.
Handset Weakness Is Hiding a 61% Automotive Surge
Over the past week, Qualcomm rose 4.94%. It is down 8.43% over the past month and up 7.26% year to date. Shares sit 29.9% below the 52-week high of $257.56. In fiscal Q3, revenue came in at $9.95 billion, ahead of the $9.67 billion estimate. Non-GAAP EPS of $2.21 missed the $2.22 estimate, which ended a six-quarter beat run.
Handset revenue fell 20%. Automotive revenue rose 61% to $1.59 billion. In October, Qualcomm won a trial verdict and declared its quarterly dividend. Reuters also reported performance-focused job cuts worldwide.

Why Bulls See $238 Ahead
Management is aiming $40 billion in non-handset revenue by fiscal 2029, including more than $15 billion from the data center. Non-handset growth should rise from 24% in fiscal 2026 to more than 60% in fiscal 2027. Wafer production for the hyperscaler chips has already begun.
The HBC accelerator is scheduled to launch in mid-2027. Qualcomm also raised its exit-rate outlook for automotive to about $7 billion a year after BMW named it lead compute provider. Our bull case of $237.99 implies 31.8% upside.

What Could Stall the Data Center Story
Analysts lean conservative, with 23 Hold ratings against 11 Buy or Strong Buy ratings. Operating income fell 41.13% as memory and wafer costs rose. Management also expects Apple (NASDAQ:AAPL) product revenue to drop about 50% from the September quarter to the December quarter.
Bulls would counter that Qualcomm is rolling out double-digit price increases that should bring gross margins back to their historical range. Our bear case of $185.64 still sits above today’s price.

Qualcomm Trades at a Steep Discount to NVIDIA and Broadcom
NVIDIA is the benchmark for AI valuation. It trades at 42 times earnings, compared with 34 for Qualcomm. NVIDIA earns that premium with a 55.6% net margin. Broadcom (NASDAQ:AVGO) is the closest comparison for custom ASICs.
Its AI semiconductor revenue reached $16.70 billion, up 221%. That is the market Qualcomm is just entering (we covered seven suppliers riding the same expansion, from power to networking, in a free AI infrastructure report). Against these peers, our target looks conservative.
| Company | Market Cap | Latest-Quarter Revenue Growth |
|---|---|---|
| Qualcomm | $192.86B | -4.0% |
| NVIDIA | $5.21T | 105.85% |
| Broadcom | $1.58T | 85.5% |
Data Center Revenue Tips the Scale Toward Upside
The 24/7 Wall St. price target of $218.57 carries a buy rating with 90% confidence. Cheap valuation coupled with hyperscaler revenue that is close at hand tips the scale.
I would find Qualcomm compelling if December-quarter data center revenue shows up as promised. I would turn conservative if price increases fail to restore margins.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $181.48 |
| 2027 | $218.57 |
| 2028 | $257.78 |
| 2029 | $284.78 |
| 2030 | $309.06 |
The projections rest on Qualcomm staying with its current strategy. Results could move well above or below them depending on how the hyperscaler ramp and the Apple transition play out.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.