Qualcomm Could Have a Much Bigger AI Story Than Investors Think
Qualcomm still gets priced like a smartphone supplier, but two hyperscaler custom silicon deals about to generate revenue suggest the market is missing something significant about where this company is actually headed.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

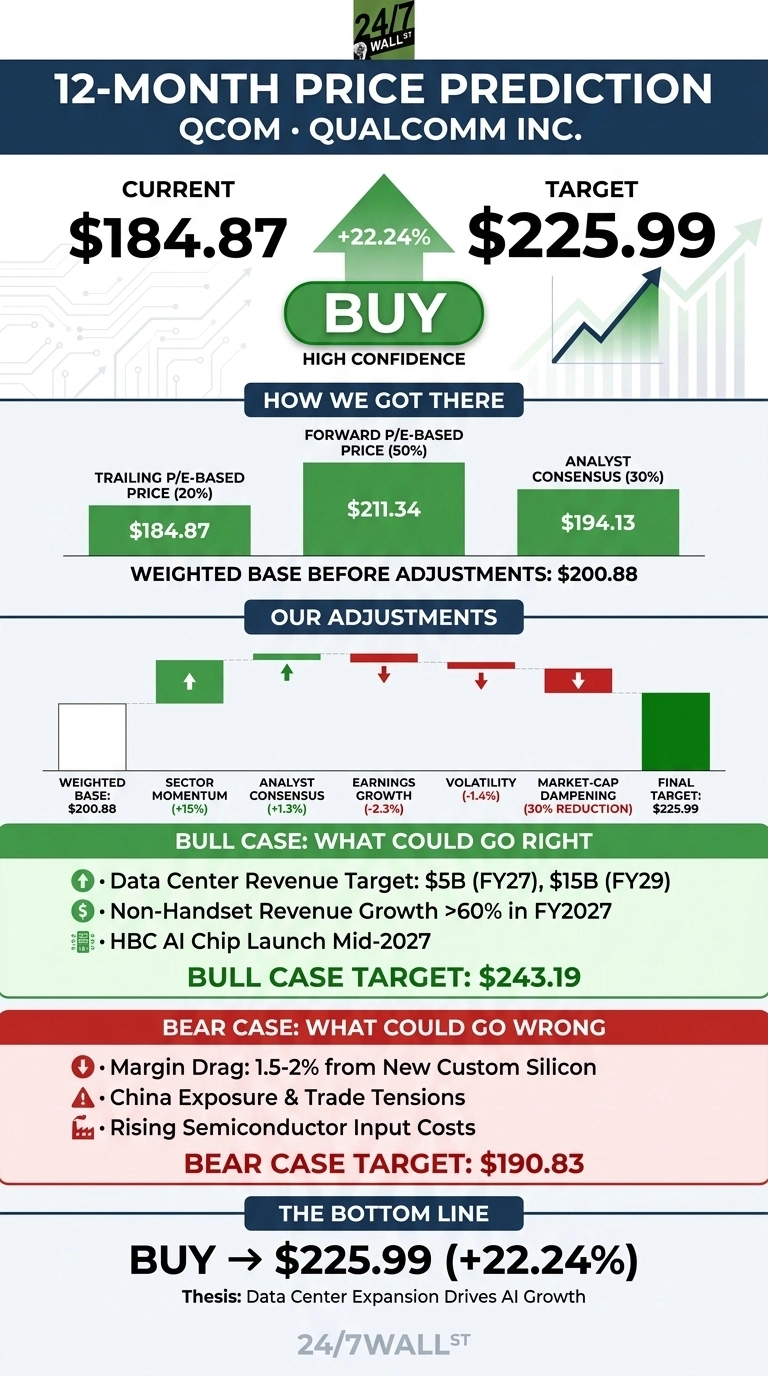
The 24/7 Wall St. price target for Qualcomm (NASDAQ:QCOM | QCOM Price Prediction) is $225.99 over the next 12 months. The target sits 22.24% above the $184.87 close. The stock carries a buy rating with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $184.87 |
| Price Target from 24/7 Wall St. | $225.99 |
| Upside/Downside | 22.24% |
| Recommendation | BUY |
| Confidence Level | 90% |
My thesis: Qualcomm trades at a handset-supplier multiple of 20x forward earnings, yet management guides to $40 billion in non-handset revenue by fiscal 2029, with more than $15 billion from data center. Two hyperscaler custom silicon wins begin generating revenue in the December quarter.

Investor Day Rally Faded, but Momentum Is Rebuilding
Shares fell 8.19% over the past week but are up 9.7% over the past month and 12.13% over the past year. The 52-week range runs from $120.88 to $257.56. The stock rose from $129.39 in mid-March to $220.81 in mid-June, ahead of the June 24 Investor Day.
In fiscal Q3, revenue of $9.95B beat the $9.67B consensus. Non-GAAP EPS of $2.21 just missed the $2.2208 estimate. Handsets dropped 20%. Automotive rose 61% to $1.59B.
Why Bulls See $243 or More
Management expects data center revenue of $5 billion in fiscal 2027, rising to $15 billion in fiscal 2029. Qualcomm has taped out its first high bandwidth compute chip, launching in mid-2027. The Modular acquisition adds an open, hardware-agnostic AI software stack.
CEO Cristiano Amon expects non-handset growth to speed up to “greater than 60% in fiscal 2027″. Automotive is expected to exit fiscal 2026 at an annualized pace of about $7 billion.
Only 11 analysts have a positive rating on the stock, against 23 Holds, leaving room for upgrades. The bull case is $243.19.

Handset Pressure and Margin Drag Could Cap Gains
Operating income fell 41.13% year over year from spending on the Modular deal plus the data center plan. Management expects early custom-chip revenue to cut QCT gross margin by one and a half to 2%.
Risks include China exposure, rising input costs, and customers designing their own chips. Management says a handset recovery could add greater than $1.50 of EPS once markets normalize. The bear case is $190.83.

Qualcomm Trades at a Discount to Custom Silicon Rivals
| Company | Forward P/E | Trailing P/E |
|---|---|---|
| Qualcomm | 20x | 21x |
| Broadcom | 19x | 44x |
| Marvell | 62x | 90x |
Broadcom (NASDAQ:AVGO) is the leading supplier of custom AI chips to hyperscalers, Qualcomm’s target customers. Its forward multiple is close to Qualcomm’s, yet Broadcom posted 85.5% quarterly revenue growth while Qualcomm’s revenue fell 4%. Qualcomm’s data center expansion must deliver to earn a similar rerating.
Marvell (NASDAQ:MRVL) makes custom data center silicon with a market cap of $244.7 billion versus Qualcomm’s $197.45 billion. Investors pay a far higher forward multiple for Marvell’s AI growth. Our target implies about 23x forward earnings, which looks conservative against this peer group.
Qualcomm Price Prediction 2026-2030
The 24/7 Wall St. price target of $225.99 comes with a buy rating and 90% confidence. The deciding factor is the data center expansion.
The bull case improves if custom silicon revenue arrives on schedule in the December quarter. At about 20x forward earnings, the AI upside does not look priced in.
Looking further out, this is where our model projects Qualcomm could trade, assuming current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $197.56 |
| 2027 | $225.99 |
| 2028 | $252.57 |
| 2029 | $298.76 |
| 2030 | $316.58 |
Qualcomm would need to keep executing on its diversification strategy for these projections to hold. Results could move well above or below them depending on hyperscaler adoption of the high bandwidth compute chip and on how quickly handset demand rebounds.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.