Qualcomm Just Locked In Apple. Our Target Sits Above Wall Street’s
Qualcomm just sealed a renewed patent deal with Apple, and the market moved fast. Whether this resets the ceiling for QCOM shares or simply buys time before a bigger reckoning depends on what replaces billions in revenue that could vanish…

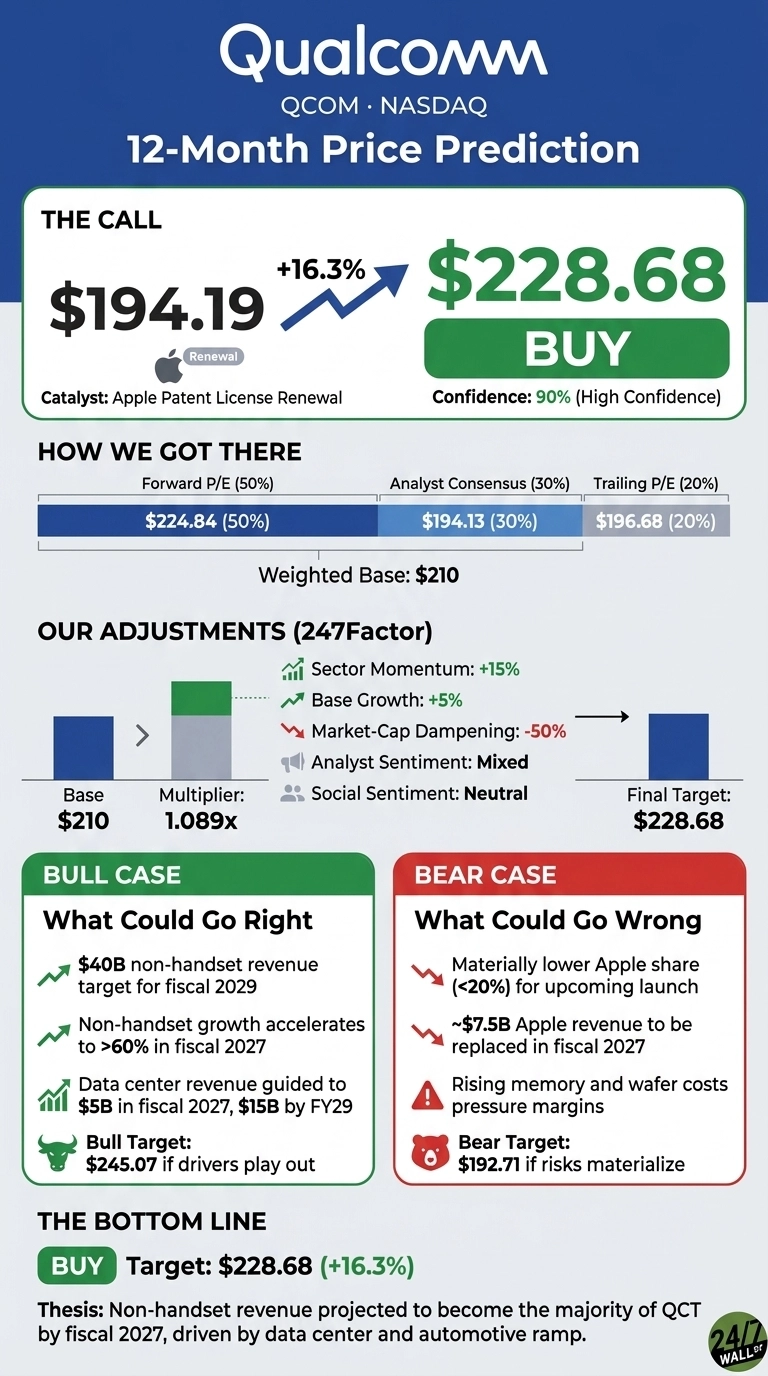
Qualcomm (NASDAQ:QCOM | QCOM Price Prediction) trades near $194.19 with Wall Street’s $194.13 consensus target. Our 24/7 Wall St. price target of $228.68 implies 16.27% upside.
This morning’s renewal of Qualcomm’s Global Patent License Agreement with Apple removes a major long-running overhang. Our model rates QCOM a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $194.19 |
| 24/7 Wall St. Price Target | $228.68 |
| Upside | 16.27% |
| Recommendation | BUY |
| Confidence | 90% |

A Blistering Month for QCOM Shares
Qualcomm shares are up 23.16% over the past month and 15.33% year to date, though below the 52-week high of $257.56.
A multi-generational AI data center collaboration with Amazon announced September 8 and today’s Apple deal fueled the move. Fiscal Q3 revenue of $9.95 billion beat estimates but fell 4% year over year, while non-GAAP EPS of $2.21 missed by a penny. Handsets fell 20% YoY, offset by Automotive up 61% and IoT up 9%.
Why Bulls See a Path to $245
The bull case rests on CEO Cristiano Amon’s raised $40 billion non-handset revenue target for fiscal 2029. Non-handset growth is projected to accelerate from 24% in fiscal 2026 to greater than 60% in fiscal 2027.
Data center is guided to $5 billion in fiscal 2027 and $15 billion by fiscal 2029, powered by two hyperscaler custom-silicon wins with POs in hand. Automotive is lifted to a $7 billion annualized run rate. Our bull scenario puts QCOM at $245.07, or 24.6% upside.

What Could Send QCOM Back to $192
The bear case: Apple is taking materially lower than 20% share in the upcoming iPhone launch, with roughly a 50% sequential decline in Apple revenue into the December quarter. About $7.5 billion of Apple revenue must be replaced in fiscal 2027.
Rising memory and wafer costs, plus 1.5% to 2% gross-margin drag from early data-center silicon, add execution risk. Management flagged greater than $1.50 of EPS as a normalization tailwind once the cycle turns. Our bear scenario: $192.71.

How Qualcomm Compares to Broadcom, NXP, and Marvell
Broadcom (NASDAQ:AVGO) is the closest large-cap analog with overlapping Apple wireless exposure and custom-silicon data-center leadership. AVGO trades at 19x forward earnings on 86% YoY revenue growth. QCOM’s forward multiple looks inexpensive if the diversification thesis lands.
NXP Semiconductors (NASDAQ:NXPI) is the auto-semi anchor. NXPI trades at 13x forward earnings on 20% revenue growth. QCOM’s premium is justified by 61% auto growth.
Marvell Technology (NASDAQ:MRVL) is the pure-play hyperscaler custom-silicon peer at 63x forward earnings. If Marvell’s multiple is directionally right, QCOM’s data-center ramp is barely priced in.
Why Qualcomm Looks Attractive Here
Our 24/7 Wall St. price target is $228.68, a buy with 90% confidence. Non-handset revenue is projected to become the majority of QCT by fiscal 2027.
The thesis rests on the two hyperscaler custom-silicon wins converting to real December-quarter revenue as guided, part of the broader AI data-center buildout we mapped across seven non-chipmaker suppliers in a free report here.
The primary risk is memory costs compressing margins without offsetting volume growth. On balance, risk/reward skews positive. Looking further ahead, here is where our model projects QCOM could trade in the coming years, assuming current growth trajectories hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $202.89 |
| 2027 | $230.33 |
| 2028 | $254.24 |
| 2029 | $282.74 |
| 2030 | $297.47 |
These projections assume Qualcomm continues executing on its data center and automotive ramp. Meaningful upside or downside could result from faster hyperscaler adoption or a prolonged handset downturn.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.