McDonald’s Is Now a Dividend King. Here’s Why One Investor Calls It a Generational Compounder

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
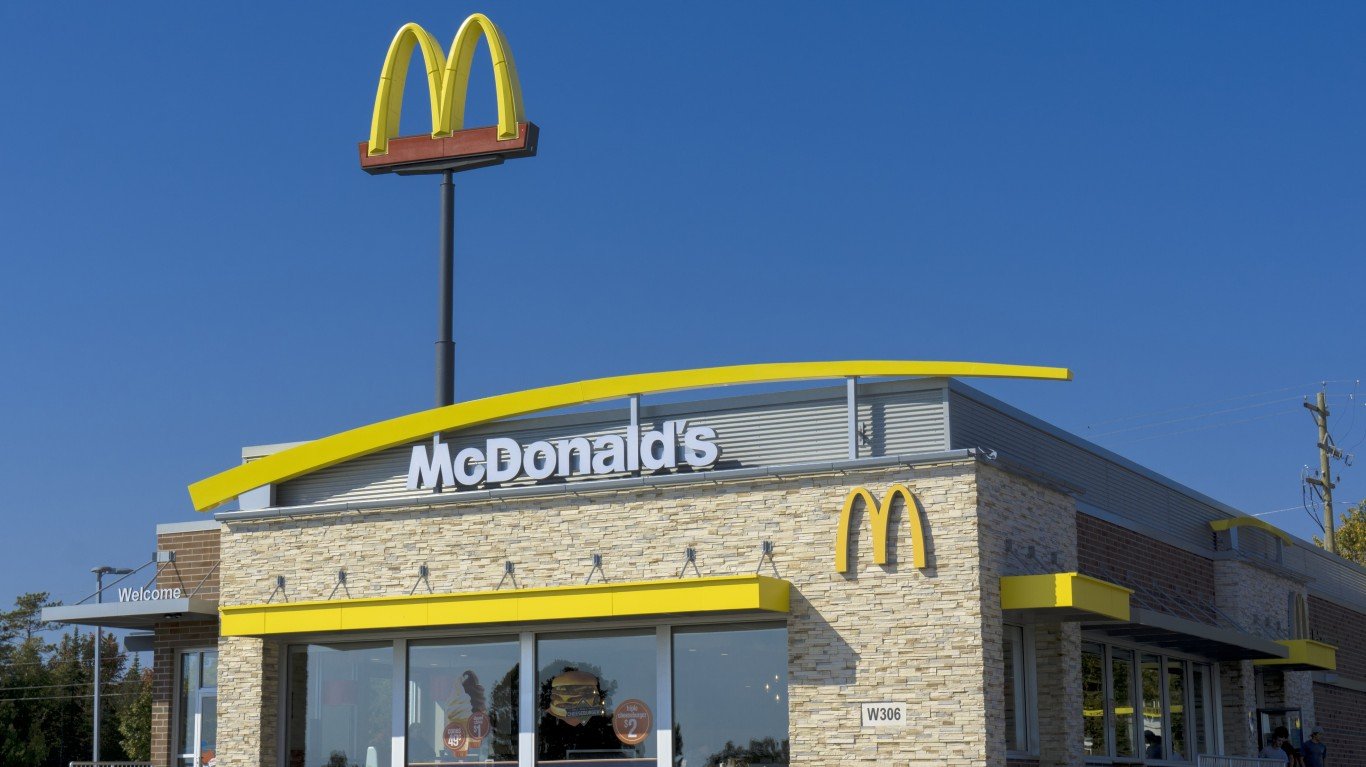
McDonald’s (NYSE:MCD | MCD Price Prediction) is now a Dividend King. In September, it raised its quarterly payout to $1.93 per share. On an episode of The Investor’s Podcast titled “TIP858: McDonald’s ($MCD): Generational Compounder in Historical Drawdown,” published November 5, co-host Daniel Mahncke pointed out that the company had raised its dividend for the 50th consecutive year, every year since 1976.
Mahncke said the dividend now comes to $7.72 a year, a yield of about 3.3%, which he called the highest since 2020. That yield has already come down. Shares rose 19.87% over the past month to $281.96, so the forward yield is now about 2.74%. The stock is still down 5.94% for the year.

How a Burger Chain Became a Landlord
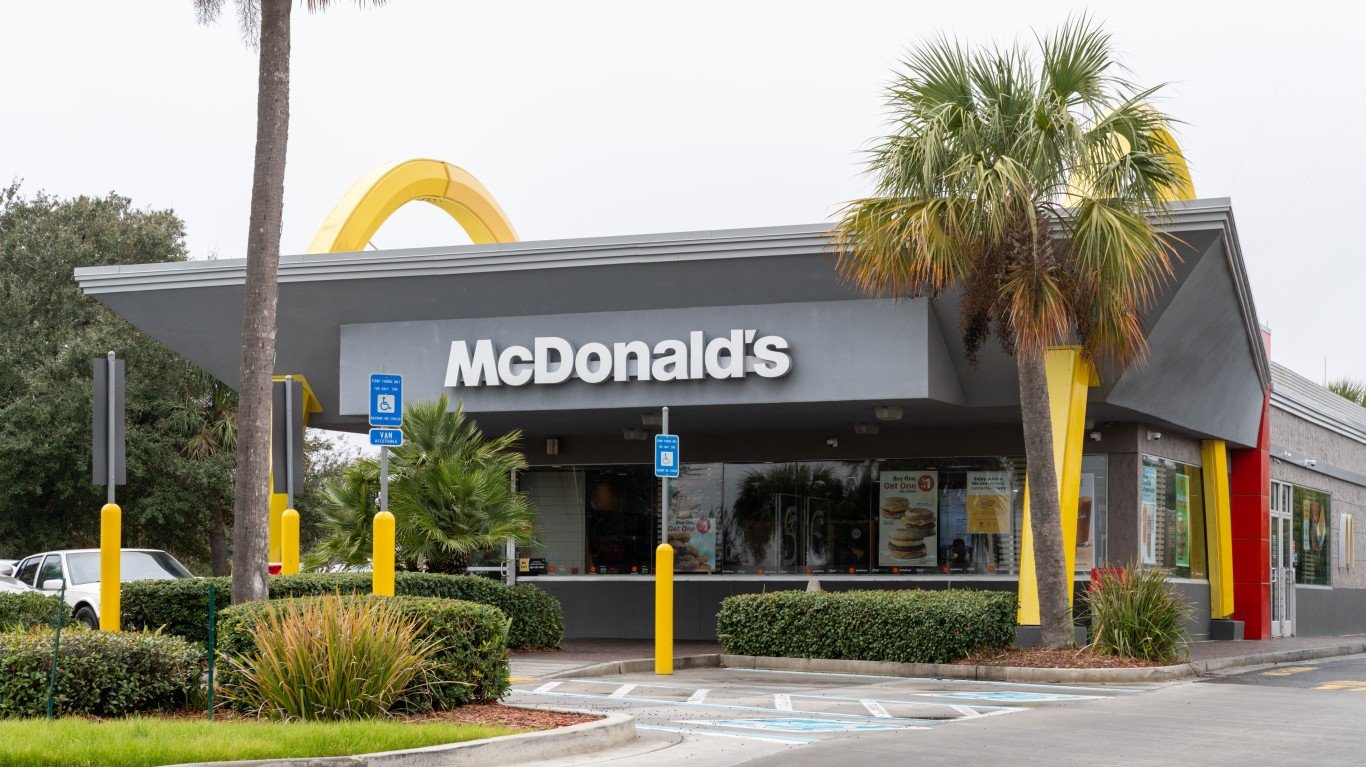
Independent franchisees run about 95% of McDonald’s restaurants. On its November 4 call, management said it remains on track to be 98% franchised by 2028. Franchisees pay McDonald’s rent plus royalties tied to their sales. That fee income supports an operating margin of about 46.1%, which is rare for a restaurant company.
Mahncke thinks the real estate holds the hidden value. He noted that the properties are carried on the balance sheet at about $28 billion, largely from purchases made in the 1960s and 1970s. He cited outside estimates valuing the real estate alone at nearly $120 billion. He added a caution: franchisees have to keep making money, or they close and stop paying rent.
Buybacks Quietly Shrink the Share Count
Mahncke also said McDonald’s bought back $2.1 billion of stock last year and, counting the dividend, returned essentially 100% of its free cash flow. The company’s full-year 2025 filing shows free cash flow of $7.186 billion and buybacks of 6.7 million shares for $2.056 billion. Diluted shares dropped to 708.3 million in the third quarter from 715.9 million a year earlier, so each remaining share gets a bigger piece of the royalty stream. The dividend record shows the long-run result: $0.375 per quarterly payment in 2008, compared with $1.93 for the payment due December 15.
Bear Case Mahncke Takes Seriously
Mahnke’s valuation is conservative. When he recorded the episode, he put fair value near $220 per share, using a 20x exit multiple. That implies about 10% total returns including dividends. The stock now trades above his estimate, at a P/E of about 23. He also named GLP-1 weight-loss drugs as a possible terminal risk that keeps his confidence in check.

Interest rates are the second risk. Mahncke said McDonald’s has traded like an inverted 10-year Treasury. Higher rates lower the value of its real estate, and they give income investors a risk-free bond paying well over 5%. The company also carries about $40 billion of long-term debt, mostly at fixed rates. Years of buybacks have pushed shareholders’ equity negative, to -$1.791 billion at the end of 2025.
The third risk is the consumer. “This is really a consumer story. When gas prices are this high, people don’t have money to go out to eat,” Kevin Simpson said on CNBC’s Halftime Report in September. U.S. comparable sales slipped 0.2% in the third quarter.

What to Watch Into 2027
McDonald’s is testing entry-level value bundles in about 1,900 restaurants and plans to launch a new national value program in early 2027. It is also preparing for mid-single-digit food and paper inflation next year. Starting in 2028, it plans to remodel more than 5,000 restaurants per year. Shareholders of record on December 1 will get the first payment at the higher rate. The compounder case depends on the value program bringing U.S. traffic back while rates stay manageable. McDonald’s posts updates on its investor relations site. For background on the decline, see our earlier analysis, McDonald’s Is Near a 52-Week Low. Is This the Contrarian Buy of 2026?
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.