Prediction: The AI Stock Wall Street Could Be Underestimating for 2027

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Credo Technology (NASDAQ:CRDO | CRDO Price Prediction) makes the connections that keep AI clusters running. Active Electrical Cables (AECs) are still its biggest business, but Chief Executive Bill Brennan says the portfolio now reaches “from millimeters to kilometers, with solutions across optics and copper.”
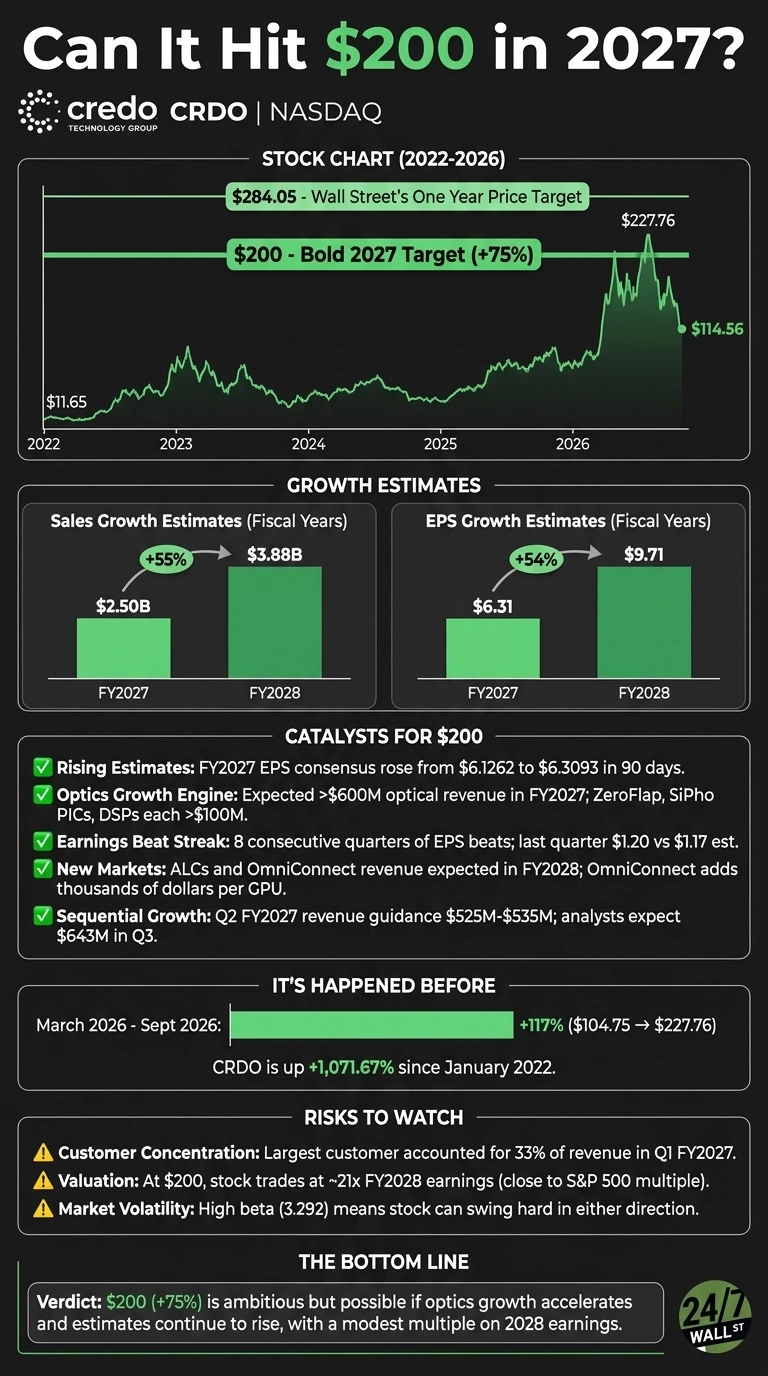
The stock hasn’t kept pace with the business. Shares dropped 16.08% today to $114.56. That came after a 35.76% drop over the month ending November 4. Here’s what Credo needs to do to reach $200 in 2027.

Analysts See Far More Upside Than the Market Is Pricing In
Wall Street’s average price target of $284.05 implies about 148% upside. Of the analysts covering the stock, 5 rate it Strong Buy, 14 rate it Buy and only 1 rates it Hold. Their EPS estimates are also rising.
Over the past 90 days, the fiscal 2027 consensus went from $6.1262 to $6.3093, and the fiscal 2028 consensus went from $9.0759 to $9.7121. Analysts expect revenue to reach $3.88 billion in fiscal 2028.

Here’s What It Takes for Credo to Reach $200
At today’s price, Credo trades at about 18x fiscal 2027 earnings and 12x fiscal 2028 earnings. At $200, the fiscal 2028 multiple would be roughly 21x. That’s close to the S&P 500’s forward multiple of around 21x to 23x, even though management expects more than 85% revenue growth in fiscal 2027 and a non-GAAP net margin near 50%.
What Could Push Credo to $200?
- Earnings beat streak: Credo has beaten EPS estimates for 8 consecutive quarters. Last quarter it posted $1.20, beating the $1.17 estimate.
- Optics growth: Management expects more than $600 million in optical revenue in fiscal 2027. It expects ZeroFlap optics, silicon photonics PICs and optical DSPs to each bring in over $100 million. In Brennan’s words, “AECs continue to grow, optics is growing faster.”
- Sequential growth: Second-quarter guidance calls for $525 million to $535 million in revenue. Analysts expect $643 million the following quarter.
- New markets: Revenue from Active LED Cables (ALCs) and OmniConnect is expected to start in fiscal 2028. Management says OmniConnect could add “thousands of dollars of Credo content per GPU.”

Credo Has Doubled in Six Months Before
Reaching $200 would take a gain of about 75%. Credo has done more than that recently. Shares rose from $104.75 in March 2026 to $227.76 in September, a gain of 117%.
Since January 2022, the stock is up 1,071.67%. Over the past 52 weeks it has traded between $86.48 and $308.67. With a beta of 3.292, it can swing hard in either direction.

$200 Is a Stretch, but Here’s Why It’s Possible
Customer concentration is the main risk. The company’s biggest customer accounted for 33% of revenue last quarter. Still, estimates keep rising, Credo keeps beating them, and optics is becoming a second growth engine.
Credo isn’t a chipmaker, it’s one of the connectivity suppliers quietly powering the AI data-center expansion (we profiled seven companies in that same category, covering everything from electricity and thermal management to networking, in a free report you can grab here).
At $200, the stock would still trade at a modest multiple on fiscal 2028 earnings. This is the plan for how Credo could post outsized gains in 2027, though such gains in one year are rare.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.