Credo Has One Number That Could Change the Stock’s Long-Term Story
Credo Technology just posted its seventh consecutive quarter of triple-digit revenue growth, yet analysts still set targets well below where this volatile stock has already traded. One specific milestone in its optical business could force a dramatic rethink of where…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Credo Technology (NASDAQ:CRDO | CRDO Price Prediction) sells the connectivity that keeps AI clusters talking. Its lineup covers active electrical cables, optical DSPs, retimers and now silicon photonics. Revenue hit a record $479 million last quarter, up 115% year over year.
Shares are up 54.22% year to date but still trade well below the $308.67 52-week high. One number could change the long-term story: more than $600 million of optical revenue in fiscal 2027. So can Credo hit $350 in 2027?

What’s Holding Credo Back Right Now
The biggest risk is volatility: Credo carries a beta of 3.228. Shares traded at $282.82 in mid-August and fell to $161.49 by mid-September, though recent gains of +13.24% week-over-week show a rebound.
GAAP gross margin slipped to 64.5% from 68.2% sequentially due to acquisition amortization. Goodwill jumped to $986.4 million. The largest customer accounted for 33% of revenue and the second-largest for 28%. Inventory rose to $313.1 million, and share-based compensation reached $87.98 million.
Analysts Are Bullish, but Their Targets Trail the Estimates
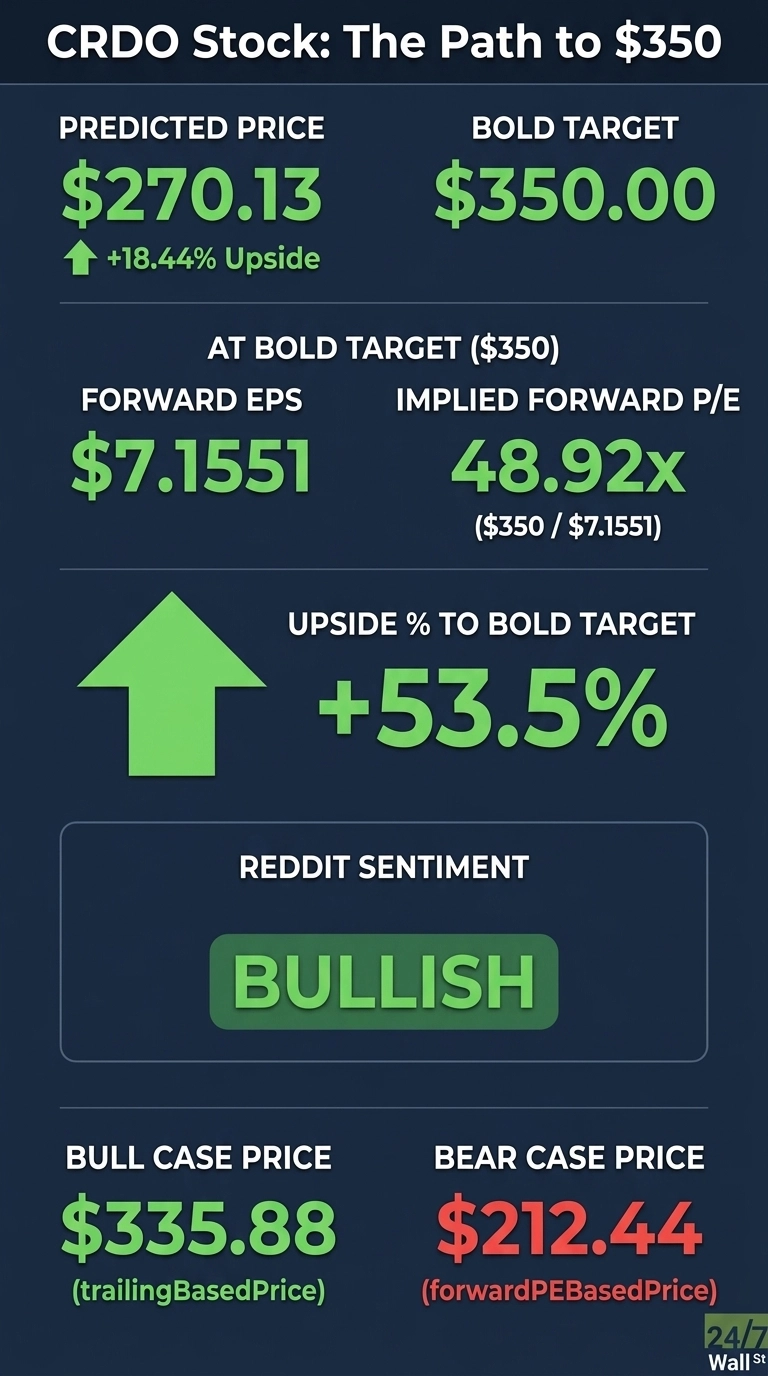
The consensus target is $281.09. The stock carries 4 Strong Buy, 14 Buy, 1 Hold, plus 0 Sell ratings from analysts. The model’s base case is $270.13, or 18.44% upside. The scenario range runs from a bear case of $212.44 to a bull case of $335.88. Model confidence is high, at 0.9 on a 1.0 scale.

The fiscal 2028 EPS estimate has rose to $9.7049 from $8.8475 90 days ago. Over the last 30 days there were 14 upward revisions and 1 downward. Analyst sentiment is 95% bullish, yet the model may be underweighting the optical ramp.
Here’s What It Takes for Credo to Reach $350
A climb to $350 from $228.07 means a gain of 53.5%.
Given forward EPS of $7.1551, $350 amounts to a significantly higher forward multiple than the base case of $270.13, calling for additional multiple expansion.
That expansion is justified because management expects fiscal 2027 revenue growth above 85% and a non-GAAP net margin “in the vicinity of 50%”. Zero-flap optics, silicon photonics PICs and optical DSPs are each expected to top $100 million.
CEO Bill Brennan said: “Fiscal 27, I think, is just a stepping stone for where we’re going with our optical business.” OmniConnect could add “thousands of dollars of Credo content per GPU” starting in fiscal 2028.

A slowdown in hyperscaler capex poses the biggest risk, landing hard on a business where three to four customers each make up more than 10% of revenue.
The flip side is that the same expansion is lifting a whole bench of suppliers beyond the chipmakers (we covered seven of them, from power to cooling to networking, in a free report).
Where Credo Trades Today vs Its Earnings Power
At $228.07, Credo’s forward multiple is reasonable for a company posting its seventh consecutive quarter of triple-digit growth. The stock is trading between its 52-week low of $86.48 and a high of $308.67.
Since January 2022, the stock has gained 1,804.81%. If the optical business delivers, today’s multiple leaves room for the rerating the bull case depends on.
$350 Is a Stretch, but Here’s Why It’s Possible
Hitting $350 requires a 53.5% gain. It’s a stretch, but within reach for a stock this volatile.
Optical revenue must clear $600 million, the first 1.6T DSP revenue must arrive on schedule, and Q2 revenue must meet the $525 million to $535 million guidance. A sharp cut in AI infrastructure spending would undermine the thesis. We’ve outlined the blueprint for how Credo could reach $350 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.