Price Prediction: This Stock Could Double by 2027
Credo Technology just posted triple-digit revenue growth for the eighth quarter in a row, yet the stock sits more than 30% below its 52-week high. Whether that gap is a buying opportunity or a warning sign depends on two product…

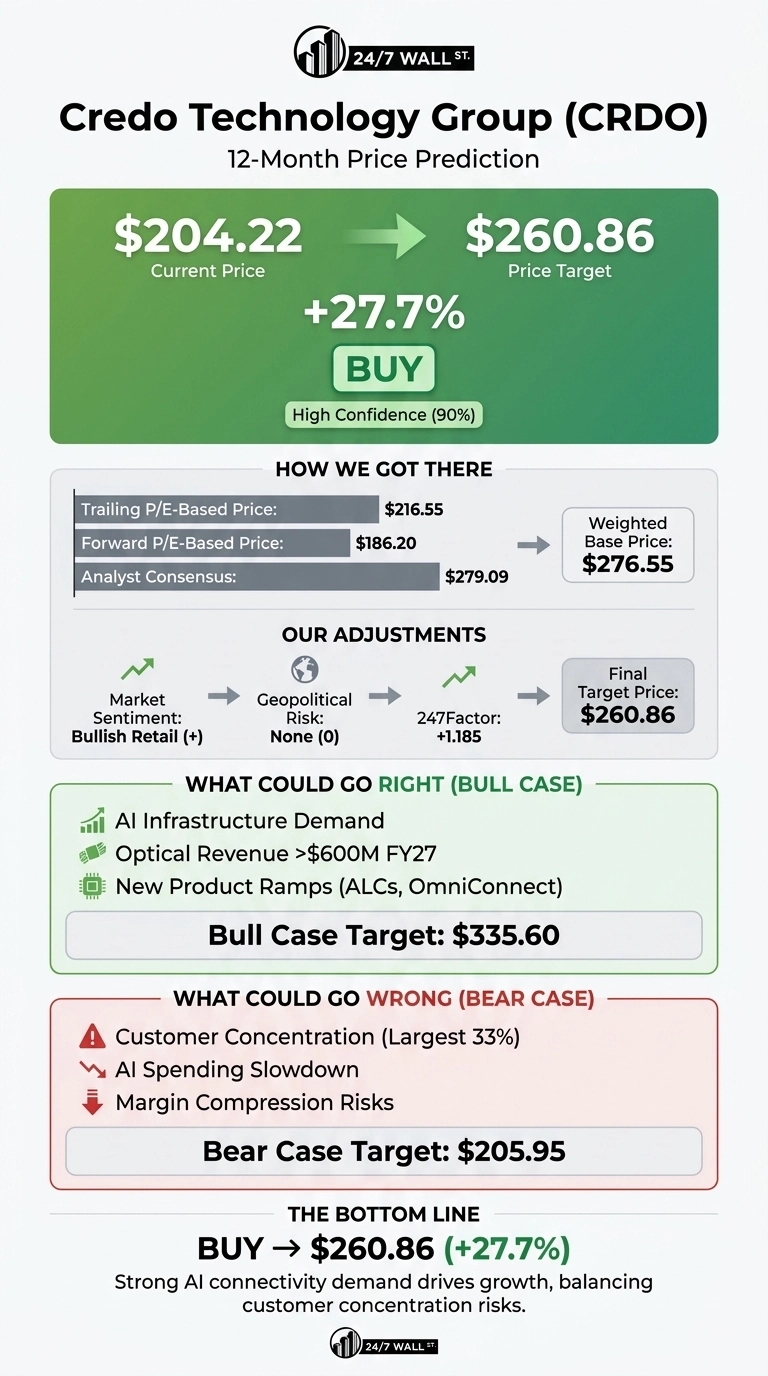
Our 24/7 Wall St. price target for Credo Technology (NASDAQ:CRDO | CRDO Price Prediction) is $260.86 over the next 12 months. That points to meaningful upside from today’s price, and our model rates the stock a buy.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $204.22 |
| Price Target from 24/7 Wall St. | $260.86 |
| Upside | 27.7% |
| Recommendation | BUY |
| Confidence Level | 90% |
Shares were down 5.69% by noon Monday, and that pullback widens the gap to our target. Our confidence is high because Credo continues beating estimates and guiding higher.
Doubling from here would mean reaching $408.44. Getting there by 2027 would take our bull scenario and then some. Our model’s five-year bull path does cross that level by October 2028.

A Volatile Rally Built on Triple-Digit Growth
Credo is up 41.93% year to date and 21.62% over the past month. It has also slipped 6.6% in the past week. The stock sits 33.8% below its 52-week high of $308.67 and 136.1% above its low of $86.48.
In fiscal Q1 2027, revenue rose 114.73% to $479 million, beating the $470.38 million consensus. Non-GAAP EPS came in at $1.20 against estimates of $1.1651, which makes eight consecutive beats. Management guided Q2 revenue to $525 million to $535 million and expects fiscal 2027 growth of more than 85%.

Why Bulls See $335 and Beyond
The bull case reaches $335.60, or 64.3% upside. Optics is the biggest driver. Management expects optical revenue above $600 million in fiscal 2027, with ZeroFlap optics, silicon photonics chips and optical DSPs each exceeding $100 million. Active LED cables (ALCs) and OmniConnect memory products are due to start contributing in fiscal 2028.
Credo says OmniConnect could add “thousands of dollars of Credo content per GPU”. Analysts are firmly on board, with 5 Strong Buy ratings, 14 Buy ratings and a consensus target of $279.09.

Concentration and Margin Risks to Keep an Eye On
Our bear case comes out at $205.95, about where the stock trades now. Customer concentration is the biggest risk. Credo’s largest customer accounted for 33% of Q1 revenue, and the second-largest added 28%.
GAAP gross margin go down to 64.5% from 68.2%, and share-based compensation reached $87.98 million. Part of that margin fall came from amortizing intangible assets tied to an acquisition, a non-cash accounting charge. Non-GAAP gross margin held at 68%.

Credo Grows Faster Than Marvell and Costs Less Than Astera
Marvell Technology (NASDAQ:MRVL) sells optics and connectivity products into the same AI data center buildout. Its revenue rose 36.55% last quarter, with a non-GAAP gross margin of 58.9%. Credo rose faster and earned higher margins, which supports a premium valuation.
Astera Labs (NASDAQ:ALAB) is the closest match on growth, with revenue up 104.5%. Shares are valued at about 271x trailing earnings. Credo trades at about 30x forward earnings, so our target looks reasonable, and arguably conservative, by comparison.
| Company | Latest Revenue Growth | Market Cap |
|---|---|---|
| Credo | 114.73% | $38.38B |
| Marvell | 36.55% | $233.8B |
| Astera Labs | 104.5% | $57.5B |
Credo Earns a Buy Rating at $204
The 24/7 Wall St. price target of $260.86 carries a buy rating and 90% confidence. Credo matches fast growth with a modest forward multiple.
The bull case improves if the optical ramp lands in the second half of fiscal 2027. The outlook weakens if one of Credo’s largest customers cuts orders.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $220.00 |
| 2027 | $261.89 |
| 2028 | $296.25 |
| 2029 | $327.60 |
| 2030 | $342.10 |
These figures assume Credo continues executing its current strategy. The biggest key factors are how fast ALC and OmniConnect sales ramp in either direction, and any slowdown in AI infrastructure spending.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.