This Magnificent Seven Stock Could Turn $10,000 Into $20,000 by 2027
One Magnificent Seven stock is quietly building a case that its biggest gains still lie ahead, and the math behind a potential doubling of your investment by 2027 is harder to dismiss than you might expect.

If you are looking for the Magnificent Seven name most likely to double a $10,000 stake by 2027, our proprietary model points squarely at NVIDIA (NASDAQ:NVDA | NVDA Price Prediction).
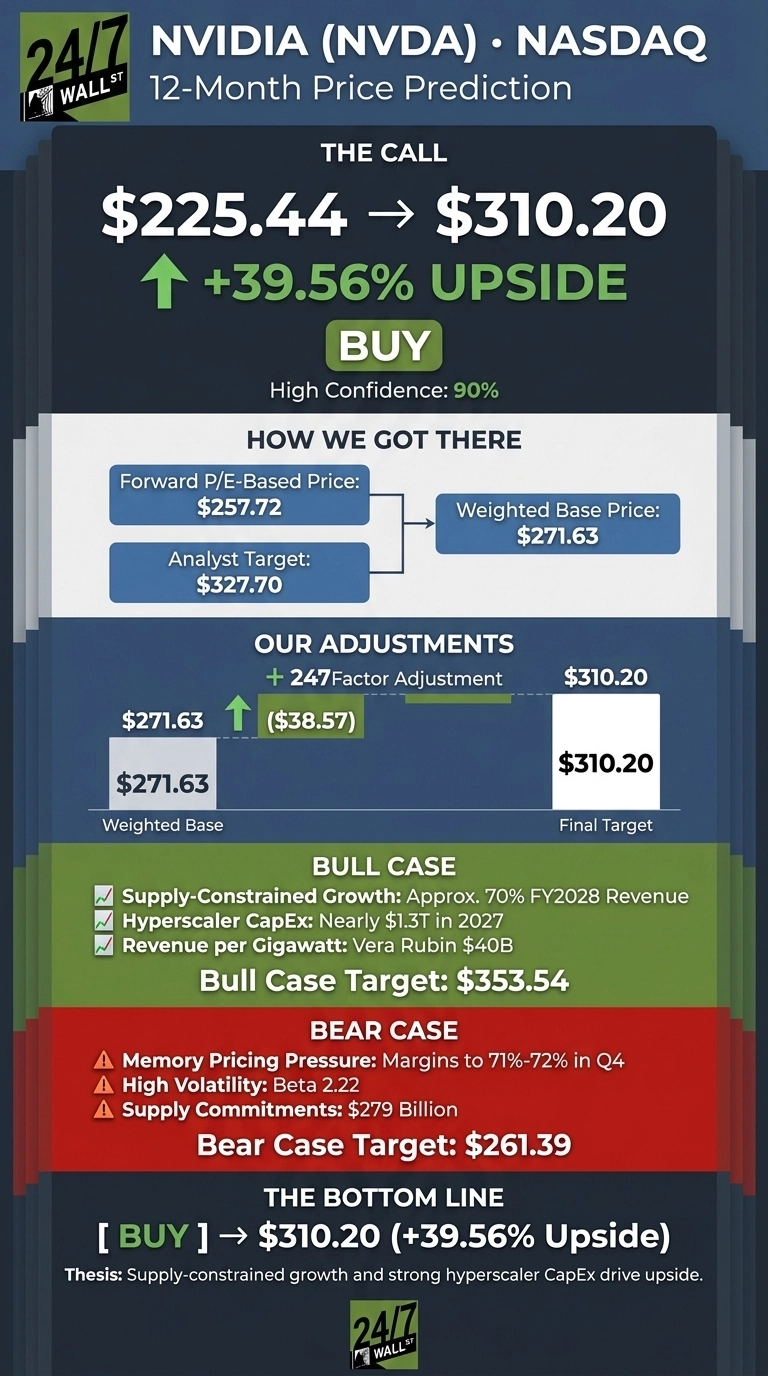
The chip designer trades at $225.44, and our 24/7 Wall St. price target for NVIDIA is $310.20, implying 39.56% of upside over the next 12 months. The recommendation is buy, and model confidence is high at 0.9.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $225.44 |
| 24/7 Wall St. Price Target | $310.20 |
| Upside | 39.56% |
| Recommendation | BUY |
| Confidence | 90% |

Blackwell Ultra, Vera Rubin, and a Stock That Keeps Grinding Higher
NVIDIA is up 3.28% over the past week, 21.16% year to date, and 28.22% over the past year.
The Q2 FY2027 report on August 26, 2026 delivered revenue of $96.221 billion, up 105.85% year over year, with non-GAAP EPS of $2.22 beating the $2.0887 consensus. Data Center revenue reached $89.023 billion, up 117%.
Management guided Q3 revenue to $108 billion, plus or minus 2%, excluding China Data Center compute. Reports of renewed Trump-Xi talks around AI chip policy could reopen that market as an upside kicker.

Why Bulls See a Breakout Ahead
Demand still exceeds supply. Jensen Huang told analysts NVIDIA expects fiscal 2028 revenue to grow “approximately 70%”, describing the outlook as “supply-constrained“.
Top-five hyperscaler CapEx is projected at nearly $800 billion in 2026 and $1.3 trillion in 2027. Revenue per gigawatt has scaled from $18 billion with Hopper to $40 billion with Vera Rubin. The bull-case one-year target is $353.54, a 59.06% return. Analyst consensus of $327.70 from 57 buy ratings sits between base and bull cases.

What Could Go Wrong
Memory pricing is a headwind. Management flagged “extreme pricing conditions in memory” and expects gross margins to bottom in the 71% to 72% range in Q4. Supply commitments reached $279 billion, with guarantee obligations of $108.5 billion for AI cloud partners.
Beta of 2.22 means AI CapEx wobbles hit NVDA harder. The bear-case one-year target is $261.39. Bulls counter that Huang’s nearly $50 billion in Frontier AI Lab investments and the $500 billion financing platform with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs, and KKR are structural demand accelerants.

How NVIDIA Compares to AMD, Broadcom, and Microsoft
Advanced Micro Devices (NASDAQ:AMD) is the direct GPU competitor. Q2 2026 Data Center revenue of $6.718 billion grew 107%, but AMD trades at a trailing P/E near 211 versus NVDA’s 45. NVIDIA looks cheap for a company earning a 55.60% net margin.
Broadcom (NASDAQ:AVGO) is the custom-silicon threat. AI semiconductor revenue reached $16.70 billion in Q3 FY2026, up 221%, with Q4 guided to $21.70 billion. Growth is faster off a smaller base, but NVIDIA’s Data Center scale exceeds Broadcom’s by more than four times, justifying the premium.
Microsoft (NASDAQ:MSFT) is the largest customer and cleanest demand proxy. FY2026 CapEx of $115.95 billion and commercial RPO of $678 billion validate NVIDIA’s supply-constrained thesis. MSFT trades at a P/E of 27, reinforcing that NVIDIA’s multiple is reasonable given its growth.
NVIDIA Price Prediction 2026-2030
Our 24/7 Wall St. price target for NVIDIA is $310.20, a buy with 90% confidence. The key factor is Huang’s supply-constrained 70% growth outlook for FY2028.
The bull thesis holds if hyperscaler CapEx guides hold into 2027. The thesis weakens if memory pricing forces gross margin below 70% or if China policy removes an upside catalyst.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $244.55 |
| 2027 | $312.33 |
| 2028 | $380.37 |
| 2029 | $447.65 |
| 2030 | $535.98 |
These projections assume NVIDIA executes on Vera Rubin and successor platforms. Upside or downside could result from China market access or a broader AI CapEx reset. For readers hunting the next name with this kind of setup, we reverse-engineered what the biggest tech winners looked like early in a free playbook you can grab here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.