Procter & Gamble Has Raised Its Dividend for 70 Straight Years. Where’s the Price Target Now?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

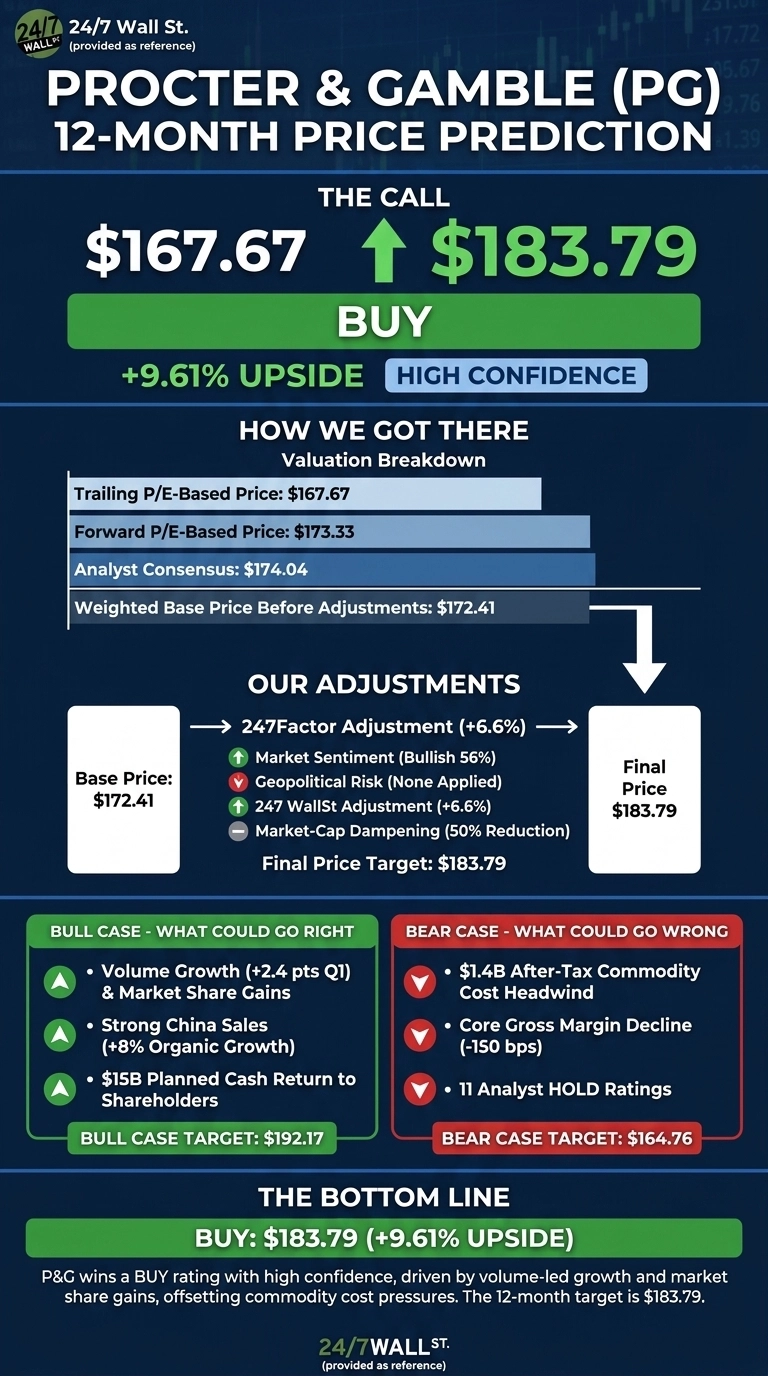
Procter & Gamble (NYSE:PG | PG Price Prediction) closed at $167.67 on November 11. The 24/7 Wall St. price target for P&G is $183.79 over the next 12 months, meaning 9.61% upside. The stock wins a buy rating from the model, and our confidence is high.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $167.67 |
| Price Target from 24/7 Wall St. | $183.79 |
| Upside/Downside | 9.61% |
| Recommendation | BUY |
| Confidence Level | 90% |

Our target sits above the consensus analyst target of $174.04.
P&G pays investors while they wait: 70 straight years of dividend increases (a run that puts it in rare company, the same club we ranked by valuation in a free Dividend Kings report), 136 consecutive years of payments, and a forward dividend of $4.354 per share, which works out to roughly a 2.6% yield. Its beta of 0.36 marks P&G as one of the steadiest mega-caps in the market.

October Earnings Beat Pushes P&G Toward Its 52-Week High
Shares have gained 10.19% over the past month and 20.37% year to date, though they were nearly flat over the past week (0.21%). That leaves the stock about 1.7% below its 52-week high of $170.52 and roughly 25.4% off its low of $133.74.
The quarter that drove the rally was fiscal Q1 2027. Core EPS came in at $2 against a consensus of $1.89, and net sales of $23.276 billion exceeded the $22.817 billion estimate. Organic sales rose 4%, which is above the full-year guidance range, and all five segments grew. P&G also closed its acquisition of Thorne on October 1, 2026 and has an Investor Day set for November 19.

Why Bulls See $192 Ahead
In our bull scenario, the stock hits $192.17. Growth is coming mostly from volume, which added 2.4 points last quarter. More than 70% of top U.S. customers are now holding or growing share, up from less than 10% in the first half of fiscal 2026.
Organic sales in Greater China rose 8%, and management projects that the Pampers Amore launch will top $100 million in first-year sales. P&G plans to return $15 billion to shareholders this fiscal year. Among analysts, 5 rate the stock Strong Buy and 9 rate it Buy.

Commodity Costs Are the Biggest Threat
Our bear scenario lands at $164.76. Management expects about $1.4 billion in after-tax input-cost pressures. That estimate assumes Brent oil at $100 a barrel, and below-the-line items push the total impact to 79 cents per share. Core gross margin fell 150 bps, and 11 analysts rate the stock Hold.
To offset the cost pressure, P&G delivered $2.8 billion of productivity savings last fiscal year and plans to raise prices alongside new product launches. Free cash flow rose 12.74% in fiscal 2026.
How P&G Compares to Colgate-Palmolive and Kimberly-Clark
Colgate-Palmolive (NYSE:CL) competes directly with P&G in oral care. It trades at the same forward multiple (24), but its Q3 organic growth of 3.6% trailed P&G’s.
Kimberly-Clark (NASDAQ:KMB) competes with Pampers and Charmin. It trades at 15 times forward earnings, but its organic sales fell 1.3%, and it took on more debt with the Kenvue deal. Next to these peers, our target looks reasonable.
| Company | Forward P/E | Dividend Yield |
|---|---|---|
| P&G | 24 | 2.6% |
| Colgate-Palmolive | 24 | 2.14% |
| Kimberly-Clark | 15 | 4.56% |
Volume-Led Growth Keeps P&G a BUY
The 24/7 Wall St. price target of $183.79 looks wins. P&G wins a buy rating from the model at 90% confidence, with market-share gains driven by volume making the difference the scale.
Things look firmer if Investor Day shows that pricing can offset commodity inflation. It weakens if oil stays high and margins keep shrinking.
Our model projects P&G could trade at these levels if its current growth path holds:
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $168.63 |
| 2027 | $183.79 |
| 2028 | $195.74 |
| 2029 | $208.47 |
| 2030 | $222.03 |
P&G would need to keep executing on its current strategy for these projections to hold. A sustained spike in commodity costs or a faster recovery in margins could move results well away from this path.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.