This Dividend King Still Has Plenty of Room to Grow
Procter and Gamble just delivered five straight earnings beats while its stock quietly lagged the market, and now a specific corner of its portfolio is flashing signals that bulls say the setup for fiscal 2027 looks nothing like the headlines.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
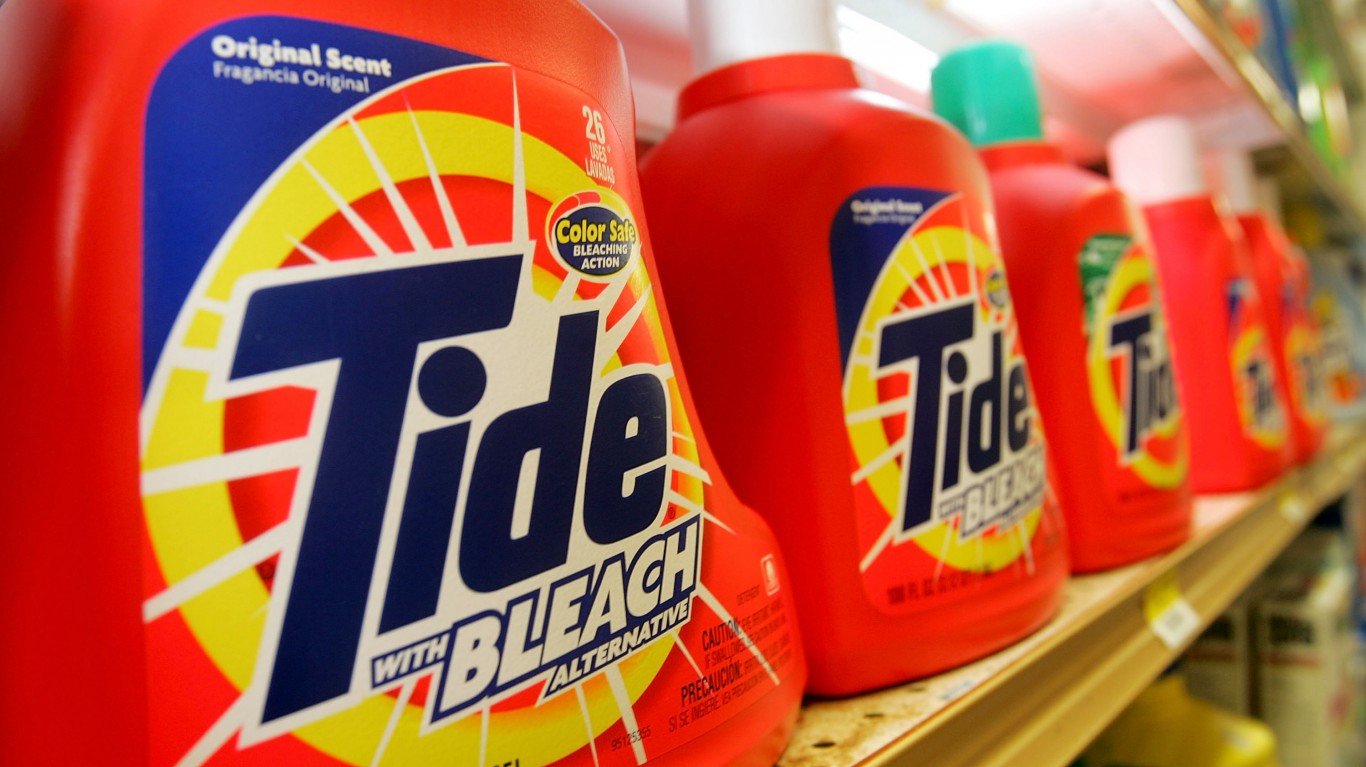
Procter & Gamble (NYSE:PG | PG Price Prediction) sits at a crossroads familiar to every Dividend King: prove the model still has legs, or watch capital rotate to faster growers. After a foundation-building fiscal 2026 that delivered five straight EPS beats but only flat organic sales in Q4, the setup into fiscal 2027 looks better than the headlines suggest.
P&G trades at $146.10 as of July 29, 2026. Our 24/7 Wall St. price target is $164.75, implying 12.77% upside over the next 12 months. That earns a buy rating with a 90% confidence score, our highest tier.

| Metric | Value |
|---|---|
| Current Price | $146.10 |
| 24/7 Wall St. Price Target | $164.75 |
| Upside | 12.77% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Year of Foundation Building
The stock is down 4% over the last year and off 1.31% this past week, but up 4.18% year to date. Q4 FY2026 delivered core EPS of $1.43 against a $1.407 estimate, with full-year revenue of $87.03 billion and full-year core EPS of $6.89.
Free cash flow expanded 12.74% to $15.84 billion, which matters because CEO Shailesh Jejurikar committed to $10 billion in dividends and $5 billion in buybacks in FY27, funded by operating cash flow.

Why Bulls See a Breakout Ahead
The bull case rests on Beauty, which grew 6% organically in Q4 and posted 11% growth in Q3, driven by SK-II premium mix and Hair Care innovation. Jejurikar told investors P&G is “inventing the CPG company of the future” through Supply Chain 3.0 and AI-enabled molecular discovery.
The bull scenario points to $173.99 (a 19.09% return) if user-growth initiatives reaccelerate volume and productivity savings (Q4 hit 460 bps) fully offset tariff drag.

The Risks Worth Watching
FY27 carries a $1 billion after-tax commodity, energy and transport headwind plus $0.56 per share drag from tariffs, interest and FX. Baby, Feminine & Family Care declined 1% in Q4 and Greater China volumes remain soft in Skin Care and Oral Care.
A recently resolved Polymarket contract showed the crowd underestimated Q4 weakness. Bulls counter that the SG&A surge of 160 bps reflects marketing reinvestment aimed at funding user growth. The bear scenario floors at $151.67, still a 3.81% gain with dividends.

How P&G Compares to Colgate and Kimberly-Clark
Colgate-Palmolive (NYSE:CL) is the cleanest direct comp on oral and personal care. Colgate trades at a forward P/E of 24 with a 2.26% dividend yield, but its most recent quarterly earnings growth was negative 5.9%. P&G’s 21 forward P/E and superior 5.8% earnings growth make our target reasonable rather than aggressive.
Kimberly-Clark (NASDAQ:KMB) offers the valuation contrast. Kimberly-Clark trades at a forward P/E of just 15 with a 4.47% yield, reflecting slower growth in paper-based staples. That gap explains why P&G commands a premium and why our Price Target implies multiple stability rather than expansion.
| Company | Forward P/E | Div Yield |
|---|---|---|
| P&G | 21 | 2.84% |
| Colgate-Palmolive | 24 | 2.26% |
| Kimberly-Clark | 15 | 4.47% |
P&G Price Prediction 2026 to 2030
The 24/7 Wall St. price target of $164.75 and buy rating rest on a durable dividend, expanding free cash flow, and a Beauty segment that compounds.
The setup favors investors who value a 0.38-beta compounder with 70 years of raises and can wait for FY27 tariff headwinds to lap. Investors who need volume-led growth today may find the setup less compelling, since organic sales were flat in two of four quarters this year.
Here is where our model projects P&G could trade, assuming current growth trajectories and capital return policies hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $155 |
| 2027 | $164.75 |
| 2028 | $180 |
| 2029 | $199 |
| 2030 | $220 |
These projections assume P&G continues executing the productivity and premiumization playbook. Significant upside or downside could result from sharper reacceleration in user growth or a prolonged tariff and commodity cycle outlasting the FY27 reinvestment plan.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.