Applied Digital Is Down 41% This Year. What Will It Take to Get APLD Stock Back to $20?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
This year’s selloff in artificial intelligence (AI) data-center stocks has left Applied Digital (NASDAQ:APLD) with a long way to climb. Applied Digital shares traded at $14.55 in the afternoon, down 9%. That’s the latest leg of a slide that has wiped out a large share of the company’s value. The decline now stands at 41% year to date (YTD).
The $20 mark matters because Applied Digital traded at that level only weeks ago. Applied Digital stock closed at $20.33 on October 14 after finishing 2025 at $24.52. Getting back there would take progress on construction schedules, tenant payments and financing costs, along with a better mood toward AI infrastructure.
What Has Weighed on Applied Digital in 2026
Pressure has hit the whole group. AI data-center stocks are under strain as investors question debt-funded AI capacity and whether AI spending holds up. Leadership turmoil at NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) ahead of its upcoming earnings report has added to the uncertainty . That puts Applied Digital squarely in the middle, since the company pays for its campuses with large note offerings. The picks-and-shovels suppliers are a separate trade. The power, cooling and networking names behind that expansion are worth knowing (we rounded up seven of them in a free report here).
Applied Digital’s most recent quarter showed rapid growth with a caveat. On October 7[1], the company reported Q1 FY2027 revenue of $341.88 million, up 432.4% year over year (YoY). It also reported an adjusted per-share loss of $0.01[1], compared with a consensus estimate of a $0.3023 loss. Of that revenue, $183.5 million[1] came from tenant fit-out services, which is construction work billed to tenants, while base rent contributed $65.8 million. On a GAAP basis, the company still booked a net loss of $184.1 million[1].

How IREN and CoreWeave Stack Up Against Applied Digital
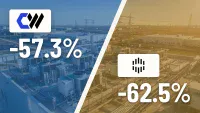
Next to IREN (NASDAQ:IREN), Applied Digital’s drop looks softer. IREN stock is down 57% YTD to $16.24. A former crypto miner, IREN now owns graphics processing units (GPUs) and sells AI cloud computing directly, which means it carries hardware risk that Applied Digital’s core hosting business leaves to its tenants.
The smallest decline of the three belongs to CoreWeave (NASDAQ:CRWV). CoreWeave stock is down 31% YTD to $49.25. Running a GPU cloud, the company rents computing power to AI labs, hyperscalers and enterprises, and it’s also one of Applied Digital’s tenants at Polaris Forge 1. So CoreWeave’s financial health feeds directly into Applied Digital’s rent.
Applied Digital’s model sits a layer below both peers. The company builds and owns the buildings, power and cooling, then rents that space to hyperscale customers under long-term contracts.
Bull and Bear Cases for Applied Digital
Applied Digital’s contract book gives optimists reason for confidence. As of August 31[2], the company had about 1.41 gigawatts (GW) of rents critical information technology (IT) load across five[3] campuses, representing roughly $36 billion[4] of contracted revenue over initial base terms. Contracted revenue is money tenants have already agreed to pay under signed leases, which gives Applied Digital a clearer view of future income than a business that sells month to month. On top of its leases, the company owns 96%[5] of ChronoScale Holdings (NASDAQ:CHRN), a publicly traded accelerated-compute platform.
Wes Cummins spoke on the October 7[6] earnings call. The Applied Digital Chairman and CEO argued that tighter local rules for new data centers raise the value of campuses that are already running. “Every new restriction elsewhere means what we already own [is] harder to replicate and more valuable,”[6] Cummins said.
Skeptics zero in on two risks: concentration and capital. Concentration is one worry, since Applied Digital depends on a small number of large tenants and trouble at any one of them could hurt its revenue. Financing is the other, because the company needs steady access to capital markets to fund new campuses, and that access can tighten quickly when sentiment toward AI infrastructure turns.
Applied Digital’s Road Back to $20
Recovering to $20 would require a string of solid wins for Applied Digital. Applied Digital’s next hurdle is whether Polaris Forge 2 lifts its North Dakota critical IT load to 300 megawatts (MW) by the end of 2026, as the company expects. Steady rent from tenants such as CoreWeave, plus new financing on workable terms, would strengthen that path.
A calmer mood toward AI infrastructure stocks may matter just as much, given that Applied Digital has fallen alongside IREN and CoreWeave this year. On the downside, construction delays, tenant stress or costly debt could keep Applied Digital stock well below its October 14 close. Moreover, Applied Digital’s financing and build-out picture may remain the key variable for the APLD stock until it settles.
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk. His work has appeared in 24/7 Wall St., The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, MarketScreener, TalkMarkets, Finmasters, and others. With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.