Greg Abel Might Have Just Made a $2 Billion Mistake Warren Buffett Avoided

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
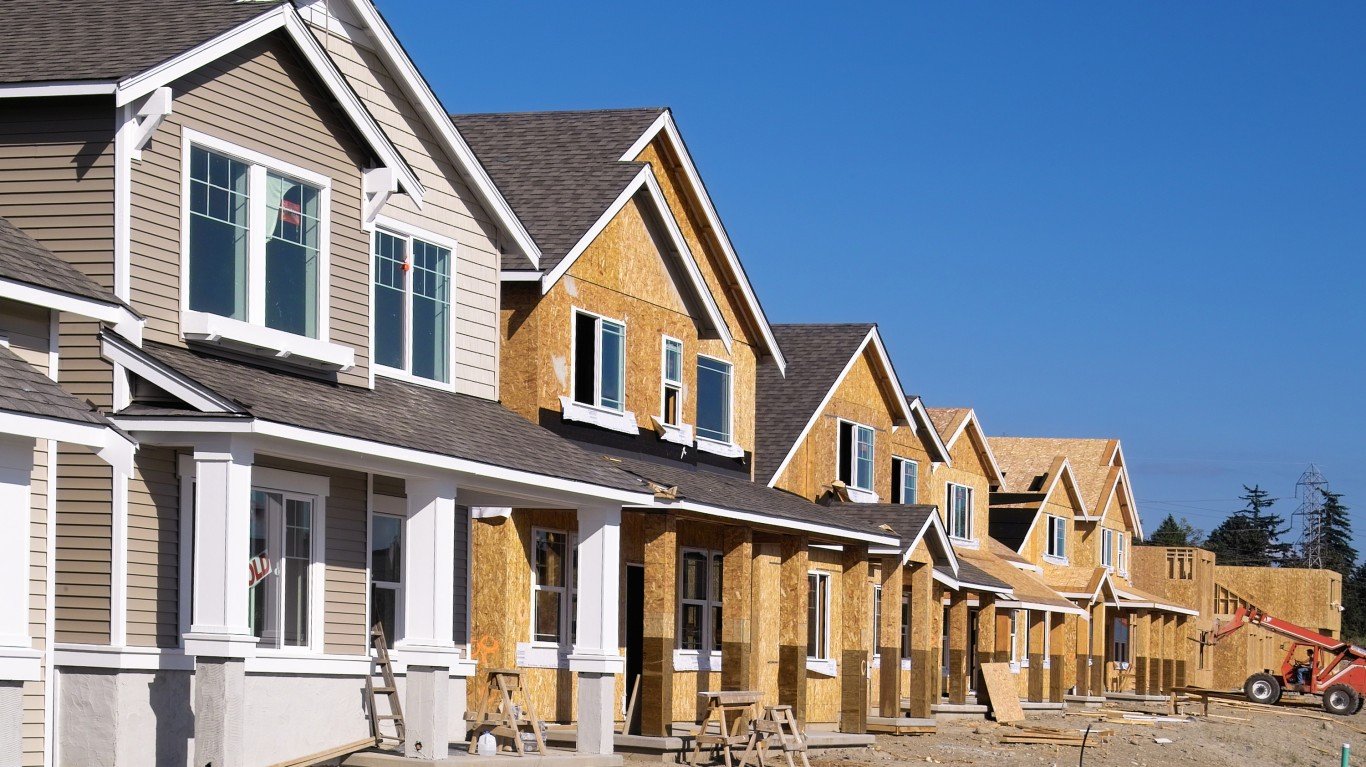
Berkshire Hathaway (NYSE:BRK-A | BRK-A Price Prediction) now owns one of the biggest housing positions in its stock portfolio, and it built that position under Greg Abel. Berkshire’s latest 13F shows 26,034,436 Class A shares of Lennar (NYSE:LEN) as of September 30. Three months earlier it held 13,111,741. The stake was worth $2.12 billion, even though Lennar shares are down 29.24% over the past year to $83.83.
Abel has said he expects the downturn to drag on. “We don’t envision a quick recovery there, but we do see it as an industry that we definitely want to be invested in, and we’re invested in for the long term,” he told CNBC on September 2.
Buffett Kept Homebuilders on a Short Leash
Buffett’s record with homebuilders shows short holding periods. In Q2 2023, Berkshire bought 5,969,714 shares of D.R. Horton (NYSE:DHI), plus small Lennar and NVR (NYSE:NVR) positions. In Q4 2023 it sold all of the D.R.
Horton shares and exited within months at a profit. The pattern repeated in 2025: Berkshire bought about 1.5 million D.R. Horton shares in Q2 and sold them in Q3.
Lennar is the holding Buffett kept. When he stepped down, Berkshire owned about 7.2 million Lennar shares. Abel has turned that modest inheritance into a position worth more than $2 billion. He also closed the $6.8 billion Taylor Morrison acquisition in July.
Lennar’s Numbers Keep Getting Worse
Lennar’s fiscal third-quarter release shows how much pressure the business is under. Revenue go down 8.52%[1] to $8.05 billion. Adjusted EPS of $1.23[1] missed the $1.30 consensus, and net income dropped 51.96%. Gross margin on home sales came in at 15.8%[1], compared with 17.5% a year earlier. Full-year delivery guidance was cut to 80,000 to 81,000[1] homes.

CEO Stuart Miller said lower margins are the price of keeping sales volume up: “We are compromising margin in order to maintain volume.”[2] He blamed land bought at old prices: “The land headwind is still in front of us for a while, but it is finite, it is visible and every quarter of volume shortens it.”
The broader market offers little relief. Housing starts go down to 1.22 million[3] annualized in September, down 7.43% from a year earlier. Miller also put the 30-year mortgage rate at approximately 7%[2].
Why Abel’s Math Could Still Work
Compared with the rest of Berkshire, the position is small. Lennar makes up 0.7% of Berkshire’s $304.20 billion stock portfolio, and Berkshire’s market cap is about $1.26 trillion. Berkshire’s Class A shares are up 17.31% year to date, so a weak Lennar is barely moving overall results.
Lennar’s balance sheet also limits the damage. The company owns about 2%[2] of its homesites and controls the rest through third parties. Book value is approximately $91[2] per share, above the current stock price. Management has been buying back shares: 3 million shares for $256 million[1] last quarter. Miller pointed to the valuation: “Don’t think that it hasn’t escaped our attention that our stock price is on sale.”[2]

Buffett sold homebuilders once the recovery looked early. Abel is buying through a slump he expects, using capital that has no deadline to show a return. Whether that turns out to be a error depends on how long Lennar’s margins stay weak.
Catalysts That Will Decide the Outcome
- Lennar’s fiscal Q4 report: Management guided to a gross margin of 15.5% to 16%, 22,000 to 23,000[2] deliveries, and EPS of about $1.30 to $1.65. Last year’s fourth-quarter release came on December 16.
- Berkshire Form 4 filings: Berkshire owns more than 10% of Lennar, so it has to report trades within two business days. It already held 28,438,045 Class A shares after its purchases in early October, as we reported at the time.
- Mortgage rates and resale supply: Miller called resale sellers “a more aggressive competitor for our customer.”[2]
For Berkshire shareholders, Lennar is a small, calculated position that will take years to judge. For Lennar shareholders, Abel’s buying shows Berkshire is willing to wait, but the company’s own guidance doesn’t yet show margins improving.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.