59 Analysts Rate Amazon a Buy. Here’s Where the Stock Could Go

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The e-commerce giant’s most important growth engine sits behind the storefront. AWS posted $45.98 billion[1] in third-quarter revenue, up 39% and its fastest growth in nearly five years.
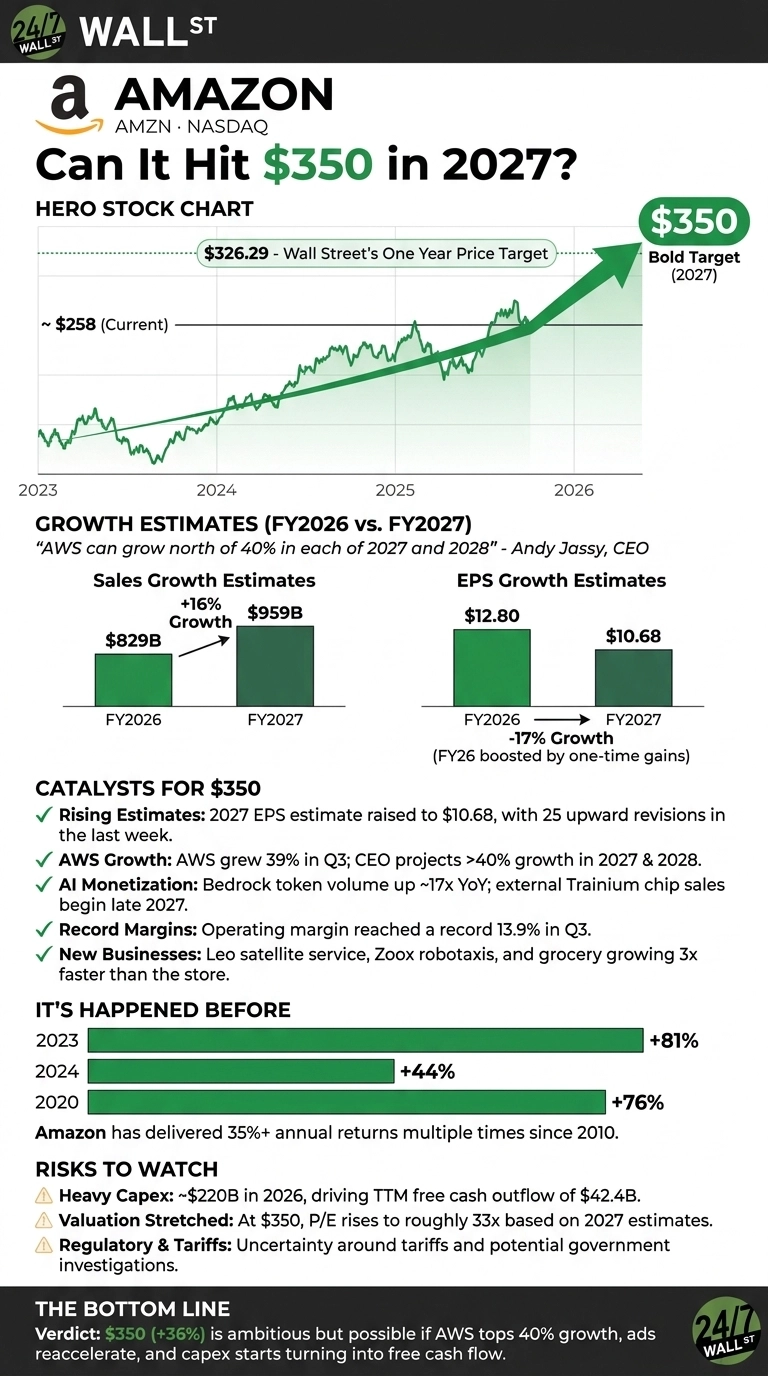
CEO Andy Jassy told investors AWS can grow “north of 40% in each of 2027 and 2028.”[2] Shares of Amazon (NASDAQ:AMZN | AMZN Price Prediction) are up 11.73% year to date at $257.89 and have gained 578.52% over 10 years.
Wall Street Sees Over 26% Upside in Amazon
Analysts are nearly unanimous: 16 rate Amazon a Strong Buy, 43 a Buy, 2 a Hold, and none a Sell. The consensus target of $326.29 implies 26.5% upside.

Analysts expect 2027 revenue of $959.35 billion, roughly 15.7% growth. The 2027 EPS estimate of $10.6826 sits below the 2026 figure of $12.8038 because 2026 included Anthropic investment gains, such as a $53.4B[3] pre-tax gain in Q2.
Can Amazon Really Hit $350? Let’s Do the Math
Amazon currently trades at about 24x 2027 estimated earnings. At $350, that multiple rises to roughly 33x. That premium is justified if AWS delivers 40%+ growth on a $578 billion[2] backlog that is growing triple digits, while companywide operating margin already reached a record 13.9%[1].

What Could Push Amazon to $350?
- Rising estimates: 90 days ago, analysts expected $10.5314 in 2027 EPS. Today it is $10.6826, with 25 upward revisions in the past week.
- Earnings track record: Amazon beat or matched EPS estimates in six of the past seven quarters. The only miss was Q3 ($1.89 vs. $2.01).
- AI demand: Bedrock token volume grew nearly 17x[2], and Meta Platforms (NASDAQ:META), NVIDIA (NASDAQ:NVDA) and OpenAI signed new AWS agreements. External Trainium chip sales begin in late 2027[2].
- Profit momentum: Q4 operating income guidance of $28.5-33.5B[1] compares with $25.0B a year ago, and ad growth should return to the high teens[2].
- New businesses: Amazon Leo satellite service, Zoox paid robotaxi rides in Las Vegas, and grocery growing about 3x faster than the rest of the store.

The main challenge is spending. 2026 capex of about $220 billion[1] drove a trailing free cash outflow of $42.4 billion, and tariffs remain an uncertainty.
Amazon’s History Says a 36% Gain Is Achievable
Reaching $350 requires a 35.7% gain. Since 2010, Amazon has cleared that bar in seven calendar years. Shares rose 80.9% in 2023, 44.4% in 2024, 76.3% in 2020 and 117.8% in 2015.
At a market cap near $2.79 trillion, matching those runs is harder. Still, the stock traded as high as $287.20 within the past 52 weeks, so part of the path is recovering recent ground.
$350 Is a Stretch, but Here’s Why It’s Possible
Hitting $350 requires Amazon to gain 35.7%. Wall Street already sees 26.5% upside, 2027 estimates are rising, and AWS is accelerating with visibility Jassy says extends into 2029.
If AWS tops 40% growth, ads reaccelerate and capex starts turning into free cash flow, a 33x multiple becomes easier to justify. Keep an eye on the stock around the Q4 earnings report for confirmation. Gains of this magnitude are rare in any single year, and these catalysts show how Amazon could deliver outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.