The Bull Case for This Stock Is Getting Harder to Ignore
AWS just posted its fastest growth in 18 quarters, Amazon is pouring $200 billion into AI infrastructure, and analysts keep lifting their targets. So what would it actually take to push AMZN from here to $350?

Amazon (NASDAQ: AMZN | AMZN Price Prediction) is having the kind of year that reminds investors why they own it. Shares are up 15.43% year to date and 17.55% in the past month alone, riding a July earnings report that CEO Andy Jassy summed up bluntly: “AWS is booming.”
Cloud growth just hit its fastest pace in 18 quarters, advertising is compounding at a mid-20s clip, and management is pouring roughly $200 billion into AI infrastructure this year. Let’s walk through what it would take for AMZN to hit $350 per share in 2027.

Wall Street Is Already Warming to Amazon’s 2027 Setup
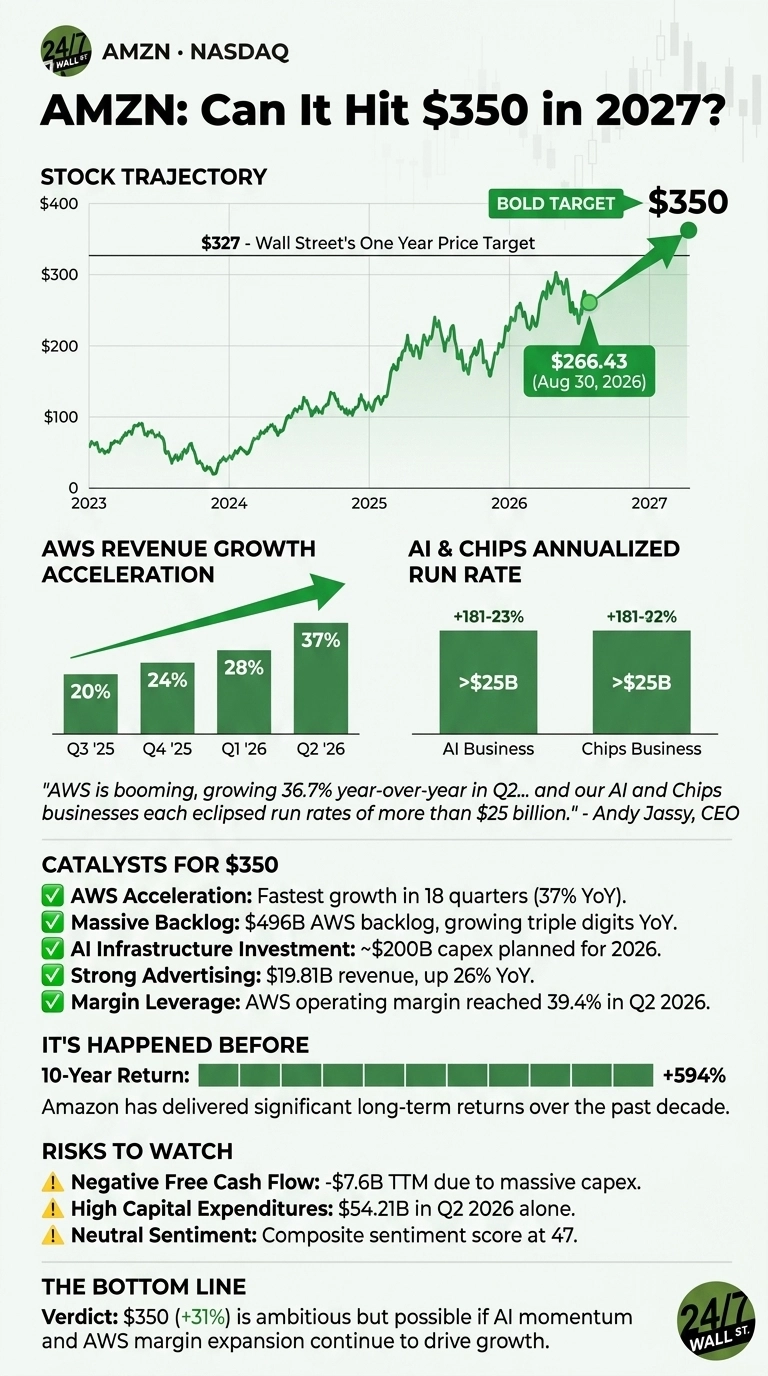
The consensus 1-year price target sits at $327, with 43 Buys, 16 Strong Buys, and just 3 Holds among covering analysts. That target implies meaningful upside from today’s $266.43 close, and it’s been drifting higher as AWS reaccelerates.
AWS growth has climbed from 20% in Q3 2025 to 24%, then 28%, and 37% in Q2 2026. Amazon has also topped EPS estimates in each of the last four quarters, including a 60.69% beat in Q1 2026. When a mega-cap is accelerating and beating, forward estimates tend to keep migrating up.

Path to $350 Per Share
AMZN trades at a forward P/E of roughly 22, essentially in line with the S&P 500. Forward EPS is pegged at $14.42. At $350, shares would trade around 24x forward earnings, a modest premium that looks reasonable when quarterly earnings grew 242% and operating income expanded 43% year over year last quarter.
What could push AMZN to $350?
- AWS backlog. The book stands at $496 billion, growing triple digits year over year, with 2027 capacity largely reserved already.
- AI and custom silicon. Amazon’s AI and Chips businesses each cleared $25 billion annualized run rates, with OpenAI and Anthropic committing to multi-year, multi-gigawatt Trainium capacity.
- Advertising. Ads revenue reached $19.81 billion, up 26%, with sold-out NFL, NBA, and NASCAR inventory.
- Margin leverage. AWS operating margin hit 39.4%, and Jassy told investors AWS could become “a trillion-dollar annual revenue business” in time.
- Rate relief. The 10-year Treasury at 4.67% sits near cycle highs. Any easing would lift growth-stock multiples.

History Says This Kind of Move Isn’t a Stretch
Hitting $350 requires roughly a 31% gain from here. AMZN has done that and more many times. Over the past decade, shares are up 594%.
Prediction markets are already leaning into the setup, with Polymarket assigning 87% probability to 2026 capex exceeding $200 billion, a proxy for AI capacity coming online in 2027 (we mapped seven suppliers riding that same buildout, from power to networking, in a free report on AI infrastructure names that aren’t chipmakers).
Bottom Line on $350
Reaching $350 by late 2027 requires Amazon to keep converting AI capex into cloud revenue, hold advertising’s mid-20s growth, and let AWS margins do the heavy lifting.
Risks are real. Free cash flow is negative $7.6 billion TTM, and near-term sentiment reads neutral at 47. But with a $327 Street target, accelerating AWS, and a backlog approaching half a trillion dollars, the bull case for AMZN is genuinely getting harder to ignore.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.