NVIDIA Posted $115.8 Billion in Revenue. Why Is the Stock Still Down 27% in a Month?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
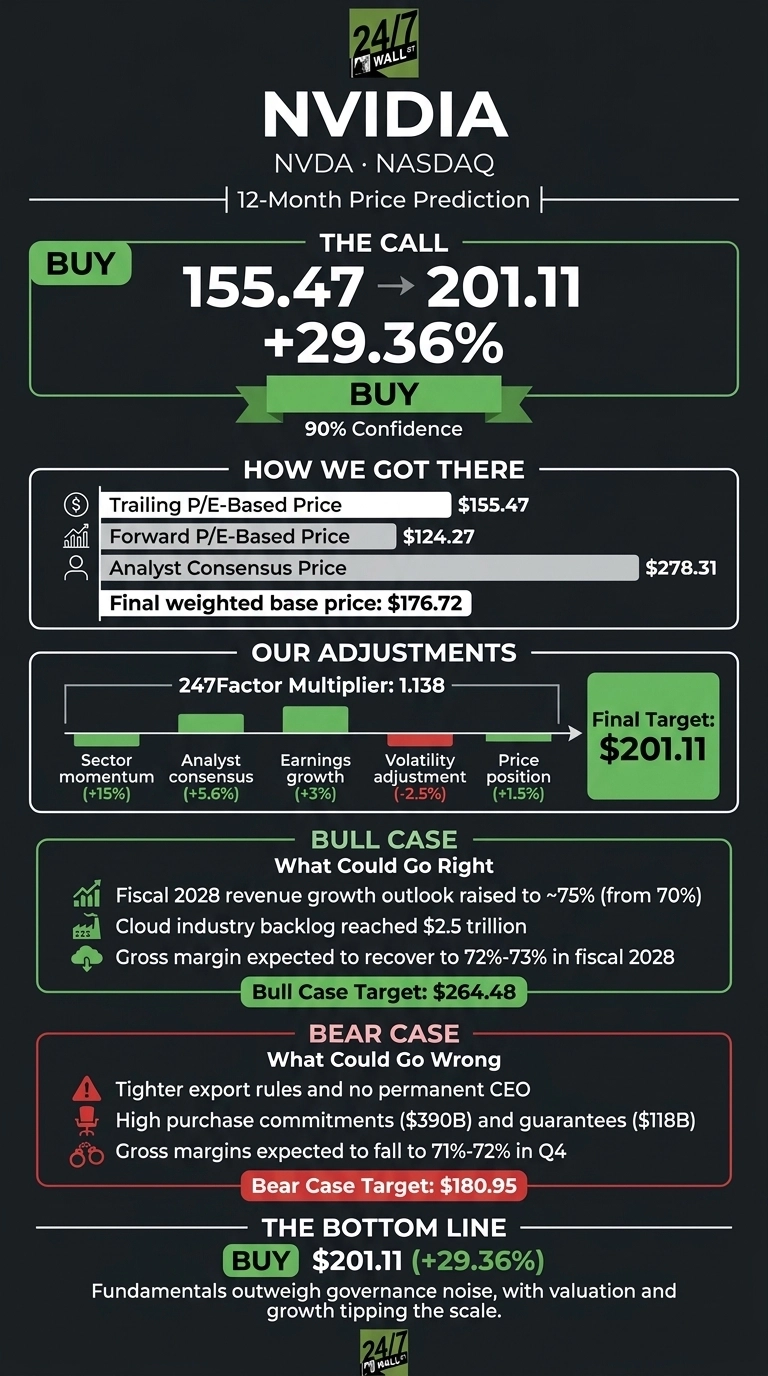
NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) reported $115.84 billion[1] in fiscal third-quarter revenue, up 103.2% year over year. The stock still trades at $155.47. The 24/7 Wall St. price target for NVIDIA stands at $201.11, which means 29.36% upside over the next 12 months.
| Metric | Value |
|---|---|
| Current Price | $155.47 |
| Price Target from 24/7 Wall St. | $201.11 |
| Upside/Downside | 29.36% |
| Recommendation | BUY |
| Confidence Level | 90% |

The stock gets a buy rating with high confidence from our model. NVIDIA trades at about 12x forward earnings while revenue keeps growing. I see the selloff as a governance and policy discount applied to a business that is still accelerating.
A CEO Exit and Export Rules Overshadow a Record Quarter
Shares fell 27.31% over the past month and 7.83% in the past week. They are down 16.34% year to date and sit near the bottom of a 52-week range of $148.80 to $243.37.
The board said on November 12[2] that Jensen Huang had resigned as CEO after “disclosure of personal behavior inconsistent with the company’s code of conduct”. Colette Kress is now interim CEO, and an independent investigation is ongoing.
The quarter beat expectations. Non-GAAP EPS of $2.68[1] beat the $2.47 consensus. Data Center revenue reached $107.60 billion[1], and Vera Rubin generated “nearly $20 billion”[2] in its first production quarter.
Investors instead focused on new export controls, the end of licensed Hopper shipments to China, and Q4 gross margin guidance of 71-72%[1], down from 74.9%[2] in Q3. This pattern has shown up before. Across seven straight beats, the stock’s average one-day move after earnings was -2.97%.
Why Bulls See $264 or Higher
Management raised its fiscal 2028 revenue growth outlook to approximately 75%[2] from 70% and guided Q4 revenue to $130 billion[1]. Backlog in the cloud industry reached $2.5 trillion[2], a expansion that also has to be powered, cooled, and networked by somebody (we covered seven of those non-chipmaker suppliers in a free report).
Management also expects gross margin to recover to 72% to 73%[2] in fiscal 2028, and $227.3 billion[1] remains on the buyback authorization. Analysts’ ratings break down as 10 Strong Buy, 49 Buy, 2 Hold and 1 Sell, with a consensus target of $278.31. After the report, Morningstar called the shares cheap. The bull case stands at $264.48.

Leadership Gaps and Swelling Commitments Cloud the Picture
NVIDIA now faces tighter export rules without a permanent CEO, and the board says it will take its time with the search. Purchase commitments reached $390 billion[1], and guarantees reached $118 billion.
Three direct customers made up 14%, 11% and 11%[1] of revenue. As offsets, management says neocloud guarantees end if a customer’s expansion stalls, and it calls Q4 the bottom for margins. Our bear case is $180.95, which is still above the current price.

Is NVIDIA Cheaper Than AMD and Broadcom?
Advanced Micro Devices (NASDAQ:AMD) is NVIDIA’s most direct GPU rival. AMD’s Q3 revenue grew 44.68%, and the stock trades at a trailing P/E of 190. NVIDIA is growing faster and trades at 31 times trailing earnings.
Analysts on the call asked about competition from custom chips (ASICs), represented by Broadcom (NASDAQ:AVGO). Revenue from AI semiconductors rose 221% to $16.70 billion, still far below NVIDIA’s Data Center revenue. Against these two peers, our target looks conservative.
| Company | Trailing P/E | Latest Quarter Revenue Growth |
|---|---|---|
| NVIDIA | 31 | 103.2%[1] |
| AMD | 190 | 44.68% |
| Broadcom | N/A | 85.5% |
Fundamentals Outweigh Governance Noise at $155
Our 24/7 Wall St. price target of $201.11 comes with a buy rating and 90% confidence. Valuation tips the scale for me.
NVIDIA’s case improves if Vera Rubin keeps growing and margins recover. The risks rise if the investigation broadens or export limits spread to more markets. On balance, the fundamentals has more weight than the headlines.
The table below shows where our model projects NVIDIA could trade if current growth patterns continue.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $158.63 |
| 2027 | $208.33 |
| 2028 | $246.55 |
| 2029 | $279.87 |
| 2030 | $302.96 |
NVIDIA would need to keep executing on its Rubin and Feynman roadmap for these projections to hold. The CEO search, export policy and customer financing could move the stock well above or below these targets.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.