AMD Slides 6% Despite Jim Cramer Calling Hunterbrook Short Report a ‘Hitjob’; NVIDIA Falls 3% Near Damodaran’s $140 Buy Price, Intel Declines 2%

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
China-related scrutiny is spreading through the chip sector, and Advanced Micro Devices (NASDAQ:AMD | AMD Price Prediction) is taking the hardest hit. AMD stock is at $458.81, down 6% in morning trading, extending a slide that began after a short seller’s report on November 19. Even with that pullback, the chipmaker is still up 114% year to date (YTD), a run built on surging demand for its data center processors.
The selling is also reaching the rest of the artificial intelligence trade. Anthropic (NASDAQ:ANT) shares are sliding on their second trading day, and technology is the weakest sector in the market. That backdrop leaves AMD with little cushion against fresh bad news.
Hunterbrook Short Report Puts AMD’s China Ties Under the Microscope
Hunterbrook Media asserted in a report on November 19 that AMD’s exposure to China leaves it vulnerable to more U.S. chip export restrictions. According to the report, U.S.-blacklisted Chinese server maker IEIT Systems kept publishing software updates containing newer AMD firmware after its March 2025 blacklisting. A short position in AMD was disclosed by Hunterbrook Capital, while the report itself conceded that its findings don’t establish an export-law violation.
In a statement to Bloomberg, AMD declared that the claims “misrepresent AMD’s business practices and relationships.” The company added, “AMD complies with applicable US export control laws and regulations and maintains rigorous processes to ensure compliance across our global operations.”
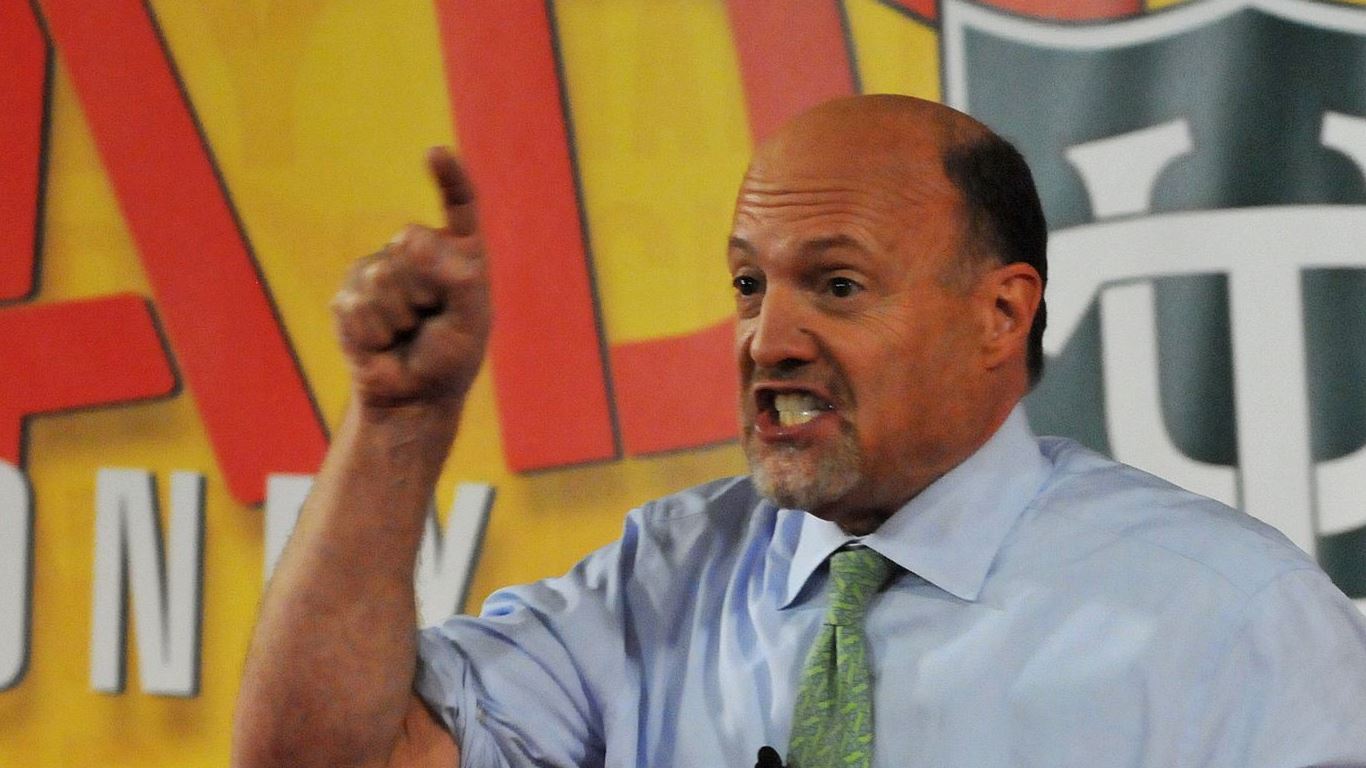
CNBC’s Jim Cramer came to AMD’s defense, writing on X, “We believe the shortseller’s attack on AMD does not hold up to close scrutiny.” Cramer went further in a follow-up post, calling the report a “hitjob.” So far, that support hasn’t stopped the selling in AMD stock.
NVIDIA and Intel Follow AMD Lower
NVIDIA (NASDAQ:NVDA) stock is at $141.08, down 3%, a smaller decline than AMD’s. The graphics chip leader is down 24% YTD. Aswath Damodaran, the New York University professor known as the “Dean of Valuation,” wrote in a blog post that he has a limit buy order waiting at a breakeven value of $140[1] per share, set 30% below his $4.8 trillion estimated value for NVIDIA.
In that post, Damodaran called China “the wild card in this story” and noted that NVIDIA’s intrinsic value “has likely dropped due to leadership loss and scandal fallout.” Congressional pressure is building, too. Reuters reports that two House Democrats opened an inquiry into whether NVIDIA tried to influence the Commerce Department’s investigation of Megaspeed, a Singapore-based cloud company suspected of diverting advanced chips to China, and asked Commerce Secretary Howard Lutnick for answers by December 1.
Responding to Reuters, NVIDIA said it consults with Commerce officials and looks forward to “engaging with Congress on this matter.” The company is also searching for a permanent CEO after former CEO Jensen Huang resigned, with Colette Kress serving as interim CEO[2].
Intel (NASDAQ:INTC) stock is at $54.45, down 2%, the mildest decline of the three. Over the past month, Intel stock has fallen 41%, a steep pullback that shows how widely the selling has spread across chipmakers.
Three Chipmakers, Three Different Business Models
AMD competes on both sides of the data center. The company sells Instinct accelerators and Helios rack-scale systems for artificial intelligence workloads alongside EPYC server processors, while Ryzen PC chips, Radeon graphics and embedded products round out its lineup. Third-party foundries handle AMD’s manufacturing.
NVIDIA dominates artificial intelligence training and inference with its graphics processors, and its CUDA software ecosystem keeps developers tied to its platform. Intel, by contrast, leans on its Xeon and Core processors and runs its own factories through Intel Foundry, a business that’s still posting operating losses. That mix matters here because AMD’s server chips reach buyers through outside server makers, the channel at the center of Hunterbrook’s report.
Short Sellers, Congress and the Road Ahead for AMD
The next test for AMD is whether Hunterbrook’s claims draw a response from U.S. regulators or lawmakers. For their part, the bulls, Cramer among them, see the short report as an overreaction, and Damodaran’s limit order suggests NVIDIA’s slide may be opening a window for value-focused buyers.
On the other side, the bears argue that China exposure could prove a lasting risk for the whole group as congressional scrutiny widens from NVIDIA to AMD. A drawn-out probe could weigh on chip valuations even if demand for data center hardware stays strong, and the power, cooling and networking suppliers behind the AI buildout may hold up better than the chipmakers themselves (we profiled seven of them in a free report on AI infrastructure).
Watch for any Commerce Department statement on IEIT Systems or Megaspeed, since either could shift sentiment toward AMD and its rivals. A cautious investment approach could make sense while the China export scrutiny of AMD plays out.
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk. His work has appeared in 24/7 Wall St., The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, MarketScreener, TalkMarkets, Finmasters, and others. With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.