If AMD Grows at 15% a Year, Here’s What $5,000 Could Become by 2030

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Advanced Micro Devices (NASDAQ:AMD | AMD Price Prediction) is one of the market’s biggest AI winners. Shares are up 150.98% year to date and closed at $530.14 in the latest session.
So what could a $5,000 investment grow to by 2030 if AMD’s growth slows to something closer to 15% a year? The answer depends on which path the AI expansion takes.

What $5,000 Could Become in the Base Case
The price model for AMD runs a five-year horizon that ends on November 18, 2031, starting from a assumed price of $514.53. The year 2030 falls inside that window, ahead of its end point, so the five-year horizon grounds the concrete figures.
Under that scenario, a $5,000 investment could be worth about $5,814.50 at the end of that horizon, a total return of 16.29% (3.07% annualized). That rests on a assumed base-case share price of $598.37.

As an illustrative checkpoint, the model’s base path reaches $551.02 on November 18, 2030. At that price, $5,000 would be worth roughly $5,354.60.
Bull, Base and Bear: Your $5,000 Across Three Paths
| Scenario | Five-Year Target Price | Total Return | Value of $5,000 | Projected 2030 Price | Projected 2030 Value |
|---|---|---|---|---|---|
| Bull | $1,017.17 | 97.69% | $9,884.50 | $965.55 | $9,382.83 |
| Base | $598.37 | 16.29% | $5,814.50 | $551.02 | $5,354.60 |
| Bear | $403.55 | -21.57% | $3,921.50 | $396.33 | $3,851.38 |
The headline’s 15% assumption reflects the more optimistic outlook, which compounds at 14.6% a year.
For comparison, a flat 15% annual gain would turn $5,000 into $8,745.03 over four years and $10,056.79 over five. Those flat-rate figures are simple projected compounding for comparison.
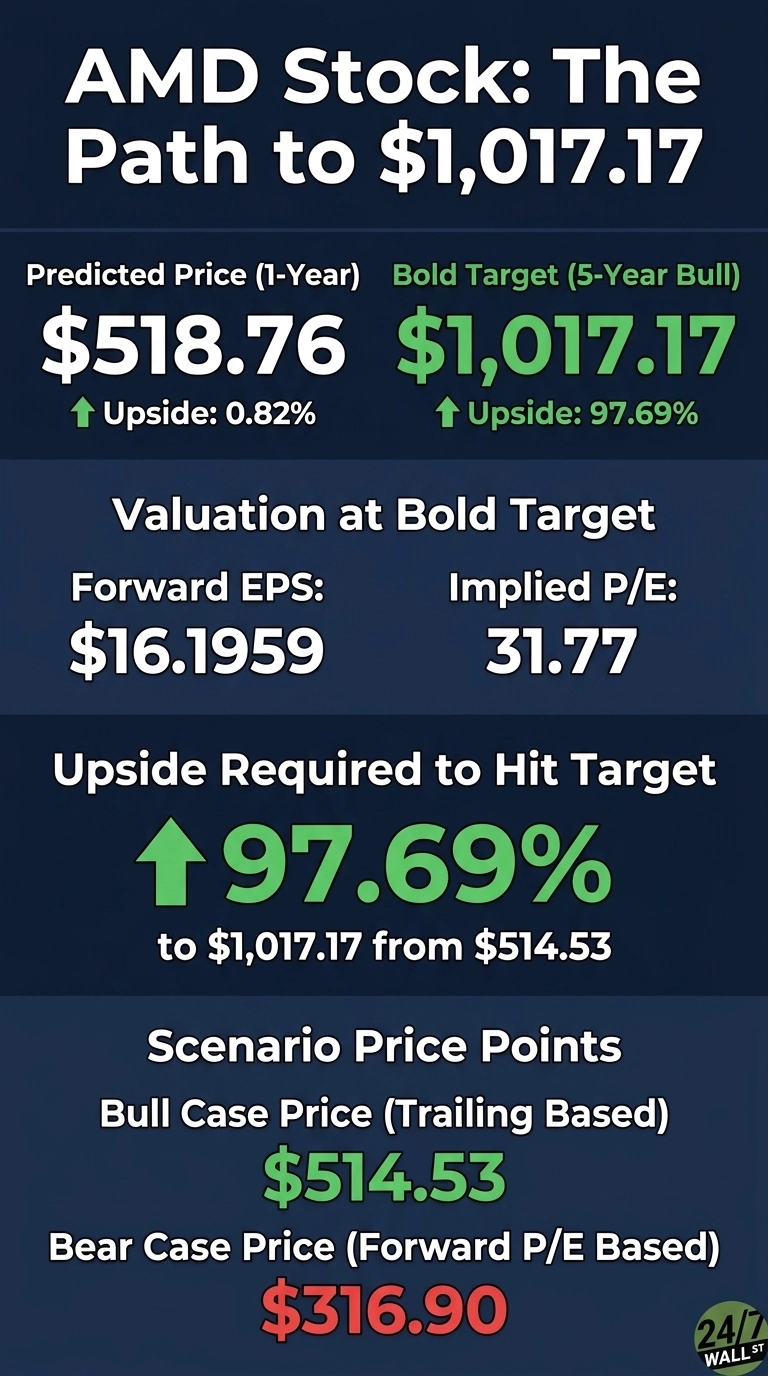
Closer in, the model’s one-year target is $518.76, meaning 0.82% upside and a hold rating because the stock trades near fair value.
Assumed confidence is rated high (0.9). Analysts are more upbeat, with a consensus target of $657.74, 5 Strong Buy, 39 Buy and 11 Hold ratings and no Sells.

Data Center Growth Behind the Bull Case
AI demand is changing the business. Third-quarter revenue rose 44.7%[1] to $13.377 billion, and Data Center sales jumped 97% to $8.546 billion. Segment operating margin expanded to 34% from 25%[1]. Anthropic, Meta Platforms (NASDAQ:META), Microsoft (NASDAQ:MSFT), OpenAI and Oracle (NYSE:ORCL) are running workloads on AMD’s first Helios rack-scale systems.
The AI story goes well past the chipmakers themselves, which is why we pulled together seven power, cooling and networking suppliers riding the same expansion in a free report you can grab here.
Guidance points higher. AMD guided fourth-quarter revenue to about $17 billion[1], plus or minus 3%. On the earnings call, CEO Lisa Su said, “Based on our current visibility, we now expect revenue to grow more than 80% in 2027.”[2]
Execution has been consistent. Non-GAAP EPS of $2.09 beat the $1.9366 estimate, and revenue beat expectations in every quarter from late 2024 onward.
So why are expectations so modest? The stock trades at about 200x trailing earnings and 32x forward earnings, and the model’s forward-earnings valuation alone comes to just $316.90. Much of the expected growth may already be in the share price.
Risks That Could Shrink Your Stake
- Supply limits: Su acknowledged that “demand is higher than supply,”[2] and AMD depends on outside partners for wafers, substrates, packaging and memory.
- PC and gaming weakness: Gaming revenue fell 40%[1], and management expects the PC market to decline by a double-digit percentage in 2027.
- Balance sheet and accounting noise: Inventory reached $11.463 billion[1] and total debt $7.079 billion. A $1,097 million[1] customer warranty charge cut GAAP EPS to $1.46.
- Volatility and policy: With a beta of 2.542 and a 52-week range of $188.22 to $658.52, the stock can swing hard. US export controls on AI accelerators add another layer of risk.
What This Means for Your $5,000
Over a five-year horizon, a $5,000 stake in AMD ranges from $3,921.50 in the bear case to $9,884.50 in the bull case, with a base case of $5,814.50. The projected 2030 checkpoints run from $3,851.38 to $9,382.83.
Reaching the 15% path requires AMD to keep converting AI demand into profits at today’s rate. Projections like these are intended for research purposes, and none of them is guaranteed.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.