BIZD Owns the Lenders Behind the Private Credit Boom in One Ticker, and Yields in the Double Digits

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
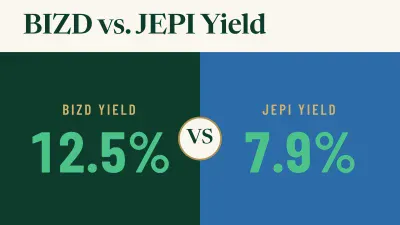
Private credit has become one of Wall Street’s fastest-growing corners. Asset managers now lend directly to mid-sized companies that banks have pulled back from. Many retirees hear about the boom secondhand and assume only pensions and wealthy investors can get in. However, one exchange-traded fund has owned the publicly traded side of that market for years: the VanEck BDC Income ETF (NYSEARCA:BIZD). At a recent price of $12.49, it carries a trailing 12-month distribution yield of 12.5%.
The natural comparison is a fund retirees are much more likely to own already: the JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI).
What a BDC Is and Why Its Yield Runs So High
A business development company, or BDC, is a publicly traded firm that lends to mid-sized private businesses, mostly through floating-rate loans. To avoid paying corporate income tax, a BDC must pass most of its income through to shareholders. That rule is the main reason BDC yields sit well above the 5.10%[1] yield on the 10-year Treasury as of November 12.
Dozens of Private Lenders in One Ticker
BIZD packages these lenders into a single fund. It held $1.63 billion[2] in net assets in its June 30, 2026 portfolio filing. The largest positions carry a lot of weight. Ares Capital (NASDAQ:ARCC | ARCC Price Prediction) alone made up 14.3%[3] of net assets. Next came Blue Owl Capital Corp (NYSE:OBDC) at 5.9%[3] and Blackstone Secured Lending Fund (NYSE:BXSL) at 5.4%[2]. Together, the top five BDC positions accounted for about 33.9% of the fund. The rest is spread across more than two dozen smaller lenders, and many of them sit below 1% each.
A Double-Digit Yield Paid in Uneven Checks
BIZD paid $1.5595 per share over the trailing 12 months. Annualizing the latest quarterly payout of $0.4371, the forward yield comes to approximately 14%. The checks do vary, though. The fund paid $0.4818 in April, then $0.2391 in July, then $0.4371 in October. Retirees who budget around a steady check should plan for that swing. JEPI pays monthly. It distributed $4.56396 over the past year, a trailing yield of about 7.9%.
How BIZD Stacks Up Against JEPI
| Metric | BIZD | JEPI |
|---|---|---|
| Payout frequency | Quarterly | Monthly |
| Trailing 12-month yield | 12.5% | 7.9% |
| Expense ratio | Includes underlying BDC costs | 0.35%[4] |
| Year-to-date total return | -3.32% | 8.16% |
| 1-year total return | -0.7% | 10.4% |
| 5-year total return | 23.1% | 44.18% |
BIZD pays out more income, but JEPI has delivered the better total return recently. Over the long run, BIZD’s dividend-adjusted return reached 101.57% over ten years.
Risks Retirees Need to Weigh First
- Credit losses: BDCs lend to smaller companies that often carry heavy debt. In a recession, more of those loans can go bad.
- Payout cuts: The July distribution shows how fast income can shrink.
- Falling rates: Most BDC loans have floating rates, so lower short-term rates reduce the interest the BDCs collect.
- Fee optics: BIZD’s reported expense ratio counts the BDCs’ own management, incentive, and interest costs as acquired fund fees. That makes the headline figure look far higher than JEPI’s 0.35%[4]. Those costs are already reflected in each BDC’s payout and share price, and investors holding the BDCs directly would bear them anyway. The part BIZD itself adds is VanEck’s management fee.
That July drop from $0.4818 to $0.2391 is the kind of signal income investors learn to watch for, and it is exactly the sort of warning we cataloged in a free guide to the seven signs a big yield is about to get cut.
Why This Fund Stays Under the Radar
That same fee accounting is a big reason BIZD gets overlooked. Screeners that rank funds by expense ratio filter it out, and BDCs were dropped from major stock indexes years ago over the same disclosure issue. JEPI, by contrast, comes from a large asset manager with heavy distribution through advisors, so it lands in far more retirement accounts.
Who BIZD Could Suit, and Who Should Skip It
BIZD could work as a small income portion for retirees who want exposure to private credit, can live with checks that change each quarter, and can ride out price swings. BDC distributions are taxed mostly as ordinary income, which is why many investors hold them in tax-advantaged accounts. Retirees who rely on a predictable monthly check, or who can’t stomach losses on their principal, will likely be better served by steadier funds. Over the coming months, the things to track are BIZD’s year-end distribution, the path of short-term interest rates, and loan-default trends at the largest BDCs.
Contact [email protected] for any questions or corrections.
Ryne Mauck is an investment writer covering exchange-traded funds, retirement planning, and portfolio strategy. Through his work at 24/7 Wall St. and other investment platforms, including Seeking Alpha, he aims to provide clear, research-driven insights that help investors make more informed decisions while maintaining a long-term approach to investing.
Ryne holds a B.Sc. in Finance and an M.A. in Political Science. He is a formerly registered Municipal Advisor Representative and has passed the Series 50, Series 63, and Series 65 exams. His articles are not intended to be, nor should they be interpreted as, financial advice.